

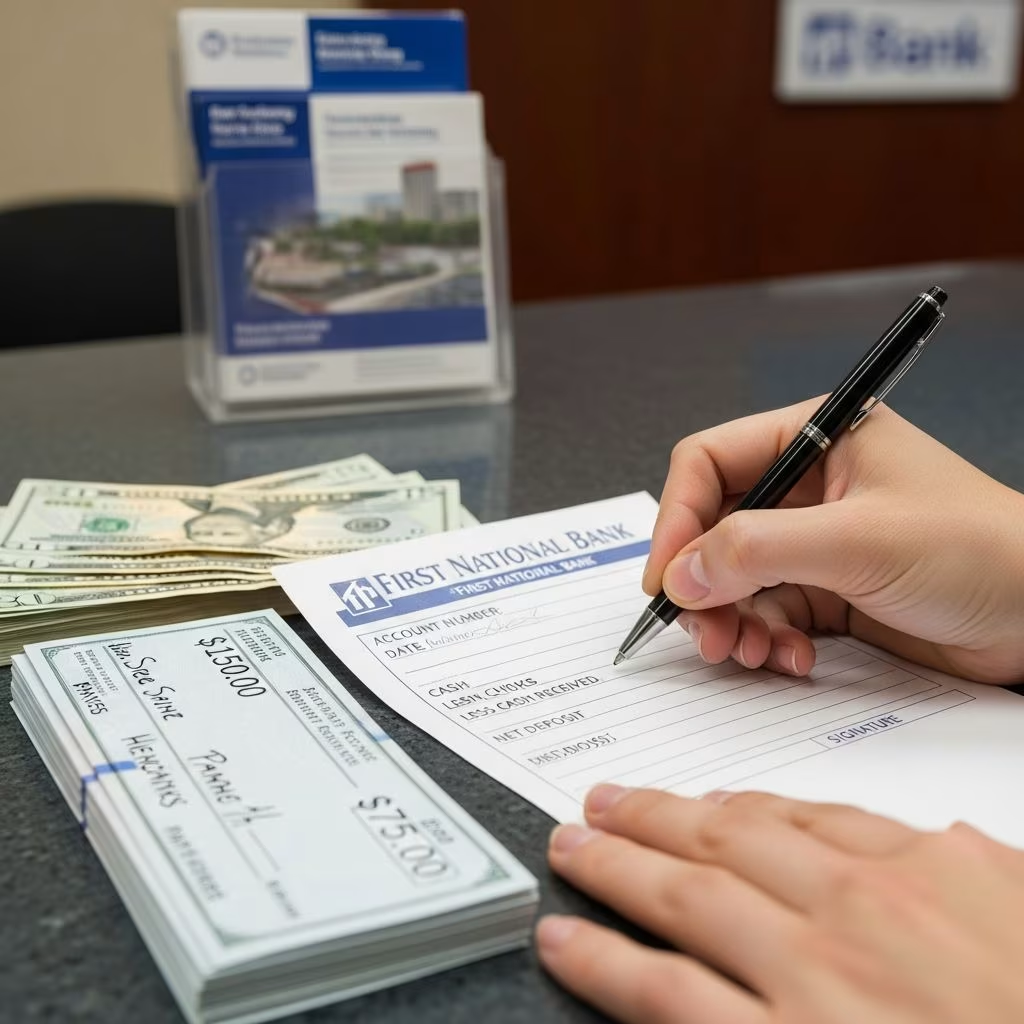
How to Fill Out a Deposit Slip: A Complete Banking Guide
Visiting a bank to deposit money is a routine financial activity for many individuals and businesses. Whether you’re depositing cash from a weekend shift, a business transaction, or collecting checks from clients, understanding how to properly fill out a deposit slip is an essential banking skill. A deposit slip is a form that documents your deposit transaction and ensures your funds are credited to the correct account. This comprehensive guide will walk you through the entire process of completing a deposit slip accurately and efficiently.
What Is a Deposit Slip?
A deposit slip, also known as a pay-in-slip or deposit ticket, is a standardized banking form provided by financial institutions to document deposit transactions. This form serves as an official record that itemizes the cash and checks being deposited into a specific bank account. When you visit your bank to make a deposit, the deposit slip acts as a communication tool between you and the bank teller, clearly indicating the amount and type of funds you’re depositing.
Deposit slips are typically pre-printed with your name and account number for security and accuracy purposes. Banks include blank deposit slips in the back of checkbooks provided to account holders, making them easily accessible for regular use. The form creates a documented transaction trail that protects both the depositor and the financial institution.
Key Information Included on Deposit Slips
Understanding what information appears on a deposit slip helps you fill it out more efficiently. Most deposit slips contain the following standard fields:
- Depositor’s Name: Your name as it appears on the account
- Account Number: Your unique bank account identifier
- Date: The specific date you’re making the deposit
- Cash Amount: The total value of bills and coins being deposited
- Check Details: Individual check amounts and check numbers
- Subtotal: Combined total of cash and checks before any withdrawals
- Withdrawal Amount: Any funds you wish to withdraw from the deposit (if applicable)
- Net Deposit Total: Final amount to be credited to your account
- Your Signature: Authorization confirming the deposit information
Step-by-Step Instructions for Filling Out a Deposit Slip
Step 1: Verify Your Account Information
Before you begin filling out your deposit slip, confirm that the pre-printed account information is correct. Your name and account number should match your banking records exactly. If you notice any discrepancies, contact your bank before proceeding. This verification step prevents deposits from being credited to the wrong account and saves time during processing.
Step 2: Enter the Deposit Date
Write the current date in the designated date field. Use the format your bank specifies, typically MM/DD/YYYY (month/day/year). Accuracy in dating your deposit slip is important for record-keeping and reconciliation purposes. The date helps banks track deposits chronologically and assists you in matching transactions to your account statements.
Step 3: List Cash Amounts
If you’re depositing cash, enter the total amount of currency you’re depositing in the designated cash section. Some deposit slips provide separate lines for different denominations (hundreds, fifties, twenties, tens, fives, ones, and coins), while others simply ask for a total cash amount. If your slip breaks down denominations, calculate each category carefully:
- Count all bills by denomination and multiply by their value
- Total all coin amounts separately
- Add bills and coins together for the total cash amount
Double-check your math to ensure accuracy. Banks will verify your cash total against what you’ve stated on the slip.
Step 4: Itemize Each Check
When depositing checks, list each check separately on the designated lines provided on the deposit slip. For each check, you’ll typically need to enter:
- The check number (usually located in the upper right corner)
- The amount of the check (written on the check face)
- The bank routing number or the bank name from which the check originates
Writing checks in the order they appear on the form helps maintain organization. Be precise with the amounts, as transcription errors can delay processing and cause reconciliation issues. If you have numerous checks to deposit, consider organizing them before arriving at the bank to streamline the process.
Step 5: Calculate Subtotals
After listing all cash and checks, calculate the subtotal by adding your total cash amount to the sum of all checks being deposited. This subtotal represents the total value of funds you’re depositing before any withdrawals. Most deposit slips have a clearly marked line for this calculation.
Step 6: Account for Any Withdrawals
If you need to withdraw cash from your deposit (common when depositing checks and wanting some cash back), enter the withdrawal amount in the designated field. Subtract this amount from your subtotal to determine your net deposit. For example, if your subtotal is $500 and you want $50 back in cash, your net deposit would be $450.
Step 7: Enter the Final Deposit Total
Calculate your final deposit total by subtracting any withdrawals from the subtotal. This is the amount that will be credited to your account. Enter this figure clearly in the total deposit field. Ensure this number is accurate, as the bank teller will verify it against the sum of the actual cash and checks you’ve submitted.
Step 8: Sign the Deposit Slip
Sign the deposit slip in the designated signature line. Your signature authorizes the deposit transaction and confirms that the information provided is accurate and complete. This signature serves as your acknowledgment of the deposit contents and protects both you and the bank.
Why Deposit Slips Matter for Banking Security
Deposit slips serve multiple critical functions in the banking system. For individual depositors, they provide essential documentation and protection. When you submit a deposit slip, you’re creating a verifiable record that proves you deposited specific funds on a particular date. If there’s ever a discrepancy between what you deposited and what appears in your account, the deposit slip serves as your proof of the transaction.
Banks rely on deposit slips as internal controls to prevent errors and fraud. When a teller receives your deposit slip, they compare the totals you’ve written against the actual cash and checks provided. This dual verification system catches mathematical errors before they’re recorded in the system. The deposit slip creates an audit trail that both you and your bank can reference for transaction verification and reconciliation.
Common Mistakes to Avoid When Filling Out Deposit Slips
Even experienced bank customers occasionally make errors when completing deposit slips. Being aware of common mistakes helps you avoid delays and complications:
- Mathematical Errors: Always double-check your addition. Subtotals and final totals should be accurate
- Illegible Handwriting: Write clearly so the teller can read all amounts and information accurately
- Incorrect Account Number: Verify the pre-printed account number matches your records
- Missing Check Details: Don’t forget to list individual checks; provide check numbers and amounts
- Unsigned Deposit Slip: Always sign the slip before submitting it to the teller
- Wrong Date: Ensure the date matches when you’re actually making the deposit
- Incomplete Information: Fill out all required fields; don’t leave blank spaces
Are Deposit Slips Still Relevant in Modern Banking?
While digital banking has transformed many aspects of personal finance, deposit slips remain relevant and widely used. Many banks continue to provide deposit slips with checkbooks and maintain them as part of their standard banking procedures. However, usage patterns have shifted as customers increasingly adopt alternative deposit methods.
Modern banking offers several alternatives to in-person deposits with deposit slips, including mobile check deposits, direct deposits, and electronic fund transfers. Many customers now use their smartphones to photograph checks and deposit them remotely, eliminating the need for physical deposit slips. Despite these technological advances, in-person deposits with deposit slips remain essential for customers who prefer traditional banking methods or need to deposit cash, which cannot be handled through mobile deposits.
What Happens After You Submit Your Deposit Slip
Understanding the post-submission process helps you track your deposit and anticipate when funds will be available. After you hand your deposit slip and funds to the bank teller, several steps occur:
The teller verifies that the information on your deposit slip matches the actual cash and checks provided. They’ll count the cash and confirm the check amounts align with what you’ve written. Once verified, the teller processes the deposit into the banking system and provides you with a receipt showing the total deposit amount, date, and time. This receipt serves as your proof of deposit and should be retained for your records.
The original deposit slip and your deposit remain with the bank for their records. A duplicate copy may be provided to you along with the receipt. Depending on the check types and your bank’s processing schedule, deposited checks typically become available within one to three business days. Cash deposits are usually credited immediately or within one business day.
Retaining Your Deposit Documentation
Proper record-keeping extends beyond the immediate deposit process. Maintain both your receipt and any duplicate deposit slip copies for at least several months or until you verify the deposit in your account statement. These documents serve important purposes:
- Proof that you made the deposit on a specific date
- Verification of the exact amounts deposited
- Reference material if questions arise about the transaction
- Documentation for business accounting and tax purposes
- Evidence in case of disputes or errors
Organize your deposit slips and receipts chronologically, either in physical files or by photographing them for digital storage. This documentation becomes invaluable during tax season or when reconciling your account.
Special Considerations for Business Deposits
Businesses that regularly make deposits may develop procedures for handling multiple deposit slips. Many companies designate specific employees to prepare and submit deposits, ensuring consistency and accountability. Businesses often use pre-numbered deposit slips to track deposits sequentially and detect any missing entries. For security purposes, some organizations require a second employee to verify deposit amounts before submission to the bank, adding an extra layer of accuracy and fraud prevention.
Frequently Asked Questions About Deposit Slips
Q: Can I deposit money without a deposit slip?
A: While it may be possible in some cases, banks strongly recommend using deposit slips for documentation and verification purposes. The deposit slip creates an official record of your transaction and protects both you and the bank.
Q: What if I make a mistake on my deposit slip?
A: Draw a single line through the error and write the correction nearby. Ensure you initial the change. If the error is significant, ask the teller for a fresh deposit slip rather than submitting one with multiple corrections.
Q: How long does it take for a deposit to be credited?
A: Cash deposits typically appear in your account immediately or within one business day. Checks usually take one to three business days to clear, depending on the bank’s processing schedule and the check’s origin.
Q: Can I deposit money on behalf of someone else?
A: Yes, you can deposit money into another person’s account by filling out their deposit slip with their account information. However, some banks may require specific authorization or additional documentation for third-party deposits.
Q: What should I do if my deposit slip doesn’t match my bank statement?
A: Contact your bank immediately with your deposit slip, receipt, and bank statement. The bank can investigate the discrepancy and ensure the correct amount was credited to your account. Keep your deposit documentation for reference during this process.
Q: Are pre-printed deposit slips necessary, or can I use blank ones?
A: Pre-printed deposit slips with your account information are preferable and more secure. They reduce the risk of errors and ensure your deposit is credited to the correct account. Blank slips may be available at bank locations but are less commonly used.
Q: Can I deposit checks without a deposit slip by using mobile banking?
A: Yes, many banks now offer mobile check deposit features that allow you to photograph and submit checks through their mobile app, eliminating the need for physical deposit slips. However, cash deposits still require in-person transactions with traditional deposit slips.
References
- Deposit Slip: Definition and Meaning — BooksTime. 2025. https://www.bookstime.com/articles/deposit-slip
- Deposit slip definition — AccountingTools. 2025. https://www.accountingtools.com/articles/deposit-slip
- Deposit Slip – Definition, How It Works, Benefits — Corporate Finance Institute. 2025. https://corporatefinanceinstitute.com/resources/wealth-management/deposit-slip/
- Do banks still use deposit slips? — Checks for Less. 2025. https://www.checksforless.com/business-checks-ordering-guide/are-deposit-slips-still-used-by-banks.aspx
- Greater Accuracy: Creating and printing deposit slips — Zil Money. 2025. https://zilmoney.com/what-is-a-deposit-slip-and-its-role-in-us-economic-payments/
- Deposit Slip — Merriam-Webster Dictionary. 2025. https://www.merriam-webster.com/dictionary/deposit%20slip
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


