

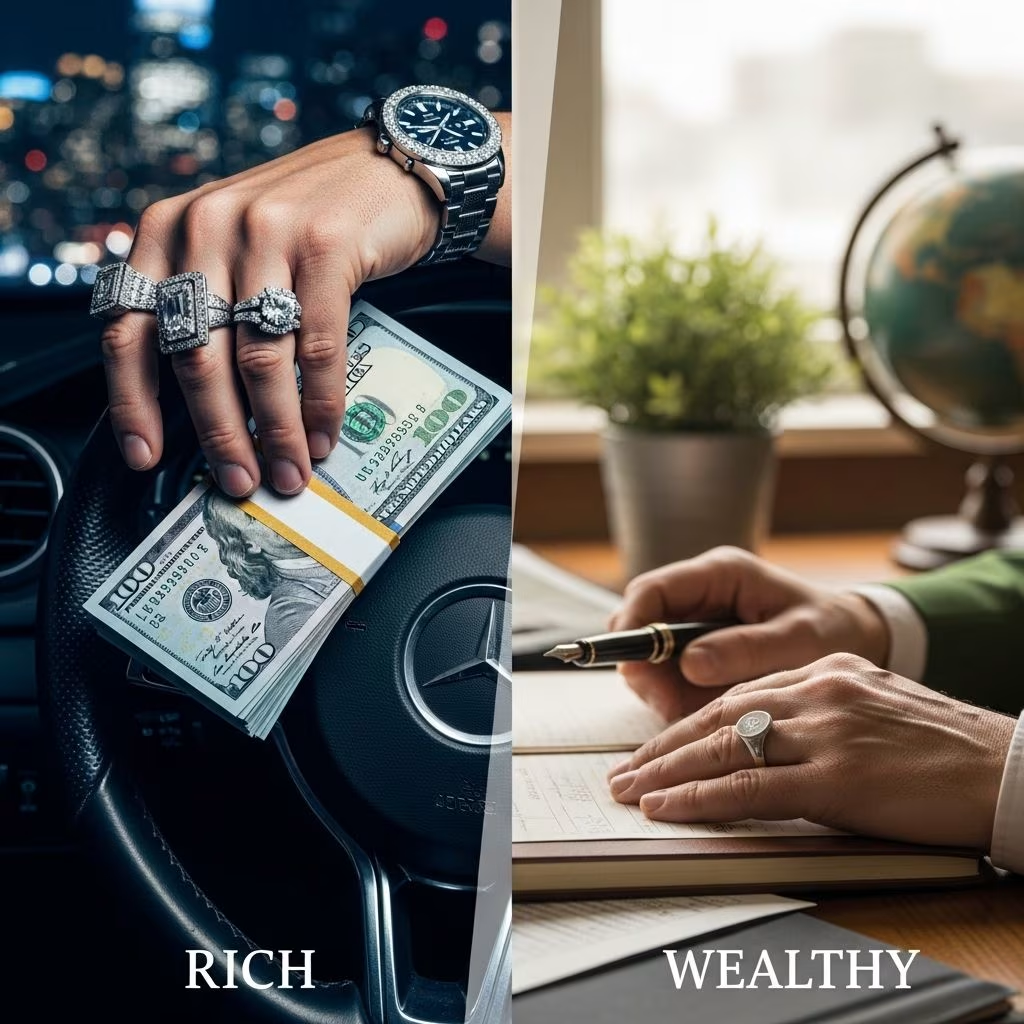
Many people dream of being rich, but being wealthy is a far more powerful and stable financial goal. Richness often focuses on what people can see: income, cars, houses, and luxury lifestyles. Wealth focuses on what truly matters: assets, net worth, and the ability to stop working while still maintaining your lifestyle.
This article breaks down the difference between rich vs wealthy, explains the three key distinctions, and shows you how to shift from chasing income to building sustainable wealth.
What does it mean to be rich?
When people say someone is “rich,” they usually mean that person has a high income or spends a lot on visible status symbols like luxury cars, designer clothes, or an expensive home in a desirable area. Richness is often measured by what you earn and what you spend, not by what you actually own.
However, a high income alone does not guarantee financial security. Someone can earn a lot of money yet still live paycheck to paycheck if their expenses are just as high—or even higher—than their income. Research on high-income households shows that many still carry significant debt and have low savings, especially when lifestyle inflation keeps pace with raises and bonuses.
- Rich people often:
- Have high salaries or business income
- Spend heavily on lifestyle and appearance
- May rely on debt to fund their lifestyle
- Focus more on income than on assets or net worth
Being rich, in this sense, is often fragile. If the job disappears, the business slows down, or debt payments rise, the entire lifestyle can quickly become unsustainable.
What does it mean to be wealthy?
Being wealthy is not just about earning a lot. It is about building enough assets so that you can cover your expenses without needing to work if you choose not to. Wealth is closely tied to net worth—what you own minus what you owe—and your ability to generate income from savings and investments rather than from labor alone.
Wealthy people focus on accumulating and protecting assets such as:
- Cash and emergency savings
- Retirement accounts and brokerage investments
- Real estate and other appreciating assets
- Businesses or side ventures that generate income
Instead of using money mainly to display status, wealthy people use money as a tool to buy back their time and create long-term security for themselves and their families.
Example: If your expenses are $5,000 per month and you have $30,000 in savings, you have about six months of expenses covered. If, over time, your invested assets grow enough to generate $5,000 per month in sustainable investment income, you have effectively reached a level of wealth that can support your lifestyle without earned income.
Rich vs wealthy: Side-by-side comparison
| Aspect | Rich | Wealthy |
|---|---|---|
| Primary focus | High income and visible lifestyle | Net worth, assets, and financial independence |
| Income vs expenses | Income may be high, but expenses often match or exceed it | Expenses are kept below income to allow saving and investing |
| Use of debt | Commonly used for lifestyle and consumption | Used carefully, mainly for investments with clear returns |
| Security | Vulnerable if income stops | More resilient due to assets and diverse income streams |
| Time freedom | Must keep working to fund lifestyle | Can choose whether or not to work |
3 key differences between being rich and being wealthy
The contrast between rich vs wealthy comes down to three main areas: net worth, expenses, and investment behavior.
1. Net worth
Your net worth is the most accurate snapshot of your financial health. It is calculated by subtracting your total debts from your total assets:
Net worth = Total assets − Total liabilities
Assets include cash, investments, real estate, and other valuable property. Liabilities include credit card balances, student loans, car loans, mortgages, and any other debts you owe. Government and central bank surveys of consumer finances consistently use net worth, not income, as the central measure of household wealth.
- A rich person may have a high income but also carry a lot of debt and limited savings, resulting in a low or even negative net worth.
- A wealthy person may have a more modest income but steadily increases net worth by saving, investing, and minimizing unnecessary debt.
This is why someone earning less can sometimes be wealthier than someone with a much higher salary: the key difference is what they keep and own, not just what they make.
2. Expenses
The second major difference is how each group handles expenses. Rich people often let their spending grow along with their income—a phenomenon known as lifestyle inflation. That can mean bigger homes, more expensive cars, frequent luxury travel, and constant upgrades in every area of life.
Wealthy people, by contrast, are intentional about keeping their expenses well below their income. They consciously avoid overspending so they can save and invest a significant portion of what they earn.
- Rich mindset: “I earn more, so I can spend more.”
- Wealth mindset: “I earn more, so I can invest more and buy my freedom.”
Wealthy people may still enjoy comforts and experiences, but they balance enjoyment today with security tomorrow. They are also cautious with debt, typically reserving it for strategic purposes like buying a home or growing a business, rather than using it heavily for discretionary consumption.
3. Investment and long-term focus
The third key difference is investment behavior. Rich individuals sometimes concentrate on earning more in the short term without creating a long-term plan for financial independence. Wealthy individuals consistently prioritize turning earned income into invested capital that can grow over time.
Wealth-building strategies commonly include:
- Regular contributions to retirement accounts and diversified investment portfolios
- Buying assets that appreciate or generate cash flow, such as property or index funds
- Building businesses or side hustles that can eventually run with less day-to-day involvement
Decades of financial research show that disciplined saving and diversified long-term investing, especially in broad stock market indices, can significantly grow wealth thanks to compound returns. Wealthy people align their financial decisions with this long-term perspective, rather than prioritizing short-lived status purchases.
How to become wealthy: Practical steps
The good news is that you do not need to be born into money to become wealthy. By managing your income, debt, and investments wisely over time, you can steadily build real wealth. Here are the core steps.
Keep track of your net worth
Since net worth is the true measure of your progress, regularly tracking your net worth is essential. This helps you see whether you are moving closer to or further from financial independence.
To track your net worth:
- List all your assets: checking and savings accounts, retirement funds, investment accounts, real estate equity, and other valuables.
- List all your liabilities: mortgages, student loans, credit card balances, car loans, personal loans, and any other debts.
- Subtract total liabilities from total assets.
Over time, focus on increasing assets and reducing liabilities. Many financial experts recommend checking your net worth at least once or twice a year to stay on track.
Pay off debt, starting with high-interest debt
High-interest debt—especially credit card debt—can dramatically slow or even reverse your progress toward wealth. The interest rates on such debt often far exceed the average long-term returns from investments, making it critical to reduce these balances as quickly as possible.
- Prioritize paying off high-interest debts first while making minimum payments on lower-rate loans.
- Avoid taking on new consumer debt for non-essential purchases.
- Once high-interest debt is gone, redirect the payments you were making into savings and investments.
The less of your monthly income goes toward interest and debt repayment, the more you can put to work building assets—one of the defining characteristics of true wealth.
Don’t splurge on unnecessary expenses
Wealthy people understand that every dollar has a job. That job might be covering essentials, funding meaningful experiences, or building future security. What they avoid is allowing too many dollars to be lost to impulse purchases or status-driven spending.
To align your spending with a wealth-building mindset:
- Create a realistic, values-based budget that reflects what truly matters to you.
- Live below your means so that saving and investing become automatic.
- Pause before big purchases and ask: “Will this move me closer to or further from financial independence?”
- Be cautious about lifestyle upgrades when your income rises; prioritize increasing savings and investments first.
Long-term wealth is the result of many small, smart decisions made consistently, not a single dramatic change.
Build passive income streams
One hallmark of being wealthy is having multiple income streams, particularly forms of income that do not require constant active labor. This is often called passive income, although in reality most passive-income sources require some effort to set up and maintain.
Examples of potential passive or semi-passive income sources include:
- Dividends from stocks or mutual funds
- Rental income from real estate
- Royalties from books, courses, or intellectual property
- Profits from a business that can operate with limited day-to-day involvement
Research on household wealth shows that business ownership and investment income are significant contributors to net worth among higher-wealth households, beyond salary alone. By steadily growing your assets and cultivating additional income streams, you move closer to the point where work becomes optional rather than necessary.
Rich vs wealthy: Which is better?
In the long run, being wealthy is more sustainable and freeing than simply being rich. A rich lifestyle without strong underlying assets can disappear quickly if income stops or debt grows. Wealth, by contrast, gives you options—where to live, how to work, how much time to spend with family, and how to handle emergencies without panic.
Choosing to pursue wealth means:
- Focusing on net worth rather than just income
- Spending below your means to create room for investing
- Managing and eliminating high-interest debt
- Investing consistently for the long term
- Building assets and income streams that support your life, even when you are not working full-time
Frequently Asked Questions (FAQs)
Is wealthy considered rich?
The words are often used interchangeably in everyday conversation, but in personal finance they describe different things. Being rich usually refers to having a high income or expensive lifestyle, while being wealthy means having substantial net worth and the ability to maintain your lifestyle without relying solely on a paycheck.
How much money is considered wealthy?
There is no single universal number that defines being wealthy, because it depends on your location, lifestyle, and expenses. Some studies classify households in the top 10% of net worth or with several million dollars in assets as wealthy, but the more practical definition is this: you are wealthy when your assets and investment income can reliably cover your living costs for the long term.
Can you be rich but not wealthy?
Yes. A person can earn a very high salary, live in a large home, and drive luxury cars yet have little savings and substantial debt. If that person lost their job or income source, their lifestyle could quickly become unsustainable. High income without strong assets or savings is the classic example of being rich but not truly wealthy.
Can you be wealthy on an average income?
Over time, it is possible. Many households build significant net worth through consistent saving, careful debt management, and long-term investing, even without exceptionally high incomes. The key is to live below your means, avoid high-interest debt, and invest regularly over many years so compounding can work in your favor.
What should I focus on first if I want to become wealthy?
Start by understanding your current financial picture: track your net worth, review your budget, and list all debts. Then, prioritize paying down high-interest debt, build a basic emergency fund, and begin investing for the long term. As you make progress, continue to control expenses and increase the percentage of your income that goes toward savings and investments.
References
- Report on the Economic Well-Being of U.S. Households in 2023 — Board of Governors of the Federal Reserve System. 2024-05-22. https://www.federalreserve.gov/publications/report-economic-well-being-us-households.htm
- Consumer Finances and the Economic Challenges Facing U.S. Households — Federal Reserve Bank of St. Louis. 2023-06-01. https://www.stlouisfed.org/publications/regional-economist/2023/06/consumer-finances-economic-challenges
- Survey of Consumer Finances (SCF) — Board of Governors of the Federal Reserve System. 2023-10-18. https://www.federalreserve.gov/econres/scfindex.htm
- Key Findings on American Household Wealth — Board of Governors of the Federal Reserve System. 2023-10-18. https://www.federalreserve.gov/publications/distribution-of-wealth-in-the-united-states.htm
- Shining a Light on Debt in the United States — Consumer Financial Protection Bureau. 2024-01-10. https://www.consumerfinance.gov/about-us/blog/shining-a-light-on-debt-in-the-united-states/
- Global Wealth Report 2023 — UBS. 2023-09-15. https://www.ubs.com/global/en/wealth-management/insights/global-wealth-report.html
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


