

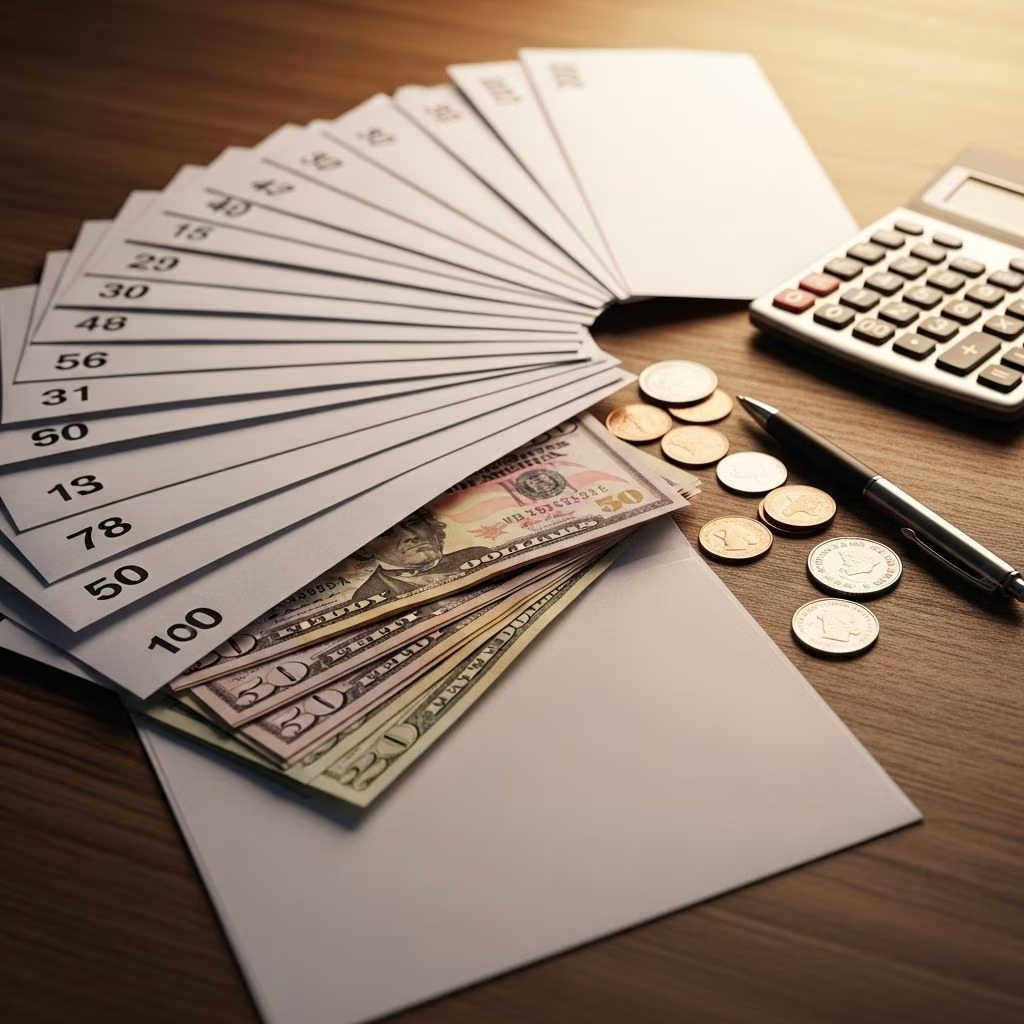
The 100-day envelope challenge is a simple, structured savings game that helps you set aside small amounts of cash every day until you’ve saved over $5,000. It’s popular because it’s easy to start, highly visual, and can fit a wide range of financial goals.
Using just envelopes, a pen, and consistent contributions, this challenge turns the abstract idea of saving into something tangible and motivating. Over roughly three months, you’ll build a lump sum that can kick-start your financial progress.
What Is The 100-Day Envelope Challenge?
The 100-day envelope challenge is a short-term savings system in which you label 100 envelopes with specific dollar amounts, then steadily fill them with cash over 100 days. By the end of the challenge, every envelope is funded, and your total savings reach a few thousand dollars.
Many people respond well to visual systems and simple rules, which is why this type of savings challenge can be effective for changing behavior and building better financial habits over time.
How The 100-Day Envelope Challenge Works
The traditional version of the challenge is straightforward:
- Gather 100 envelopes.
- Label each envelope from 1 to 100.
- Each day, pick one envelope.
- Put the amount of cash written on the envelope inside it (e.g., envelope 47 gets $47).
- Seal the envelope and store it somewhere safe.
You continue this process until each of the 100 envelopes is filled once. Whether you pick them in order or randomly, the total amount you’ll save is the same, as long as you complete all the envelopes.
Random Draw vs. In Order
You can choose one of two main approaches:
| Method | How It Works | Best For |
|---|---|---|
| In Order | Start with envelope 1 and go up to 100, increasing the amount daily. | People who prefer predictability and a steady increase in savings. |
| Random Draw | Shuffle or mix the envelopes and draw one at random each day. | Those who like variety and a surprise element in their savings routine. |
Both options work, but random draws can lead to larger amounts on some days and smaller amounts on others, which may require a bit more flexibility in your daily budget.
Savings Breakdown: How You Reach Over $5,000
In the classic setup, you label envelopes from $1 to $100. When you fill all 100, your savings equal the sum of the numbers from 1 through 100:
1 + 2 + 3 + … + 100 = 5,050
That means completing the 100-day envelope challenge gives you $5,050 in savings. The timeline—just a bit over three months—makes it a relatively fast way to accumulate a substantial amount of money compared with casual, unstructured saving.
Who Would Benefit From A 100-Day Envelope Challenge?
The 100-day envelope challenge is especially helpful if you want a clear savings target with a short deadline. It is also useful for people who like physical, visual systems over purely digital methods.
Research suggests that using simple, rule-based systems and clear targets can make saving easier, particularly when people struggle with self-control or feel overwhelmed by long-term goals.
Situations Where This Challenge Works Well
You might benefit from the challenge if you:
- Have a big purchase coming up – such as furniture, appliances, or a down payment on a major item.
- Want to pay down high-interest debt faster – you can redirect the lump sum toward credit cards or other costly loans.
- Need to save for the holiday season – setting aside money in advance can reduce reliance on credit and holiday stress.
- Have a vacation planned – funding your trip with savings instead of debt can lower financial pressure afterward.
- Want to build an emergency fund quickly – experts often recommend having at least several months of expenses set aside for emergencies.
- Prefer a simple, low-tech savings system – envelopes and cash can feel more concrete than numbers in an app.
Who Might Struggle With This Challenge?
The challenge may be harder to maintain if you:
- Have very irregular income and cannot predict cash flow over the next three months.
- Are already working with a tight budget and have limited ability to set money aside.
- Do not feel comfortable keeping significant cash at home.
- Prefer fully digital banking and want to avoid handling physical money.
In these situations, a modified version of the challenge or a different savings approach may be a better fit.
Why Should You Try The 100-Day Envelope Savings Challenge?
There are multiple reasons this specific challenge has become so popular. It offers a clear goal, a firm timeline, and a structure that makes daily decisions easier. Behavioral economists have documented that such pre-commitment strategies and mental accounting can help people stick to savings plans they otherwise might abandon.
Key Benefits And Motivations
- Fast results – Saving $5,050 in about 100 days gives you visible progress in a relatively short period.
- Built-in accountability – With 100 envelopes to complete, you can visually track your progress and see how far you’ve come.
- Simple rules – The method doesn’t require complex math or financial knowledge.
- Flexible implementation – You can adjust the amounts, schedule, or format (cash vs. transfers) to suit your situation.
- Habit-building – Daily savings contributions help reinforce a routine of paying yourself first.
Can You Really Save $5,000 With The 100-Day Envelope Challenge?
Yes, if you follow the standard rules and complete all the envelopes from $1 to $100, you will save $5,050. The math is built into the structure: you are systematically covering every amount from 1 through 100 exactly once.
However, whether you can personally sustain this depends on your income, expenses, and flexibility. As with any savings plan, the challenge is most effective when it is realistic relative to your budget.
What If Daily Saving Is Too Difficult?
You can still reach a meaningful savings goal by adjusting the schedule:
- Weekly version – Pick and fill several envelopes per week instead of every day.
- Bi-weekly version – Align envelope-filling with paydays if you’re paid every two weeks.
- Monthly version – Choose a smaller number of envelopes to complete each month.
If needed, you can also lower the amounts written on the envelopes—for example, $1–$50 instead of $1–$100—reducing the total saved but making the challenge more sustainable.
What You Need For A Successful 100 Envelope Savings Challenge
Getting started is inexpensive and simple. You do not need specialized products or software. Most of the setup can be done in a few minutes.
Basic Supplies
- 100 envelopes – Standard or colorful envelopes both work; choose something you’ll enjoy using.
- A marker or pen – To label each envelope with its dollar amount.
- A storage container – A box, basket, or drawer to keep envelopes organized and out of sight.
- A tracking system – This could be a notebook, spreadsheet, savings tracker printable, or a note on your phone.
- Cash or digital transfers – Physical money for envelopes or a separate savings account to simulate each envelope.
Optional Tools To Stay Organized
- Printed trackers – Visual charts you can color in as you complete each envelope.
- Budgeting app – To make sure you can safely set aside each amount without harming essential bills.
- Calendar reminders – Alerts to help you remember your daily or weekly envelope task.
Tips To Make The Challenge Work For You
- Align it with your pay cycle – Schedule higher-value envelopes on weeks when your income is higher.
- Prepare small bills in advance – Withdraw a mix of denominations so filling envelopes is convenient.
- Store cash securely – Use a safe or a discreet, locked location if you’re keeping money at home.
- Review your budget first – Ensure that you can cover essentials (housing, food, utilities, debt minimums) before committing.
Pros And Cons Of The 100-Day Envelope Challenge
Like any savings strategy, the 100-day envelope challenge has strengths and limitations. Understanding both can help you decide whether it suits your needs.
Pros
- Doesn’t require much money to start – On some days you only need $1 or $2. You can begin with minimal supplies and adjust as you go.
- Highly visual and tangible – Watching envelopes fill up can be very motivating and satisfying.
- Flexible and customizable – You can shorten or extend the timeline, change amounts, or switch to a digital variation.
- Encourages consistent saving – Regular contributions reinforce the habit of setting money aside.
- Clear goal amount – Knowing you’re aiming for just over $5,000 gives you a concrete reason to stay on track.
Cons
- Daily commitment can be challenging – Busy schedules, irregular income, or unexpected expenses may cause you to miss days.
- Some days are more expensive – When you pick higher numbers (like 80–100), those days can strain your budget.
- Security risk with cash – Keeping thousands of dollars in physical envelopes at home carries theft or loss risk.
- May not fit very low incomes – For some households, setting aside up to $100 in a single day is simply not feasible.
Other Money-Saving Challenges To Try Instead
If the 100-day envelope challenge feels too intense or doesn’t match your financial situation, there are other savings challenges you can use to build momentum.
1. 52-Week Savings Challenge
This challenge spreads saving over an entire year. One common version is:
- Week 1: save $1
- Week 2: save $2
- Week 3: save $3
- … up to week 52: save $52
If completed, this yields $1,378 in a year. It’s slower-paced than the 100-day challenge and may feel more manageable.
2. 200 Envelope Challenge
The 200 envelope challenge works similarly to the 100-day version but uses more envelopes and often smaller amounts. You can:
- Label 200 envelopes with amounts that fit your budget (for example, $1–$50 repeated or customized amounts).
- Fill a set number of envelopes per week or month.
This approach allows you to spread savings over a longer period or to target a different total amount while still enjoying a gamified system.
3. No-Spend Challenge
In a no-spend challenge, you commit to avoiding all non-essential spending for a set period, such as a week or a month. Essential expenses—like housing, utilities, and groceries—are allowed, but optional purchases are paused. Extra money left over can then be moved into savings or used for debt repayment.
4. Round-Up Or “Spare Change” Challenge
Many banks and apps allow you to round up purchases to the nearest dollar and transfer the difference into savings. Over time, these small automatic contributions can accumulate without requiring daily manual effort.
5. Custom Goal-Based Challenge
You can also design your own challenge focused on a specific goal:
- Choose a target amount (e.g., $2,000 for an emergency fund).
- Decide on a time frame (e.g., 6 months).
- Break the goal into equal weekly or monthly contributions.
Creating a personalized plan lets you match your savings obligations to your income and essential expenses more precisely.
Try The 100-Day Envelope Challenge Today
If you want a simple, fast way to save a few thousand dollars, the 100-day envelope challenge can be a powerful tool. It takes minimal supplies, offers visible progress, and gives you a clear savings target to aim for.
Step-By-Step Quick Start
- Decide on your target amount (e.g., $5,050) and confirm that your budget can support it.
- Gather 100 envelopes, a pen, and a safe storage location.
- Label the envelopes from 1 to 100, or with customized amounts that fit your finances.
- Choose your schedule: daily, weekly, or another realistic pace.
- Fill each envelope according to the plan and record your progress in a tracker.
- When all envelopes are filled, deposit or allocate the lump sum toward your goal—emergency savings, debt, or a specific purchase.
By approaching it as a flexible framework rather than a rigid rule, you can adapt the 100-day envelope challenge to your life and use it to build lasting savings habits.
Frequently Asked Questions (FAQs)
Q: Do I have to use physical cash for the 100-day envelope challenge?
A: No. You can simulate the envelopes digitally by labeling 100 lines in a spreadsheet or note app. Each day, transfer the envelope amount from your checking account into a separate savings account and mark that envelope as complete.
Q: What if I miss a day during the challenge?
A: Missing a day does not mean you have failed. You can either double up on a future day, extend your timeline by a day, or shift to a weekly schedule. The goal is to complete all envelopes eventually, not to be perfect.
Q: Is the 100-day envelope challenge safe if I keep cash at home?
A: Keeping large amounts of cash at home carries risks, including theft, loss, or damage. If security is a concern, consider using a locked safe or replacing physical cash with transfers to a protected savings account at a regulated financial institution.
Q: Can I change the amounts on the envelopes?
A: Yes. The standard 1–100 setup leads to $5,050 saved, but you can adjust the range or specific amounts based on what you can realistically afford. The important part is consistency and a clear plan.
Q: How should I use the money once the challenge is complete?
A: Common uses include starting or boosting an emergency fund, paying down high-interest debt, funding a planned purchase, or saving for upcoming expenses like tuition or travel. Many financial experts recommend prioritizing an emergency fund and high-interest debt first to improve long-term financial stability.
References
- Thaler, Richard H. Mental Accounting Matters. — Journal of Behavioral Decision Making. 1999-09-01. https://doi.org/10.1002/(SICI)1099-0771(199909)12:3%3C183::AID-BDM318%3E3.0.CO;2-F
- Madrian, Brigitte C., & Shea, Dennis F. The Power of Suggestion: Inertia in 401(k) Participation and Savings Behavior. — Quarterly Journal of Economics. 2001-11-01. https://doi.org/10.1162/003355301753265543
- Soman, Dilip & Cheema, Amar. Earmarking and Partitioning: Increasing Saving by Low-Income Households. — Journal of Marketing Research. 2011-11-01. https://doi.org/10.1509/jmkr.48.SPL.S14
- Consumer Financial Protection Bureau. Start Small, Save Up: A Financial Empowerment Toolkit for Workers. — Consumer Financial Protection Bureau. 2020-02-01. https://files.consumerfinance.gov/f/documents/cfpb_start-small-save-up_toolkit.pdf
- FDIC. How to Save Money. — Federal Deposit Insurance Corporation. 2023-01-10. https://www.fdic.gov/resources/consumers/money-smart/teach/online/consumers/module-5/index.html
- Financial Consumer Agency of Canada. No-Spend Challenge: How Taking a Break from Spending Can Help You Save. — Financial Consumer Agency of Canada. 2023-04-05. https://www.canada.ca/en/financial-consumer-agency/services/financial-tools-resources/no-spend-challenge.html
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


