

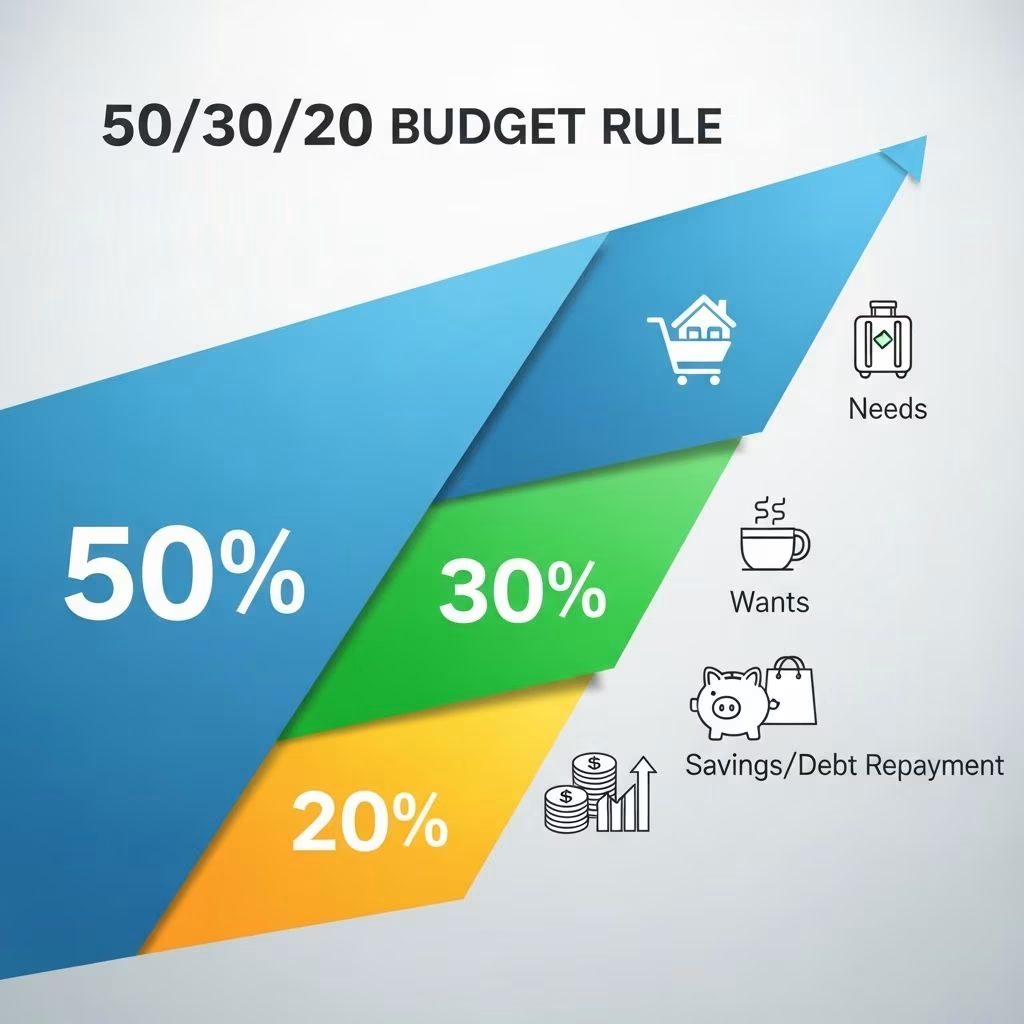
The 50/30/20 budget rule is a simple, flexible way to organize your money so you can cover essential expenses, enjoy your life, and still make steady progress toward savings and debt-free living. Instead of tracking dozens of tiny categories, you divide your after-tax income into just three buckets: needs, wants, and savings or debt payoff.
This guide explains what the 50/30/20 rule is, how it works, how to calculate your numbers, and how to adjust the percentages to fit your real life. You will also see examples, practical tips, and answers to common questions so you can start using this method with confidence.
What Is the 50/30/20 Budget Rule?
The 50/30/20 rule is a percentage-based budgeting method that splits your after-tax income into three main categories:
- 50% for needs – essential costs you must pay to live and work
- 30% for wants – nonessential expenses that add joy and comfort
- 20% for savings and extra debt payments – money for future goals and faster payoff of what you owe
Because you are working with three broad categories instead of a long list of line items, this approach can be easier to start and maintain than a very detailed budget, especially if you are new to managing money.
How the 50/30/20 Rule Works
To apply the rule, you first calculate your monthly take-home pay (what you receive after income taxes). Then you allocate that amount into the three buckets using the 50%, 30%, and 20% guidelines.
At a high level, the method helps you:
- Cover the basics without overspending
- Put boundaries around lifestyle spending
- Make saving and debt repayment a consistent habit
Step 1: Find Your After-Tax Income
Your starting point is your after-tax income (also called take-home pay). This is the amount you receive once mandatory income taxes are taken out. Many official budgeting guides recommend using this number rather than your gross (before-tax) income to keep the plan realistic.
If you are a salaried employee and taxes are withheld, look at your paycheck:
- Start with your net pay (the amount actually deposited to your account)
- Do not subtract deductions like retirement contributions or health insurance; those can be counted within your budget buckets if needed
If your income varies (for example, from freelance or hourly work), you can use an average of the last three to six months to estimate your monthly after-tax income.
Step 2: Calculate the 50/30/20 Amounts
Once you know your take-home pay, multiply it by the target percentages. Here is a simple table for a monthly take-home pay of $4,000:
| Category | Percentage | Dollar amount (example: $4,000 income) |
|---|---|---|
| Needs | 50% | $2,000 |
| Wants | 30% | $1,200 |
| Savings & extra debt | 20% | $800 |
These numbers become your monthly spending targets. Over time, the goal is to bring your actual spending as close to these targets as is reasonable for your situation.
What Counts as a “Need” (50%)?
Needs are expenses that are necessary to maintain a basic standard of living and allow you to work, stay healthy, and keep a safe place to live.
Common examples of needs include:
- Rent or mortgage payments
- Utilities (electricity, water, basic internet, heat)
- Basic groceries and household essentials
- Transportation to work or school (fuel, public transit, basic car expenses)
- Health insurance premiums and essential medical costs
- Child care required to be able to work
- Minimum payments on credit cards, student loans, and other debts
A simple way to decide whether something belongs in the needs category: ask yourself, “Would not paying this bill threaten my housing, health, safety, or ability to earn income?” If the answer is yes, it is likely a need.
What Counts as a “Want” (30%)?
Wants are purchases that improve your quality of life but are not strictly necessary for survival or basic functioning. These are often the most enjoyable parts of your budget and a key reason many people like the 50/30/20 rule: it allows for guilt-free spending within a clear limit.
Typical wants include:
- Dining out, coffee shops, and takeout meals
- Streaming services and entertainment subscriptions
- Vacations and weekend trips
- Hobbies and nonessential shopping (clothes beyond the basics, home decor, gadgets)
- Upgrades such as a larger apartment than you strictly need, or premium phone plans
Sometimes an expense is partly a need and partly a want. For example, a car is a need if you rely on it to get to work, but choosing a luxury model makes part of that payment a want. Use your judgment and stay consistent with how you categorize gray areas.
What Counts as Savings and Debt Repayment (20%)?
The final 20% of your income goes toward savings and extra debt payments. This is the portion that helps you build security, prepare for big goals, and reduce interest costs over time.
This category usually includes:
- Contributions to an emergency fund
- Retirement contributions (401(k), IRA, pension, etc.)
- Saving for a home down payment, education, or other major goals
- Paying more than the minimum on credit cards, personal loans, or student loans
If you have high-interest debt, many financial educators recommend prioritizing extra payments on those balances because reducing costly interest can significantly improve your long-term financial position.
Benefits of the 50/30/20 Budget Rule
The 50/30/20 rule has become a popular framework in banking, financial wellness programs, and personal finance education because it offers several practical advantages.
- Simplicity: You only track three broad categories instead of many small ones.
- Clarity: You can easily see whether housing or lifestyle spending is crowding out savings.
- Flexibility: The framework works at different income levels and can be adjusted.
- Built-in savings: Allocating 20% to savings makes future goals part of the plan instead of an afterthought.
- Compatible with tools: Many banks and budgeting apps support this style of budgeting, making tracking easier.
Limitations and When the 50/30/20 Rule May Not Fit
Even though the rule is widely recommended, it does not work perfectly for everyone. Your location, income, and family situation can make the default percentages difficult to follow.
Common challenges include:
- High cost of living: In expensive housing markets, rent or mortgage alone can exceed 50% of take-home pay, leaving little room for other needs.
- Low or unstable income: If your income is low or varies month to month, you may temporarily need a higher share for needs and a lower share for wants and savings.
- Large existing debts: If you owe a lot in loans or credit cards, sticking to only 20% for savings and extra debt may feel too slow.
Because of these realities, financial institutions often emphasize that the 50/30/20 split is a starting point, not a rigid rule. You can adjust the percentages while keeping the same basic structure of needs, wants, and savings.
How to Adjust the 50/30/20 Rule for Your Situation
If the standard breakdown does not fit, you can modify it while preserving the core idea: cover essentials, limit lifestyle creep, and always dedicate some share to your future.
Common Alternative Splits
- 60/20/20: 60% needs, 20% wants, 20% savings – useful if you have higher unavoidable expenses.
- 70/15/15: 70% needs, 15% wants, 15% savings – sometimes used by households in very high-cost areas or during tight periods.
- 40/30/30: 40% needs, 30% wants, 30% savings – a more aggressive savings plan if your fixed costs are low.
As your income grows or you reduce debts, you can gradually shift the percentages to invest more in savings and long-term goals.
Prioritizing Within the 20% Category
Within the 20% savings and debt bucket, you can order your goals. A common approach is:
- Build a basic emergency fund (for example, one month of expenses)
- Make extra payments on high-interest debt
- Increase retirement contributions, especially to get any employer match
- Save for medium- and long-term goals (home, education, business, etc.)
Step-by-Step: How to Start Using the 50/30/20 Budget
You do not need to have perfect numbers from day one. The goal is steady improvement. Here is a straightforward process to get started:
1. Calculate Your Monthly Take-Home Pay
Gather your pay stubs or bank statements and total your after-tax income for a month. If you are paid weekly or biweekly, convert it to a monthly figure by multiplying your average paycheck by the number of paychecks per month.
2. Work Out Your 50/30/20 Targets
Multiply your monthly income by 0.50, 0.30, and 0.20. Write down the results as your tentative limits for needs, wants, and savings/debt.
3. Track Your Current Spending
Review your last one to three months of transactions. Sort each expense into needs, wants, or savings/debt. Many people discover that their actual percentages differ from the guideline, which gives you a clear picture of where to adjust.
4. Make Adjustments
If your needs are above 50%, look for ways to slowly reduce them, such as renegotiating bills, considering a less expensive housing option when your lease ends, or cutting transportation costs. If wants are taking more than 30%, decide which discretionary expenses you are willing to reduce or pause while you work toward your goals.
5. Automate Savings and Debt Payments
Setting up automatic transfers or contributions can make the 20% savings goal easier to hit. For example, schedule a transfer to your savings account right after each paycheck is deposited, and set automatic payments for extra debt reduction. Many banks and employers offer automatic transfers and direct deposit splitting so you can send a portion of your income directly into savings.
6. Review and Refine Regularly
Your budget is a living plan. Revisit it every few months or whenever your income or expenses change. Adjust your categories or percentages to stay aligned with your priorities.
Example of a 50/30/20 Budget in Action
Suppose your monthly after-tax income is $3,500. Here is how a 50/30/20 budget might look:
| Category | Target amount | Example items |
|---|---|---|
| Needs (50%) | $1,750 | Rent: $1,100; Utilities & internet: $200; Groceries: $300; Transportation: $100; Minimum debt payments: $50 |
| Wants (30%) | $1,050 | Dining out & coffee: $250; Streaming & entertainment: $80; Shopping & hobbies: $300; Travel savings: $420 |
| Savings & extra debt (20%) | $700 | Emergency fund: $200; Retirement contributions: $300; Extra credit card payment: $200 |
Your exact categories and amounts will differ, but this example shows how each dollar has a clear purpose.
Tips to Make the 50/30/20 Rule Work Better
- Start where you are: If you cannot hit 20% savings right away, begin with a smaller percentage and gradually increase it.
- Use separate accounts: Consider separate bank accounts for bills, spending money, and savings to reduce the temptation to overspend.
- Be realistic about needs: Avoid labeling wants as needs. This keeps your budget honest and effective.
- Protect your emergency fund: Use it for real emergencies and rebuild it as soon as possible after you tap it.
- Revisit big expenses: Housing, transportation, and insurance often have the biggest impact. Checking these regularly can free up a lot of room in your budget.
Frequently Asked Questions (FAQs)
Q: Is the 50/30/20 rule based on gross income or net income?
A: The 50/30/20 rule is typically applied to after-tax (net) income, meaning the amount you receive after income taxes are deducted from your paycheck.
Q: What if my needs are more than 50% of my income?
A: If your essential bills exceed 50%, adjust the percentages temporarily (for example, 60/20/20) and look for long-term ways to lower fixed costs, such as renegotiating bills, seeking more affordable housing when possible, or reducing transportation expenses.
Q: Should debt repayment be in needs or savings?
A: Required minimum payments on debts belong in the needs category because you must pay them each month. Any amount you pay above the minimum is counted in the 20% savings and debt bucket, since it accelerates debt payoff and improves your future finances.
Q: How much should I keep in an emergency fund?
A: Many financial educators and institutions suggest building an emergency fund covering three to six months of essential expenses, so you have a cushion against job loss, medical issues, or other unexpected events.
Q: Can I use the 50/30/20 rule if my income is irregular?
A: Yes. If your income varies, use a conservative monthly average based on several months of earnings, and aim to live below that number. In stronger months, try to save more than 20% to cover leaner periods.
Q: Do retirement contributions count in the 20% savings category?
A: Yes. Contributions to retirement accounts such as a 401(k) or IRA generally count as part of the 20% you allocate to savings, since they are funds set aside for your future financial security.
References
- What is the 50/30/20 budget rule? — Citizens Bank. 2023-05-01. https://www.citizensbank.com/learning/50-30-20-budget.aspx
- Budgeting basics: The 50-30-20 rule — United Nations Federal Credit Union (UNFCU). 2023-02-10. https://www.unfcu.org/financial-wellness/50-30-20-rule/
- The 50-30-20 Budget Rule Explained — Henrico County Government, Human Resources. 2022-09-15. https://employees.henrico.gov/county-connection/the-50-30-20-budget-rule-explained/
- The 50-30-20 budget rule explained — Empower. 2023-03-08. https://www.empower.com/the-currency/life/50-30-20-budget-rule-explained-news
- Retirement Topics – 401(k) and Profit-Sharing Plan Contribution Limits — Internal Revenue Service (IRS). 2024-01-01. https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-401k-and-profit-sharing-plan-contribution-limits
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


