

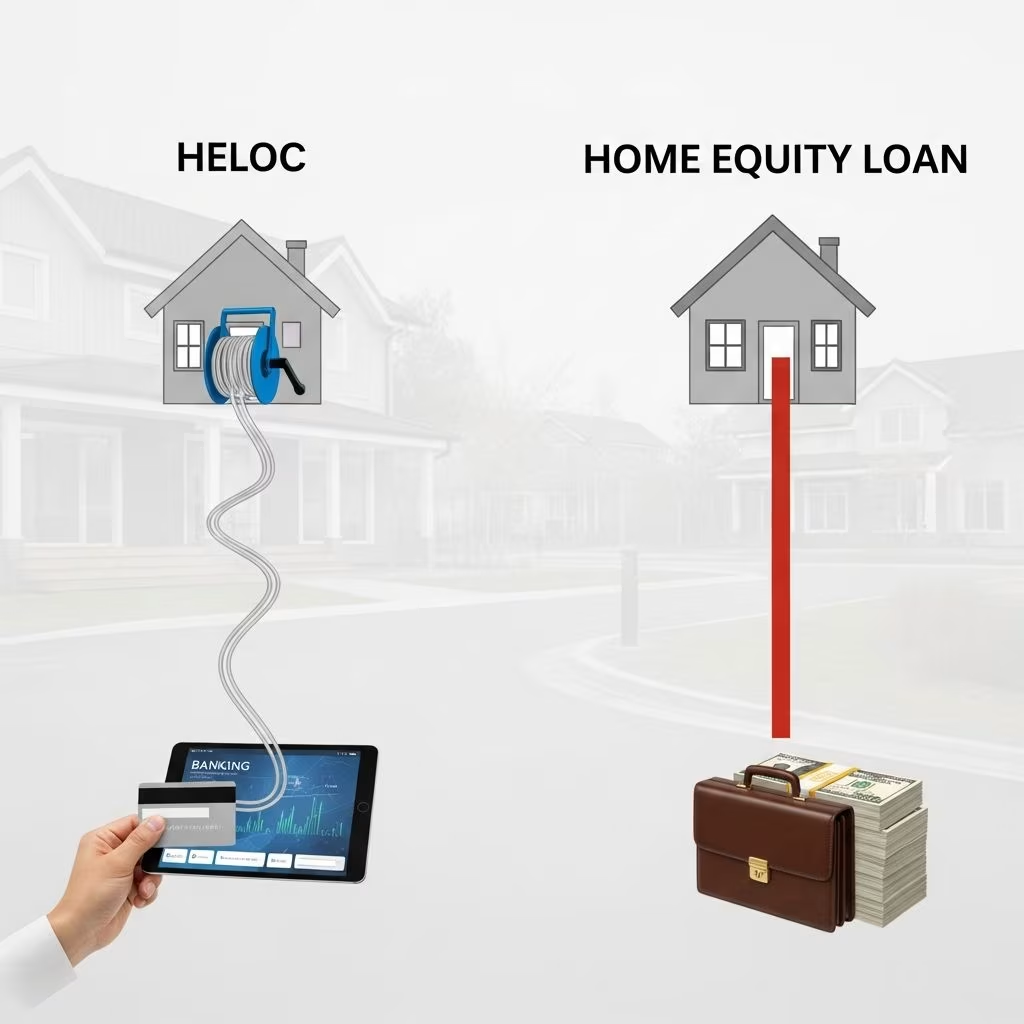
Home equity loans and home equity lines of credit (HELOCs) enable homeowners to access cash by leveraging the equity built up in their property. Both options use your home as collateral, typically offering lower interest rates than unsecured loans like credit cards or personal loans. A **home equity loan** provides a one-time lump sum with fixed payments, ideal for known expenses, while a **HELOC** functions like a revolving credit card, allowing flexible draws during a draw period with variable rates suited for ongoing needs.
What Is a Home Equity Loan?
A home equity loan, often called a second mortgage, lets you borrow a fixed amount based on your home’s equity—the difference between its current market value and your outstanding mortgage balance. Lenders typically allow borrowing up to 80-90% of your equity. You receive the full amount upfront and repay it in equal monthly installments over a set term, usually 5 to 30 years, with a fixed interest rate.
This structure ensures predictable payments, making budgeting straightforward. Interest accrues on the entire loan from day one, regardless of usage. Closing costs, including appraisals and fees, range from 2-5% of the loan amount. These loans suit one-time large expenses like home renovations or debt consolidation.
What Is a HELOC?
A **HELOC** (Home Equity Line of Credit) is a revolving credit line secured by your home equity, similar to a credit card but with lower rates. It features two phases: a draw period (usually 5-10 years) where you can borrow up to your approved limit (often 85% of equity), paying interest only on drawn amounts, followed by a repayment period (10-20 years) requiring principal and interest.
Rates are variable, tied to an index like the prime rate plus a margin, which can fluctuate monthly. Some lenders offer introductory fixed-rate periods or options to lock portions at fixed rates. This flexibility benefits projects with uncertain costs or variable needs, but payments can rise with rates.
Key Differences: HELOC vs. Home Equity Loan
The primary distinctions lie in structure, rates, repayment, and flexibility. Home equity loans offer stability; HELOCs provide adaptability.
| Feature | Home Equity Loan | HELOC |
|---|---|---|
| Loan Structure | Lump sum disbursement | Revolving line of credit |
| Interest Rate | Fixed | Variable (some fixed options) |
| Repayment | Principal + interest from start, fixed payments | Interest-only during draw; full repayment later |
| Interest Charged On | Full amount borrowed | Amount drawn only |
| Flexibility | One-time access | Borrow/repay repeatedly during draw period |
| Best For | Known, fixed costs (e.g., renovations) | Ongoing/uncertain expenses (e.g., education) |
Pros and Cons of Home Equity Loans
Pros
- Fixed rates and payments protect against rate hikes, aiding budgeting.
- Lower rates than credit cards (average 8-10% vs. 20%+).
- Potential tax deductibility for home improvements (consult IRS rules).
- Simple structure for single large needs.
Cons
- No flexibility—can’t access more funds without refinancing.
- Interest on full amount immediately.
- Closing costs (2-5%) add upfront expense.
- Risk of foreclosure if defaulting, as home is collateral.
Pros and Cons of HELOCs
Pros
- Pay interest only on used funds, saving money if not fully drawn.
- Revolving access during draw period for flexibility.
- Potentially lower initial rates; some fixed-rate locks available.
- Suits variable expenses like medical bills or phased projects.
Cons
- Variable rates can increase payments significantly (e.g., post-2022 hikes).
- Temptation to overspend like a credit card.
- Balloon payments possible at draw end if not managed.
- Annual fees or inactivity charges on some accounts.
Interest Rates and Fees
Home equity loans average 8.5-9.5% fixed (as of late 2025), per ICE Mortgage Technology data. HELOCs start lower at 8-9% variable but can exceed 10% with rises. Fees include origination (0-1%), appraisals ($300-500), and title searches. HELOCs often waive closing costs but may charge annual fees ($50-75). Shop multiple lenders; credit unions like UW Credit Union offer competitive terms.
Qualifications and Eligibility
Both require 15-20% equity post-borrowing, credit scores of 620-680+, debt-to-income (DTI) under 43-50%, and stable income. Self-employed may need extra docs. Lenders appraise your home; LTV caps prevent over-borrowing. Excellent credit (740+) unlocks best rates.
- Minimum equity: $20,000-50,000 typically.
- Loan amounts: $10,000-$500,000+ based on equity.
When to Choose a Home Equity Loan
Opt for this if you need a specific sum now, like $50,000 for a kitchen remodel with fixed costs. Fixed payments suit tight budgets, especially in rising rate environments.
When to Choose a HELOC
Ideal for ongoing needs, like college tuition over years or home repairs with phased costs. Borrow as needed, repay to replenish line—great for emergencies if you have discipline.
Risks of Both Options
Your home is collateral; default risks foreclosure. Variable HELOC rates amplify payments in high-rate periods. Overborrowing erodes equity, complicating future sales/refinancing. Always calculate affordability; use no more than 80% equity.
Alternatives to Consider
- Personal loans: Unsecured, fixed, for smaller amounts ($1k-50k), higher rates (10-20%).
- Cash-out refinance: Replaces primary mortgage, lower rates but resets term.
- 0% balance transfer cards: Short-term for debt consolidation.
Frequently Asked Questions (FAQs)
What’s the main difference between a HELOC and home equity loan?
A home equity loan gives a lump sum with fixed payments; a HELOC offers revolving access with variable rates and interest-only draws.
Are HELOC rates fixed or variable?
Typically variable, tied to prime rate, but some allow fixed-rate portions.
Can I deduct interest on these loans?
Possibly, if used for home improvements—check IRS Publication 936 and consult a tax pro.
How much can I borrow?
Up to 80-90% of equity, e.g., $200k home with $100k mortgage = up to $80-90k available.
What happens after the HELOC draw period?
Enters repayment: no more draws, principal + interest due, possibly higher payments.
Final Thoughts
Assess your needs: stability (home equity loan) or flexibility (HELOC). Compare rates from 3+ lenders, review total costs, and ensure payments fit your budget to avoid risks. Building equity wisely supports long-term financial health.
References
- HELOC Vs. Home Equity Loan: What’s The Difference? — Bankrate. 2025-08. https://www.bankrate.com/home-equity/home-equity-loan-vs-line-of-credit/
- HELOC vs Home Equity Loan vs Personal Loan — UW Credit Union. 2025. https://www.uwcu.org/mortgage-home-loans/articles/borrowing-options
- Home Equity Loan Vs. HELOC — PSBT. 2025. https://www.psbt.com/Learn/Resources/PSBT-Corner-News/Home-Equity-Loan-Vs-HELOC
- Home Equity Loan vs. Line of Credit — Bank of America. 2025. https://www.bankofamerica.com/mortgage/learn/home-equity-loan-vs-line-of-credit/
- What is the difference between a Home Equity Loan and a Home Equity Line of Credit (HELOC)? — Consumer Financial Protection Bureau. 2025. https://www.consumerfinance.gov/ask-cfpb/what-is-the-difference-between-a-home-equity-loan-and-a-home-equity-line-of-credit-heloc-en-247/
- Home Equity Loan vs. HELOC: 5 Factors to Consider — Gate City Bank. 2025. https://www.gatecity.bank/education/articles/home-equity-loan-vs-HELOC/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


