

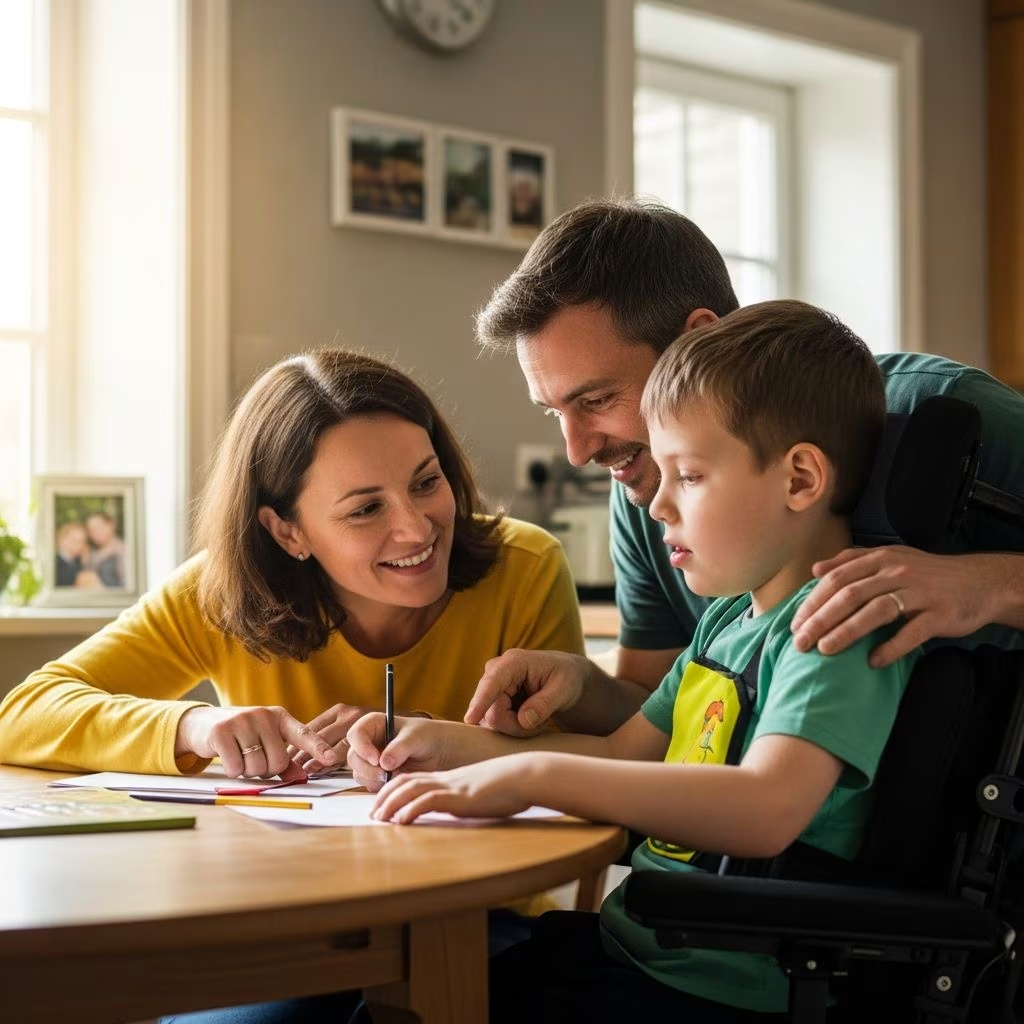
Raising a child with cerebral palsy (CP) brings unique joys alongside significant financial challenges. Medical bills, therapies, adaptive equipment, and daily care can quickly add up, often straining family budgets. This article shares the real-life experiences of the Russell family, who have navigated these costs for over a decade with their son diagnosed with CP. By combining government assistance, insurance optimization, and creative saving strategies, they’ve kept expenses manageable without sacrificing quality care.

Tina Russell and family managing daily life with cerebral palsy. Photo by Tina Russell/The Penny Hoarder.
What Is Cerebral Palsy and Its Financial Impact?
Cerebral palsy is a group of permanent movement disorders caused by abnormal brain development or damage to the developing brain, affecting muscle tone, movement, and motor skills. It is the most common motor disability in childhood, impacting about 1 in 345 children in the U.S. Families often face lifelong costs estimated at $1 million or more per child over a lifetime, covering therapies, surgeries, wheelchairs, and home modifications.
The Russell family learned this firsthand when their son was diagnosed at age 2. ‘We went from typical toddler worries to budgeting for weekly therapies and custom braces,’ says mom Tina Russell. Initial shock gave way to proactive planning, focusing on high-cost areas like physical therapy ($100-$200/session), occupational therapy, speech therapy, and equipment such as standers ($3,000+) and power wheelchairs ($20,000+).
Securing Health Insurance and Supplemental Coverage
Health insurance is the cornerstone of managing CP costs. The Russells prioritized comprehensive coverage through Tina’s employer plan, which covers 80% of therapies after deductibles. They supplemented with Medicaid waivers, which provide additional services not covered by private insurance.
- Employer-sponsored plans: Choose high-deductible plans with HSAs for tax-free savings on therapies.
- Medicaid/CHIP: Free or low-cost coverage for children with disabilities; apply via state health departments.
- ABEN waivers: In many states, these fund respite care, adaptive equipment, and in-home nursing.
Pro tip: Appeal denials aggressively. The Russells successfully fought for coverage of a $15,000 gait trainer by submitting doctor letters and medical necessity forms.
Government Benefits and Assistance Programs
Federal and state programs are lifelines for special needs families. Supplemental Security Income (SSI) provides monthly cash benefits (up to $943 in 2024 for individuals) based on disability and income. The Russells qualified early, using funds for non-medical expenses like transportation.
| Program | Benefits | Eligibility | Avg. Annual Value |
|---|---|---|---|
| SSI | Cash for daily needs | Low-income disabled child | $11,000 |
| Medicaid | Medical coverage | SSI auto-qualifies | $10,000+ |
| Section 8 Housing | Subsidized rent | Low-income families | $5,000 |
| 529 ABLE Account | Tax-free savings | Disability before age 26 | Up to $18,000/year |
ABLE accounts are game-changers, allowing savings without affecting SSI eligibility. The Russells saved $10,000 for future equipment upgrades.
Managing Therapy Costs Effectively
Therapies are weekly necessities but pricey. Physical, occupational, and speech sessions total $20,000+ annually out-of-pocket without aid. The Russells cut costs by:
- Using in-home therapy via Early Intervention (free for under 3s).
- Nonprofits like Children’s Specialized Hospital offering sliding-scale fees.
- Home exercise programs with PT-designed routines to reduce sessions.
- Teletherapy post-pandemic, saving $50/session in travel.
‘Consistency matters more than intensity,’ Tina notes. They blend professional sessions with family-led exercises using free YouTube channels from certified therapists.
Affordable Adaptive Equipment and Home Modifications
- Wheelchairs and mobility aids: Medicaid covers basics; upgrade via nonprofits like United Cerebral Palsy (UCP).
- Standers/bath chairs: Buy used on Facebook Marketplace ($500 vs. $3,000 new); inspect for safety.
- Home ramps/lifts: Grants from Easterseals or local housing authorities fund 50-100%.
The Russells scored a gently used power chair for $4,000 (retail $25,000) through a local CP parent group.
Special Needs Trusts and Long-Term Financial Planning
Planning for adulthood is crucial. Without it, benefits like SSI can be lost upon inheritance. Special Needs Trusts (SNTs) preserve eligibility while holding assets for extras like vacations.
- First-party SNT: Funded by child’s assets (e.g., settlements).
- Third-party SNT: Parents fund for child without Medicaid payback.
- Life insurance: Buy low-cost policies inside trusts for future security.
Consult a special needs attorney early; fees ($2,000-$5,000) pay off long-term. The Russells set up a pooled trust via a nonprofit for low upfront costs.
Respite Care and Family Support Resources
Caregiver burnout is real. Respite programs offer paid breaks (8-40 hours/month via waivers). Parent support groups via UCP provide emotional and practical tips.
- Join online forums like Cerebral Palsy Guide for gear swaps.
- Apply for family grants from Variety Club or Help Hope Live.
Tax Breaks and Deductions for Special Needs Families
IRS rules allow hefty deductions:
- Medical expense deduction: Over 7.5% AGI (therapies, equipment).
- Dependent care credit: Up to $3,000 for respite.
- ABLE contributions: State tax deductions.
The Russells claim $8,000 annually, reducing taxable income significantly.
Daily Budgeting Tips from the Russells
- Track everything: Use apps like Mint categorized for ‘CP expenses.’
- Meal prep adaptive foods: Blender recipes save on special diets.
- Second-hand clothing: Once Upon a Child for durable, sensory-friendly items.
- Community fundraisers: Lemonade stands or GoFundMe for big-ticket items.
Frequently Asked Questions (FAQs)
What are the average lifetime costs for a child with cerebral palsy?
Estimates range from $900,000 to $1.5 million, primarily for medical care and lost productivity, per CDC data.
Does SSI cover all therapy costs?
No, SSI is cash; pair with Medicaid for therapies. Waivers fill gaps.
Can I buy used adaptive equipment safely?
Yes, but get PT inspection. Platforms like eBay or parent groups are reliable.
How do I start a Special Needs Trust?
Contact a certified special needs planner via Academy of Special Needs Planning.
Are there free resources for CP parents?
Yes: Pathfinders for autism/CP, Scope.org.uk for guides, and state family support networks.
Key Takeaways
- Maximize insurance + government aid first.
- Network with other parents for deals.
- Plan long-term with trusts and ABLE.
- Appeal everything; persistence pays.
The Russells’ journey proves that with strategy, families can thrive despite CP costs. ‘It’s not easy, but knowledge is power,’ Tina says. Start with your state’s disability resources today.
References
- Cerebral Palsy Facts and Figures — Centers for Disease Control and Prevention (CDC). 2024-09-01. https://www.cdc.gov/ncbddd/cp/facts.html
- Supplemental Security Income (SSI) for Children — Social Security Administration (SSA). 2025-01-10. https://www.ssa.gov/ssi/text-child-ussi.htm
- Lifetime Costs of Cerebral Palsy — United Cerebral Palsy Research. 2023-06-15. https://ucp.org/resource/lifetime-costs/
- Medicaid Home and Community-Based Services Waivers — Centers for Medicare & Medicaid Services (CMS). 2024-11-20. https://www.medicaid.gov/medicaid/long-term-services-supports/home-community-based-services/
- Special Needs Trusts and ABLE Accounts — IRS Publication 907. 2024-12-01. https://www.irs.gov/publications/p907
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


