

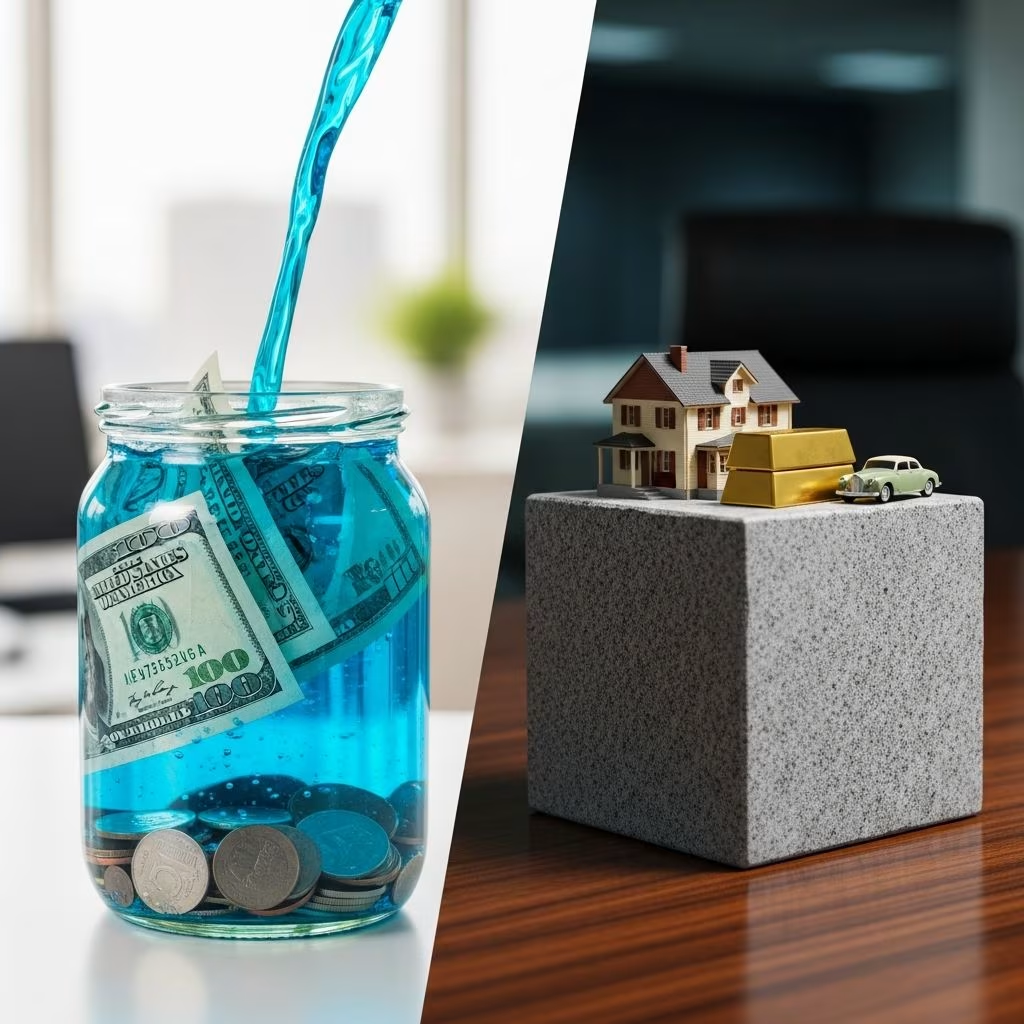
Liquid assets can be quickly converted into cash with little to no loss in value, providing immediate financial flexibility, while non-liquid assets require more time and effort to sell, often suiting long-term wealth building.
What Are Liquid Assets?
Liquid assets are financial resources that can be rapidly transformed into cash without significantly affecting their market value. This characteristic makes them essential for covering short-term needs, emergencies, or opportunistic investments. The speed of conversion—typically within days—distinguishes them from other holdings, ensuring accessibility when liquidity is critical.
In personal finance, maintaining a healthy portion of liquid assets helps individuals and businesses respond to unexpected expenses or market shifts without forced sales of valuable long-term holdings. For instance, during economic downturns, liquid assets prevent the need to liquidate illiquid investments at depressed prices.
Examples of Liquid Assets
- Cash: The ultimate liquid asset, including physical currency, demand deposits, and funds in checking or savings accounts, available instantly for use.
- Marketable Securities: Stocks and bonds traded on public exchanges, which can be sold quickly through brokerage platforms with established market prices.
- Money Market Funds and Short-Term CDs: Low-risk investments offering high liquidity, often redeemable within a day or two with minimal penalties.
- Treasury Bills: Government-issued short-term securities maturing in less than a year, easily traded in active secondary markets.
These examples highlight how liquid assets support day-to-day operations and provide a safety net, as noted in financial management guides emphasizing quick convertibility.
What Are Non-Liquid Assets?
Non-liquid, or illiquid, assets cannot be easily or quickly converted to cash without substantial value loss, extended selling periods, or high transaction costs. They are typically held for appreciation, income generation, or strategic purposes over extended horizons, making them foundational for wealth accumulation but risky for immediate needs.
Investors value non-liquid assets for their potential high returns, yet they demand patience due to market dependencies, legal processes, or niche buyer pools. In portfolios, they counterbalance liquid holdings by driving growth, though over-reliance can strain cash flow during crises.
Examples of Non-Liquid Assets
- Real Estate: Properties like homes, land, or commercial buildings, which may take months to sell amid appraisals, inspections, and financing hurdles.
- Vehicles and Personal Property: Cars, boats, or jewelry, facing depreciation and limited buyer interest, often requiring auctions or dealerships.
- Collectibles and Art: Items like antiques, wine, or paintings, with subjective valuations and specialized markets prolonging sales.
- Business Interests and Equipment: Ownership stakes in private companies, machinery, or inventory, involving negotiations, valuations, and potential depreciation.
- Intellectual Property: Patents, trademarks, or copyrights, challenging to monetize quickly due to legal transfers and niche demand.
These assets exemplify the trade-off: higher growth potential versus reduced accessibility, crucial for diversified strategies.
Liquid vs. Non-Liquid Assets: Key Differences
The core distinctions between liquid and non-liquid assets revolve around convertibility, value stability, market dynamics, and strategic roles, profoundly impacting financial planning.
| Aspect | Liquid Assets | Non-Liquid Assets |
|---|---|---|
| Conversion Speed | Quick, often within days, ideal for emergencies. | Slow, potentially weeks to years, with complex processes. |
| Value Impact | Minimal loss; stable pricing in active markets. | Potential significant discounts or losses if rushed. |
| Market Availability | Broad, liquid markets like stock exchanges. | Limited, niche buyers requiring targeted efforts. |
| Risk and Return | Lower risk, modest returns for stability. | Higher risk, superior long-term returns possible. |
| Usage | Short-term needs, flexibility. | Long-term growth, income, diversification. |
This comparison underscores why balancing both asset types is vital: liquid assets ensure resilience, while non-liquid ones fuel prosperity.
Why Balance Liquid and Non-Liquid Assets?
Achieving an optimal mix of liquid and non-liquid assets aligns short-term security with long-term objectives, mitigating risks like market volatility or liquidity crunches. Financial advisors recommend 3-6 months of expenses in liquid forms as an emergency fund, with the rest allocated to growth-oriented illiquid investments.
During downturns, excess liquidity avoids distress sales of non-liquid assets at lows, preserving capital for recovery. Conversely, too much liquidity may erode purchasing power via inflation, underscoring non-liquid assets’ role in hedging and appreciation. Personalized ratios depend on age, risk tolerance, and goals—younger investors might favor illiquids for growth, while retirees prioritize liquidity.
Benefits of Liquid Assets
- Immediate access for opportunities or crises.
- Low transaction costs and value preservation.
- Reduced stress in volatile markets.
Benefits of Non-Liquid Assets
- Potential for substantial appreciation and yields.
- Portfolio diversification beyond liquid markets.
- Steady income from rentals or dividends.
This equilibrium supports goals like homebuying, education funding, or retirement, enhancing overall financial health.
Financial Strategies for Managing Liquidity
Effective liquidity management involves regular portfolio reviews, stress testing for scenarios like job loss, and tools like liquidity ratios (e.g., current ratio: liquid assets divided by short-term liabilities). Diversify liquid holdings across accounts to maximize yields without sacrificing access, and ladder non-liquid maturities for periodic cash inflows.
For businesses, centralized platforms streamline tracking, while individuals benefit from robo-advisors auto-balancing allocations. Tax considerations also play in: liquid assets like munis offer tax advantages, while illiquids like real estate provide depreciation deductions. Periodically rebalance to maintain targets, selling winners and buying dips judiciously.
Frequently Asked Questions (FAQs)
What is a liquid asset?
A liquid asset is one that can be converted to cash quickly with minimal value loss, such as cash or stocks.
What are examples of liquid assets?
Examples include cash, checking/savings accounts, stocks, bonds, and money market funds.
What are non-liquid assets?
Non-liquid assets, like real estate or collectibles, take significant time and effort to sell without major value impact.
Why is liquidity important in personal finance?
Liquidity ensures you can handle emergencies or opportunities without disrupting long-term investments.
How much of my portfolio should be liquid?
Typically 10-20% or enough for 3-6 months’ expenses, adjusted for personal risk and goals.
Can non-liquid assets generate income?
Yes, through rentals, dividends, or sales over time, often outperforming liquids long-term.
References
- Financial Management Regulation — U.S. Department of Defense. 2023-10-01. https://comptroller.defense.gov/Portals/45/documents/fmr/Volume_12/Chapter_01.pdf
- Principles of Corporate Finance — McGraw-Hill Education (Brealey, Myers, Allen). 2020-01-06. https://www.mheducation.com/highered/product/principles-corporate-finance-brealey-myers/M9781260013900.html
- Liquidity Risk Management — Federal Reserve Board. 2024-05-15. https://www.federalreserve.gov/supervisionreg/srletters/sr2405.htm
- Investor Bulletin: Liquidity and Illiquid Investments — U.S. Securities and Exchange Commission. 2022-08-10. https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/liquidity
- Asset Liquidity and Portfolio Management — CFA Institute. 2023-11-20. https://www.cfainstitute.org/en/membership/professional-development/refresher-readings/asset-liquidity
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


