

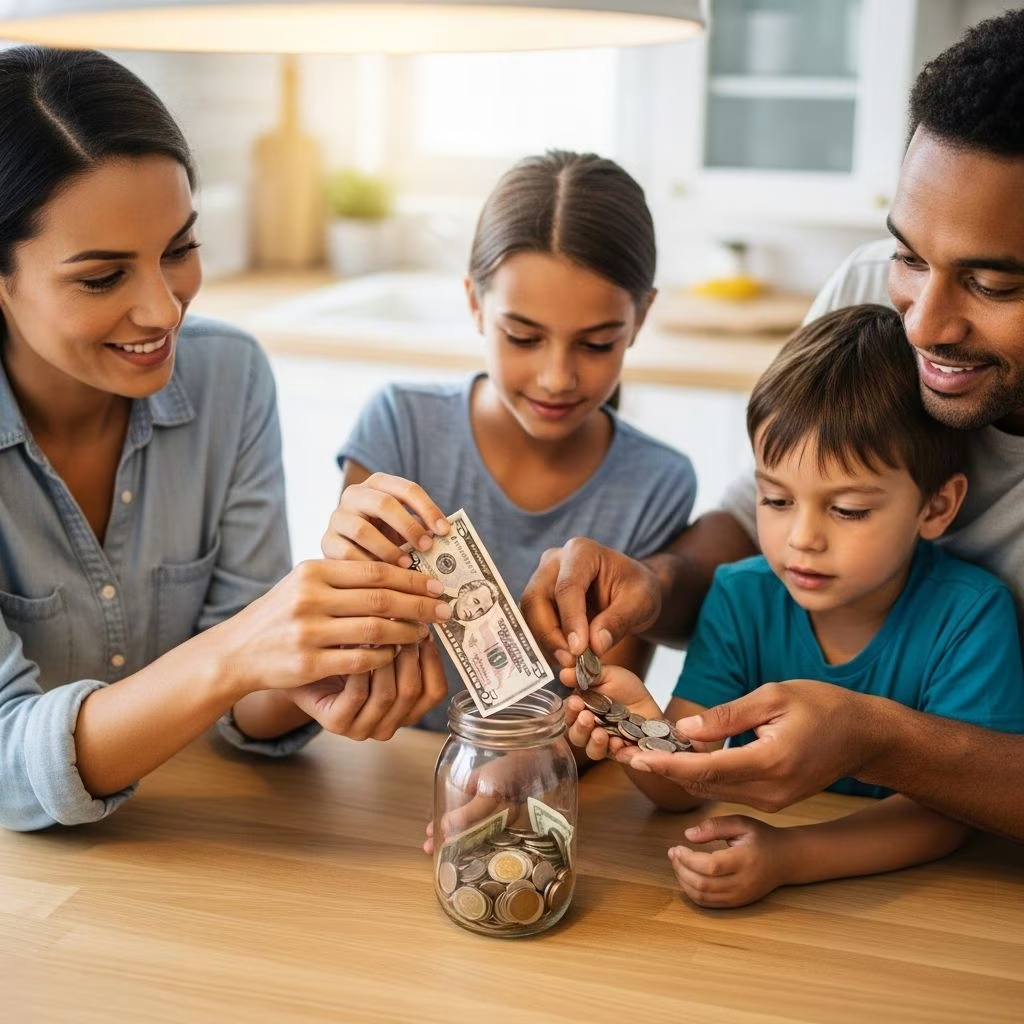
In today’s economy, families are increasingly collaborative when it comes to finances. But should children—whether young kids or teenagers—pitch in toward shared family savings goals like a vacation, home repairs, or emergency funds? This question sparks debate among parents, educators, and financial experts. On one hand, involving kids teaches invaluable money lessons; on the other, it risks burdening them unfairly or stifling childhood joys. This article dives deep into the arguments, strategies, and real-world examples to help you decide what’s right for your family.
The Case For: Why Kids Should Contribute
Having children contribute to family goals fosters financial literacy from an early age, turning abstract concepts into tangible experiences. When kids see their small sacrifices adding up to a family win, they learn the power of delayed gratification and teamwork.
- Builds Ownership and Responsibility: Contributing a portion of allowance or chore earnings makes kids feel like active participants, not just dependents. For instance, matching family contributions to a ‘fun fund’ mirrors real-world 401(k) matches, teaching leverage.
- Teaches Budgeting Basics: Kids quickly grasp opportunity costs—skipping candy today means ice cream tomorrow. This hands-on approach outperforms lectures, as evidenced by financial education programs emphasizing experiential learning.
- Prepares for Adulthood: With nearly 40% of empty-nesters still subsidizing adult children, early independence training prevents prolonged dependency.
Experts like those at credit unions advocate starting small: for young children, $1-2 toward a $10-15 goal like a movie night creates excitement without overwhelm.
The Case Against: Potential Downsides
Not everyone agrees. Critics argue that pressuring kids to contribute shifts adult responsibilities onto minors, potentially breeding resentment or inequality.
- Resentment and Childhood Loss: Forcing savings from limited allowances might make kids view family goals as punitive, eroding family bonds.
- Unequal Burdens: Larger families or low-income households could exacerbate stress if contributions feel mandatory.
- Missed Learning Opportunities: Over-focusing on family goals might neglect personal savings, like kids’ own toy funds, hindering individual goal-setting.
Balance is key: surveys show parental support persisting into adulthood often stems from poor early financial habits, but abrupt cutoffs without preparation can backfire.
Age-Appropriate Strategies for Success
Tailor involvement by age to maximize benefits. Here’s a breakdown:
| Age Group | Goal Examples | Contribution Methods | Expected Outcomes |
|---|---|---|---|
| 3-6 Years (Preschool) | Ice cream outing ($10-15) | 1-2% of allowance or chore coins; visual jar trackers | Excitement for small wins; basic counting |
| 7-12 Years (Elementary) | Family movie night or park day ($50) | 5-10% allowance; family matching | Budget awareness; delayed gratification |
| 13-17 Years (Teens) | Vacation fund or gadget upgrade ($500+) | Job earnings portion; apps for tracking | Real budgeting; independence prep |
For preschoolers, use transparent jars to visualize progress—watching coins stack up is magical. Tweens benefit from chore charts tying earnings to goals, while teens can use apps linking part-time wages to family pots.
Real-World Examples and Family Stories
Consider the Rodriguez family: With three kids under 12, they set a $200 backyard picnic goal. Each child contributed $5 from chores, matched by parents. The event wasn’t just fun—it sparked ongoing savings talks.
In contrast, the empty-nester survey highlights risks: parents footing 40% of adult kids’ bills regret not enforcing earlier contributions, urging a shift to mapped independence plans.
Tools and Games to Make It Fun
Turn saving into playtime. Family game nights with money-themed board games teach strategy without pressure.
- Monopoly or Cashflow: Simulate real economies, negotiating ‘family deals.’
- DIY Savings Jars: Label for family goals; decorate together.
- Apps like Greenlight: Prepaid cards with parental controls for goal-setting (note: research family-friendly options).
Credit union tips emphasize timelines: set goals, map paychecks needed, hit benchmarks.
Expert Tips from Financial Pros
Millennial expert Priya Malani warns against harmful dependency jeopardizing parental retirement. Steps include:
- Communicate Transparently: Explain goals and ‘why’ behind contributions.
- Match Contributions: Double kids’ input to show partnership.
- Celebrate Milestones: Non-monetary rewards reinforce positivity.
- Review Regularly: Adjust as family needs evolve.
Sallie Mae’s resources stress free tools for goal projection, applicable to family college funds.
Frequently Asked Questions (FAQs)
What if my child refuses to contribute?
Start voluntary and lead by example. Refusal often stems from unclear benefits—tie to privileges like extra playtime upon goal hits.
Does this replace personal savings?
No—insist on 50/50 split: half to family, half personal. Builds balanced habits.
How much is age-appropriate?
1-10% of allowance/earnings, scaled by age. Under $5 for young kids prevents burden.
Can this help with teen jobs?
Absolutely—designate 20% of wages to family goals, teaching real-world allocation.
What about single-income families?
Focus on non-cash contributions like chores equaling ‘dollars’ value, maintaining equity.
Conclusion: A Path to Financially Savvy Families
Involving kids in family money goals isn’t one-size-fits-all but offers profound benefits when done thoughtfully. It equips the next generation against statistics like prolonged parental support, while strengthening bonds through shared success. Start small, stay consistent, and watch your family thrive financially.
References
- 4 Financial Moves for Empty Nesters — John Hancock. 2023 (accessed 2026). https://www.johnhancock.com/ideas-insights/4-financial-moves-for-empty-nesters.html
- 6 Ways to Save as a Family — Scenic Community Credit Union. 2024 (accessed 2026). https://www.mysccu.com/learn/6-ways-to-save-as-a-family
- Powering Confidence – Sallie Mae CSR Report — Sallie Mae. 2023. https://www.salliemae.com/content/dam/slm/writtencontent/Reports/investors/SallieMae_CSR.pdf
- Family Game Night: Teach Kids About Money — CNBC Ohio. 2024 (accessed 2026). https://www.cnbohio.com/family-game-night-can-be-a-fun-way-to-teach-kids-about-money/
- 7 Ways to Turn Saving into a Habit — 1st Ed Credit Union. 2025 (accessed 2026). https://www.1edcu.org/7-ways-to-turn-saving-money-into-a-habit/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


