

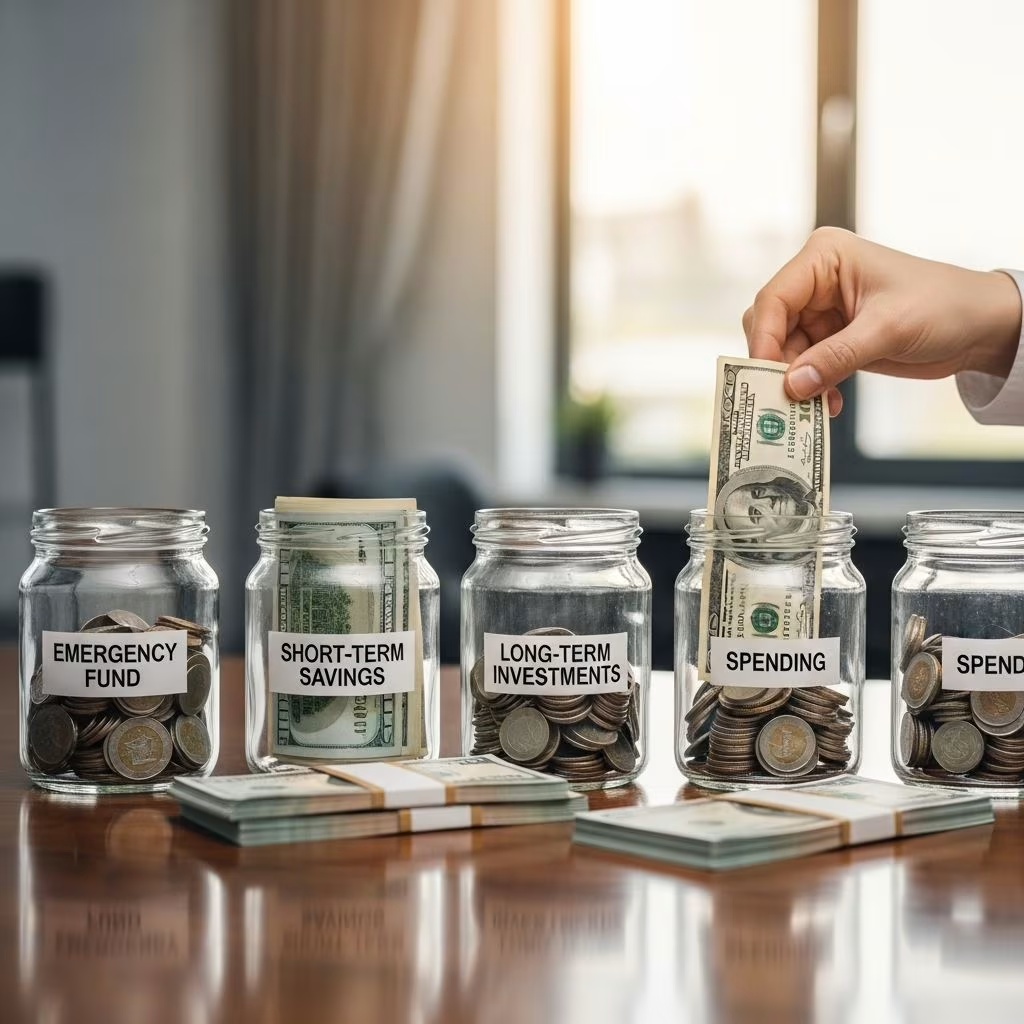
Strategic cash bucketing divides your savings into distinct categories based on when you’ll need the money, creating a roadmap for financial stability throughout retirement or long-term goals. This method minimizes market volatility risks by matching investments to time horizons, ensuring liquidity for immediate needs while allowing growth for future years.
Why Cash Bucketing Beats Traditional Investing
Unlike a single diversified portfolio, cash bucketing tailors asset allocation to specific timelines, preventing forced sales during downturns. It provides psychological comfort, knowing short-term funds are protected, while long-term portions pursue higher returns.
Research shows this approach helps retirees sustain withdrawals even in volatile markets. By isolating safe assets for near-term use, you avoid dipping into growth investments at inopportune times, preserving principal for later.
Building Your Three-Bucket Framework
The core of cash bucketing involves three layers: immediate access, balanced replenishment, and aggressive expansion. Each serves a unique role in your financial ecosystem.
Bucket 1: Immediate Liquidity Reserve
This foundation covers 1-3 years of essential expenses, including living costs beyond guaranteed income like Social Security or pensions. Prioritize ultra-safe, liquid options to weather any economic storm without stress.
- Cash in high-yield savings accounts for instant access.
- Certificates of Deposit (CDs) laddered for short maturities.
- Short-term U.S. Treasury bills or money market funds yielding stability.
Calculate needs by totaling annual expenses, inflating for future years, and adding an emergency buffer—typically 3-6 months extra. Conservative estimates suggest holding twice your yearly spend for cautious investors.
Bucket 2: Income and Stability Bridge
Designed for 4-10 years out, this bucket generates moderate income to refill Bucket 1 annually. It balances yield with low volatility, using assets that produce dividends or interest.
| Asset Type | Expected Role | Risk Level |
|---|---|---|
| Investment-grade bonds | Steady interest payments | Low |
| Dividend blue-chip stocks | Quarterly payouts with growth | Moderate |
| Preferred stocks or REITs | High yields, some appreciation | Moderate |
| Intermediate-term bond funds | Diversified fixed income | Low-Moderate |
As Bucket 1 depletes, transfer from here, accounting for 2-3% inflation and modest returns around 4-6%.
Bucket 3: Long-Term Growth Engine
For needs beyond 10 years, this bucket embraces equities and alternatives for compounding. Its distant horizon tolerates fluctuations, fueling the entire system over decades.
- Broad stock index funds or ETFs for market exposure.
- Growth-oriented mutual funds targeting 7-10% average annual returns.
- Diversified real estate or international equities for added potential.
Historical data supports equities’ superiority for longevity, with S&P 500 averaging over 10% since inception, adjusted for inflation.
Step-by-Step Implementation Guide
Launching your buckets requires precise planning. Start with a full financial audit.
- Assess Total Expenses: List fixed (housing, utilities) and variable (travel, hobbies) costs. Project 30+ years, inflating at 2-3% annually.
- Quantify Buckets: Bucket 1: 2-3 years’ expenses (~$150K for $50K/year). Bucket 2: 5-7 years (~$350K). Remainder to Bucket 3.
- Allocate Assets: Shift holdings accordingly, selling high-performers tax-efficiently via tax-advantaged accounts first.
- Set Replenishment Rules: Annually review; move $50K from Bucket 2 to 1, $50K from 3 to 2 if growth allows.
- Monitor and Adjust: Rebalance yearly or after major life events like health changes.
Real-World Example: A Retiree’s Bucket Plan
Consider Sarah, 65, with $1M portfolio and $60K annual expenses (post-Social Security). She allocates:
- Bucket 1: $180K (3 years) in CDs and Treasuries at ~4% yield.
- Bucket 2: $360K (6 years) in bonds and dividend stocks yielding 5%.
- Bucket 3: $460K in stock funds targeting 8% growth.
Year 1: Spends $60K from Bucket 1. Transfers $65K (inflation-adjusted) from Bucket 2. Bucket 3 grows to $497K. This cycle sustains her for 30+ years, even with market dips.
Overcoming Common Obstacles
Bucketing isn’t flawless. Low yields on safe assets can erode purchasing power, but blending ladders mitigates this. Over-reliance on stocks in Bucket 3 risks sequence-of-returns issues, countered by conservative sizing.
Inflation demands vigilant projection—use tools assuming 2.5% long-term. Tax implications favor Roth conversions for growth buckets. Flexibility is key: Upsize Bucket 1 during recessions.
Advanced Tweaks for Optimal Performance
Enhance with dynamic guardrails: Cap withdrawals at 5% of portfolio if markets soar, floor at 3% if crashing. Integrate annuities into Bucket 2 for guaranteed flow.
For couples, align buckets with joint lifespans, emphasizing Bucket 3 for the longer-lived spouse. Tech aids like portfolio trackers automate rebalancing.
Frequently Asked Questions
What if markets crash right after retirement?
Your Bucket 1 buffer lets growth assets recover undisturbed, historically rebounding within 2-5 years.
How often should I rebalance?
Annually or when a bucket deviates 10-20% from target, whichever first.
Is bucketing suitable for non-retirees?
Yes, adapt for goals like home buying: Short bucket for down payment, long for post-purchase growth.
Does inflation break the strategy?
No—plan transfers with inflation baked in, and growth bucket outpaces it long-term.
Can I use fewer buckets?
Two-bucket versions work for smaller portfolios, but three offers finer risk control.
Long-Term Sustainability Metrics
| Scenario | Success Rate (30 Years) | Source Insight |
|---|---|---|
| Standard 4% Rule | ~95% | Historical backtests |
| Three-Bucket Strategy | ~98% | Volatility-adjusted |
| Bear Market Start | 92% vs 85% | Sequence risk reduced |
These figures underscore bucketing’s edge in adverse conditions.
Adopting cash bucketing transforms abstract savings into a tangible security system. It empowers confident spending today while securing tomorrow’s horizons.
References
- Boost Your Retirement Portfolio With the “Three Bucket” Strategy — NCOA. 2023. https://www.ncoa.org/article/boost-your-retirement-portfolio-with-the-three-bucket-strategy/
- A Complete Guide on Retirement Bucket Strategy — Farther. 2024. https://www.farther.com/foundations/a-complete-guide-on-retirement-bucket-strategy
- Manage Market Risk in Retirement with the Bucket Strategy — Thrivent. 2024. https://www.thrivent.com/manage-market-risk-in-retirement-with-the-bucket-strategy
- Phasing Retirement with a Bucket Drawdown Strategy — Charles Schwab. 2023. https://www.schwab.com/learn/story/phasing-retirement-with-bucket-drawdown-strategy
- The Bucket Approach to Building a Retirement Portfolio — Morningstar. 2024. https://www.morningstar.com/portfolios/bucket-approach-building-retirement-portfolio
- The Bucket Approach for Retirement: A Suboptimal Behavioral Trick? — IESE Business School (PDF). 2019-07-01. https://blog.iese.edu/jestrada/files/2019/07/BucketApproach.pdf
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


