

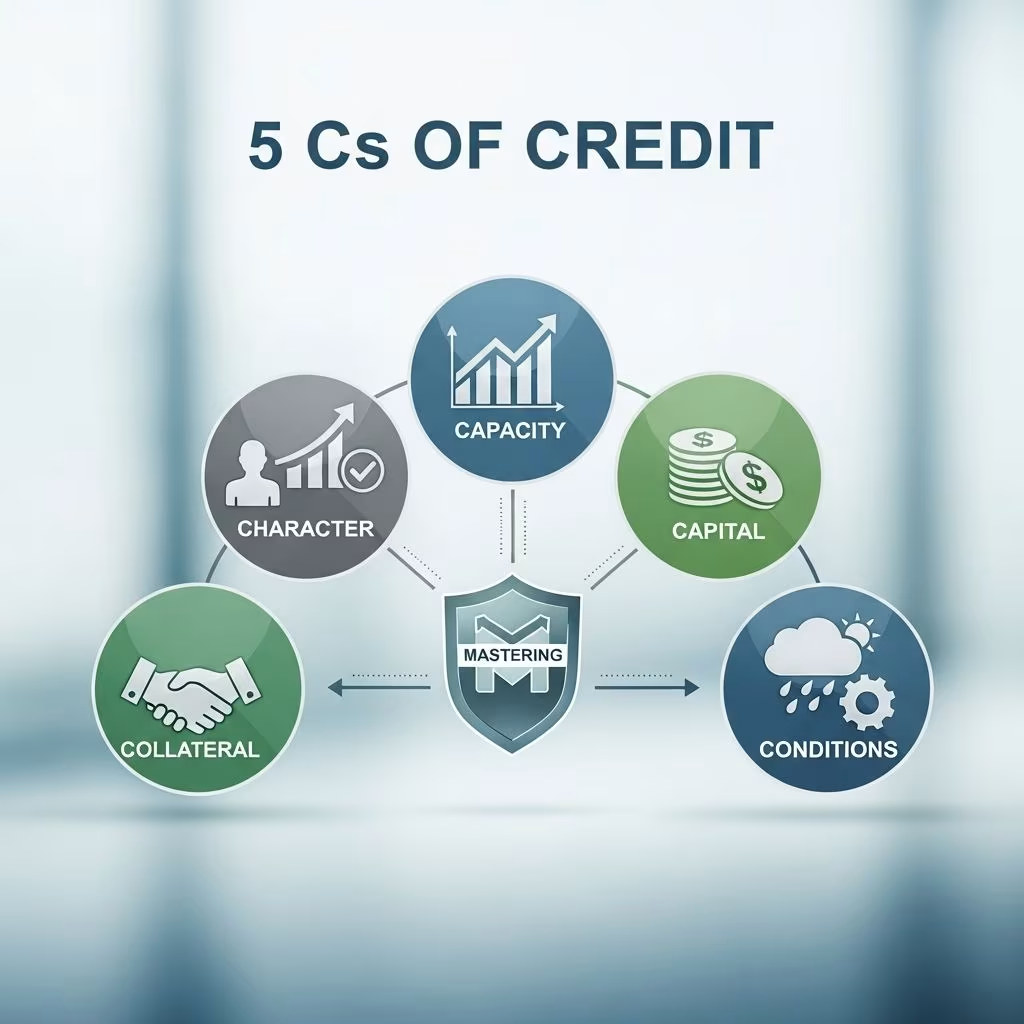
Strong credit opens doors to favorable loan terms, lower interest rates, and financial opportunities. Lenders rely on the **5 Cs of Credit** framework to assess borrowers: Character, Capacity, Capital, Collateral, and Conditions. This time-tested model helps evaluate risk and reliability.
Understanding these factors empowers you to take targeted actions for credit improvement. Whether starting fresh or rebuilding, focusing on each C builds a robust financial profile.
Character: Proving Your Creditworthiness
Character refers to your history of managing debt responsibly. Lenders review your credit report for patterns in payments, defaults, and overall behavior.
Payment history is paramount, comprising 35% of FICO scores. Consistent on-time payments signal trustworthiness. Late payments or delinquencies can linger for seven years, impacting approvals.
- Check your credit report weekly via AnnualCreditReport.com for errors.
- Set up autopay for bills to ensure timeliness.
- If behind, negotiate payment plans with creditors promptly.
Building character starts with secured cards for newcomers. Deposit funds as your limit, use lightly, and pay fully monthly. This establishes positive history quickly.
Capacity: Demonstrating Repayment Ability
Capacity measures income against debt obligations. Lenders calculate debt-to-income (DTI) ratio: monthly debts divided by gross income. Ideal DTI is under 36%.
Stable employment and verifiable income bolster capacity. Gig workers may need extra documentation like tax returns.
| DTI Range | Implication |
|---|---|
| <36% | Strong, qualifies for best rates |
| 37-43% | Moderate, possible approval |
| >43% | High risk, harder approvals |
Improve capacity by paying down debts, avoiding new credit, and boosting income through raises or side gigs. Tools like credit simulators predict score impacts from DTI changes.
Capital: Showing Financial Reserves
Capital reflects personal investment via savings, assets, or down payments. Lenders favor borrowers with skin in the game, reducing default risk.
Liquid assets like emergency funds (3-6 months expenses) reassure lenders. High savings demonstrate discipline.
- Build reserves in high-yield accounts.
- Offer larger down payments on loans.
- Use credit-builder loans: repay held funds while reporting payments.
For real estate, 20% down avoids PMI, signaling strong capital. Track net worth to monitor progress.
Collateral: Securing the Loan
Collateral is assets pledged against loans, recoverable if default occurs. Secured loans (auto, mortgage) use vehicles or property as backing.
Unsecured credit relies solely on character and capacity, facing higher rates. Secured options suit thinner credit files.
Choose collateral wisely: over-borrowing risks asset loss. Credit-builder loans hold your deposit, returning it post-repayment with interest.
- Secured cards: Deposit sets limit, graduates to unsecured.
- Auto loans: Vehicle as collateral builds installment history.
Conditions: Navigating External Factors
Conditions encompass loan purpose, economic climate, and market trends. Lenders scrutinize if funds go to volatile ventures like startups.
Current rates, inflation, and employment data influence decisions. Stable jobs in growing sectors score higher.
Mitigate by applying during favorable conditions and shopping rates. Diversify credit mix (revolving, installment) positively affects scores.
Practical Strategies to Strengthen All 5 Cs
Integrate habits across Cs for holistic improvement.
- Monitor Reports: Free weekly from Equifax, Experian, TransUnion. Dispute inaccuracies.
- Low Utilization: Keep balances under 30% of limits. Request increases cautiously.
- Diversify Mix: Balance cards with loans responsibly.
- Authorized User: Join trusted family member’s card for history piggyback.
- Rent Reporting: Services add utility/rent to reports.
Patience yields results: scores rise with 6-12 months consistency.
Common Mistakes and Fixes
| Mistake | Impact | Fix |
|---|---|---|
| Minimum payments only | High interest, signals strain | Pay full or more |
| Multiple inquiries | Temporary score drop | Rate shop within 14-45 days |
| Maxing cards | High utilization hurts capacity | Pay down aggressively |
| Ignoring reports | Misses errors | Review annually minimum |
Tools and Resources for Credit Building
- Credit Simulators: Test scenarios.
- Apps: Track spending, reminders.
- Builder Products: Secured cards, credit-builder loans.
Co-signers aid startups but share liability.
FAQs
What if I have no credit history?
Start with secured cards or builder loans to establish payment history.
How long to build good credit?
3-6 months for initial score; 1-2 years for strong profile.
Does checking my score hurt it?
Soft pulls don’t; hard pulls temporary dip.
Can utilities build credit?
Some report via services.
What’s a good credit score?
670+ fair; 740+ excellent for best rates.
References
- The Best Ways to Build Credit With a Credit Card — Navy Federal Credit Union. 2023. https://www.navyfederal.org/makingcents/credit-debt/how-to-build-credit.html
- How to Build Credit: A Comprehensive Guide — Experian. 2024-01-15. https://www.experian.com/blogs/ask-experian/credit-education/improving-credit/building-credit/
- How to Build Your Credit Successfully — Intuit. 2023-06-20. https://www.intuit.com/blog/innovative-thinking/financial-tips/build-credit/
- What are some ways to start or rebuild a good credit history? — Consumer Financial Protection Bureau. 2024. https://www.consumerfinance.gov/ask-cfpb/what-are-some-ways-to-start-or-rebuild-a-good-credit-history-en-2155/
- How to Build Credit With and Without a Credit Card — NerdWallet. 2024-02-01. https://www.nerdwallet.com/finance/learn/how-to-build-credit
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


