

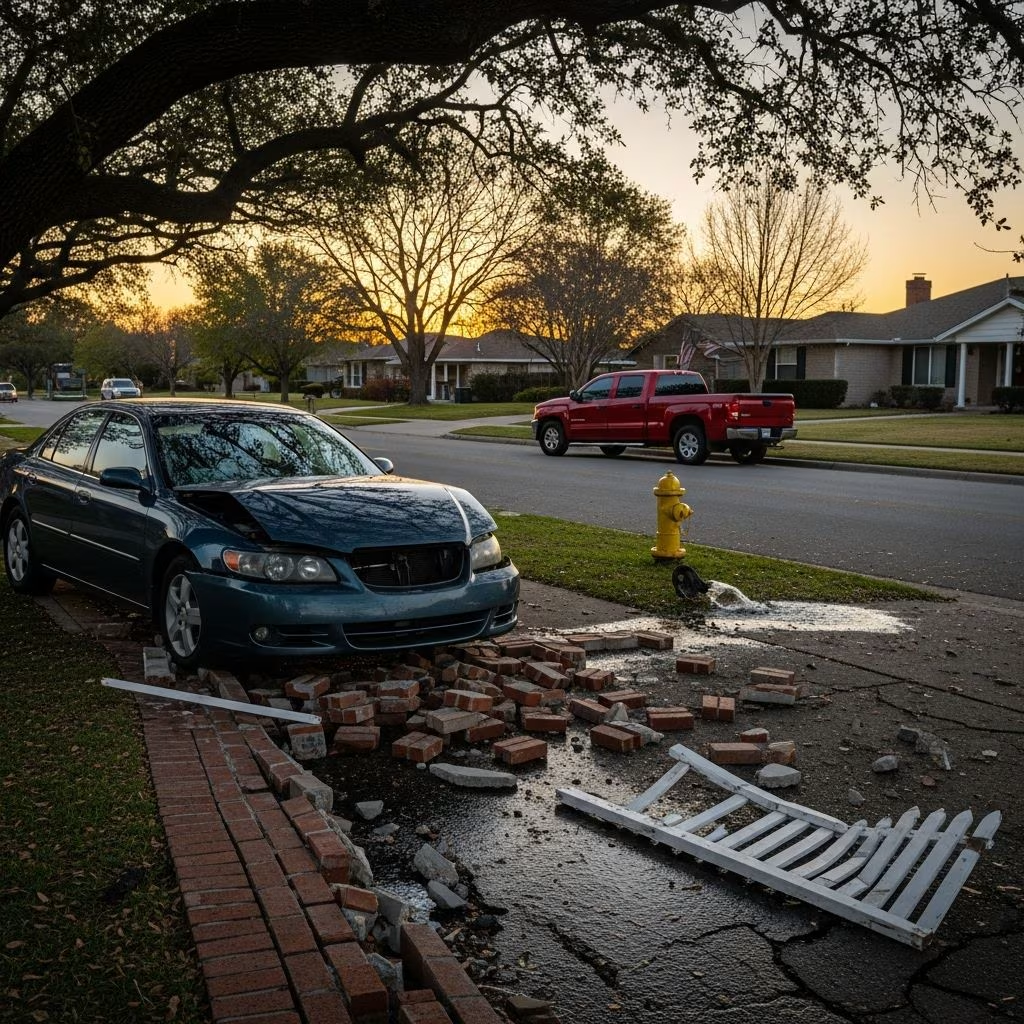
Property damage liability is a fundamental component of auto insurance policies, designed to cover the costs of repairing or replacing property belonging to others when you are at fault in an accident. This coverage ensures that drivers can avoid personal financial ruin from incidents involving vehicles, structures, or other assets.
Defining Property Damage Liability Coverage
This type of insurance falls under the broader umbrella of liability protection in car policies. It activates specifically when your vehicle causes harm to someone else’s tangible property during a collision for which you bear responsibility. Unlike collision or comprehensive coverage, which handle your own vehicle’s damage, property damage liability focuses exclusively on third-party losses.
Financial responsibility laws in nearly all states mandate this coverage, recognizing the potential for significant repair expenses in modern accidents. For example, even minor crashes can lead to thousands in damages due to advanced vehicle technologies and repair complexities.
What Does This Coverage Typically Include?
Property damage liability addresses a wide array of potential harms. Common examples include:
- Repairs or total loss replacement for other drivers’ cars, including parts and labor.
- Damage to stationary objects like fences, mailboxes, lampposts, guardrails, and utility poles.
- Structural impacts such as garages, homes, storefronts, or business facades.
- Environmental elements like trees, landscaping, or road signs affected by the incident.
- Business interruption costs, such as lost revenue if property damage forces a temporary closure.
In a scenario where a driver rear-ends another vehicle and then veers into a roadside fence, the policy would cover both the car’s bodywork and the fence reconstruction up to the policy limit.
State-Specific Minimum Requirements
Every U.S. state except New Hampshire requires drivers to carry property damage liability at specified minimum levels per accident. These thresholds vary widely to reflect local economic factors and repair costs. Here’s a comparison of select states:
| State | Minimum Property Damage Limit (Per Accident) |
|---|---|
| California | $5,000 |
| Texas | $25,000 |
| Nevada | $10,000 |
| Florida | $10,000 |
| Massachusetts | $5,000 |
These minima represent the least protection legally allowed, but experts recommend far higher amounts given escalating auto repair prices, which averaged over $4,000 per claim in recent years due to supply chain issues and tech integrations.
How Property Damage Claims Process Works
When an accident occurs, the at-fault driver’s insurer assesses liability through police reports, witness statements, and evidence. If responsibility is confirmed, the claim proceeds: the other party’s insurer or individual files with your provider, who then arranges inspections and authorizes payments for verified damages.
Coverage applies on a per-accident basis. If damages total $6,000 but your limit is $5,000, you cover the $1,000 excess personally, potentially through savings, loans, or lawsuits. Legal defense costs, like attorney fees from disputes, may also fall under this coverage.
Key Exclusions and Limitations
No insurance is all-encompassing. Property damage liability explicitly excludes:
- Damage to your own vehicle or property.
- Incidents during commercial use, such as ride-sharing (Uber/Lyft) or auto business operations.
- Non-consensual use of your vehicle by others.
- Racing, stunts, or intentional acts.
- Damage from wear-and-tear or unrelated mechanical failures.
Policyholders should review endorsements for ride-share or business extensions if applicable. Medical expenses require separate bodily injury or med-pay coverage.
Choosing Optimal Coverage Limits
While state minima suffice legally, adequacy demands higher thresholds. Consider:
Asset Protection: Limits below your net worth risk personal lawsuits for shortfalls.
Repair Cost Trends: Luxury vehicles or EVs can exceed $20,000 in fixes; structures add more.
Umbrella Policies: Supplemental excess liability starting at $1 million for comprehensive shielding.
Common recommendations: 100/30/25 (bodily injury per person/accident, property per accident) or higher, balancing premiums with risk.
Real-World Accident Scenarios
Urban Rear-End Collision: Striking a sedan ($4,500 repairs) and storefront awning ($2,200)—a $10,000 limit covers fully; $5,000 leaves you owing $1,700.
Rural Off-Road Drift: Hitting a mailbox ($800), fence ($3,000), and tree ($1,500)—total $5,300 tests low limits severely.
Multi-Vehicle Chain: Damaging two cars ($8,000 combined) plus a pole ($1,200)—higher limits prevent out-of-pocket hits.
These illustrate why underinsurance leads to 15-20% of drivers facing post-claim debts annually.
Cost Factors Influencing Premiums
Increasing limits raises rates modestly—often 10-20% for doubling coverage—due to algorithms factoring driving records, location, and vehicle type. Safe drivers in low-risk areas pay less.
- Discounts: Bundling home/auto, good credit, defensive courses reduce costs.
- High-Risk Adjustments: Tickets or claims hike premiums 30-50%.
Integration with Other Auto Coverages
Property damage complements:
- Bodily Injury Liability: Medical/income losses for others.
- Collision: Your vehicle fixes.
- Comprehensive: Theft/vandalism/weather.
- Uninsured Motorist Property Damage: Covers if other driver lacks insurance.
A balanced policy might read 100/300/100 for full liability.
Frequently Asked Questions
Is property damage liability required in all states?
Yes, in 49 states; New Hampshire permits alternatives like cash deposits.
Does it cover my own car?
No, collision coverage handles that.
What if damages exceed my limit?
You pay the difference, risking lawsuits.
Can I increase limits easily?
Yes, contact your insurer; shop annually for best rates.
Does it apply in no-fault states?
Yes, for property claims regardless of injury rules.
Steps to Verify and Enhance Your Coverage
- Review policy declarations for current limits.
- Compare state minima vs. your needs.
- Consult agents for personalized quotes.
- Consider umbrella for high assets.
- Update after life changes (e.g., new car).
Proactive management safeguards against surprises.
References
- What Is Property Damage Coverage and How Does It Work? — MAPFRE Insurance. 2023. https://www.mapfreinsurance.com/blog/property-damage-coverage/
- What is Property Damage Liability Insurance – AAA — AAA Northeast. 2024. https://mwg.aaa.com/insurance/car/articles/property-damage-liability
- Property Damage Coverage — Liberty Mutual. 2024. https://www.libertymutual.com/vehicle/auto-insurance/coverage/property-damage-coverage
- What Is Property Damage Liability? – Allstate — Allstate. 2023-07-01. https://www.allstate.com/resources/car-insurance/property-damage-liability-insurance
- What is Property Damage Liability Coverage? • Lemonade Car — Lemonade. 2024. https://www.lemonade.com/car/explained/property-damage-liability-coverage/
- Property Damage Liability Insurance Coverage | The Hartford — The Hartford. 2024. https://www.thehartford.com/aarp/car-insurance/property-damage-liability-insurance
- What Is Property Damage Liability Insurance? – Progressive — Progressive. 2024. https://www.progressive.com/answers/property-damage-liability/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


