

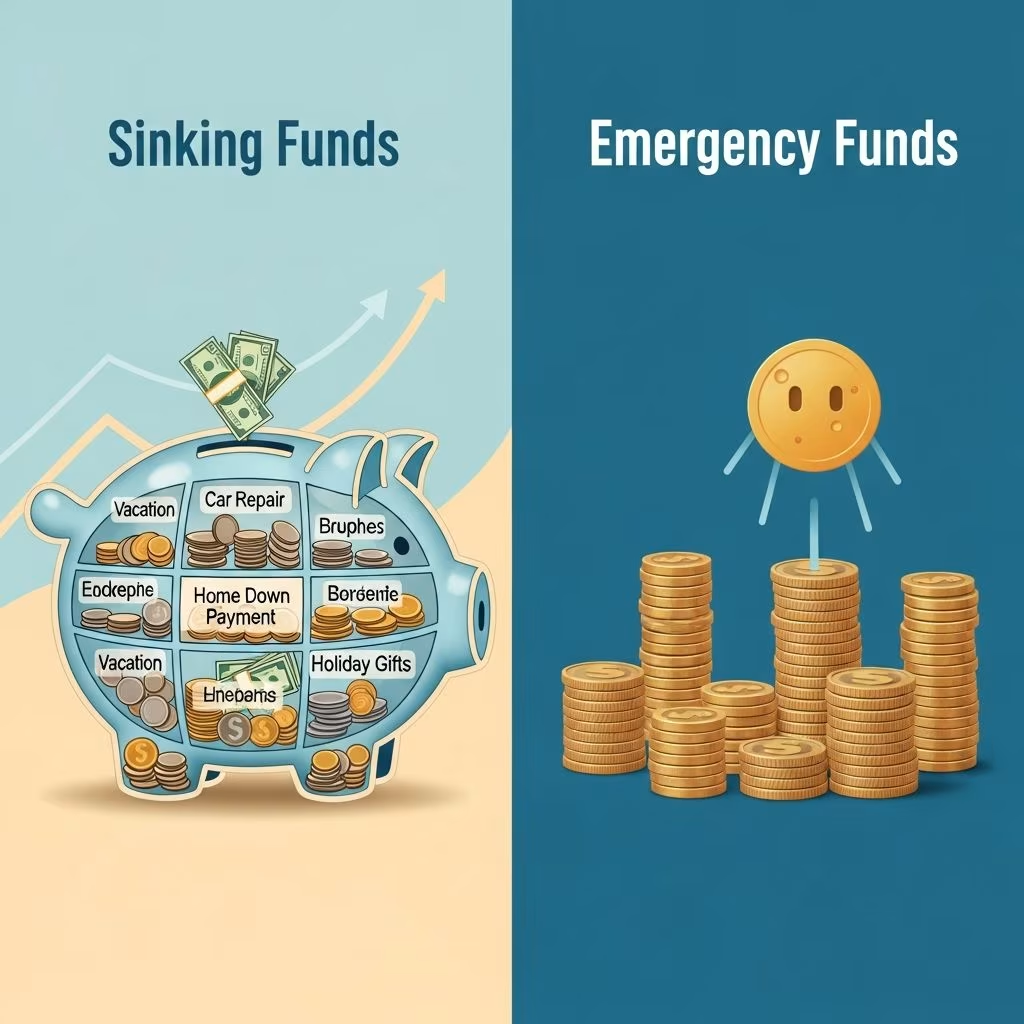
In the realm of personal finance, two types of savings stand out as essential tools for maintaining stability: sinking funds and emergency funds. While both involve setting money aside, they serve distinct purposes—one for anticipated expenses and the other for life’s curveballs. Understanding their differences empowers individuals to allocate resources wisely, avoid debt, and achieve financial goals without stress.
Defining the Core Concepts
A sinking fund represents a proactive savings approach where you systematically set aside money for a known, upcoming expense. This could range from seasonal costs like holiday gifts to larger investments such as home renovations or vehicle replacements. By breaking down the total cost into smaller, regular contributions, you ensure the full amount is available exactly when needed, preventing budget disruptions.
On the other hand, an emergency fund acts as a financial safety net for unforeseen crises. These might include sudden medical bills, job loss, or urgent car repairs. Experts emphasize that this fund should cover essential living expenses during tough times, typically without a predefined spending timeline or purpose beyond immediate survival.
Key Distinctions at a Glance
To clarify the divide, consider this comparison:
| Aspect | Sinking Fund | Emergency Fund |
|---|---|---|
| Purpose | Planned, predictable expenses | Unplanned, urgent crises |
| Timeline | Specific date or event | Indefinite, as needed |
| Examples | Annual taxes, vacations, insurance premiums | Job loss, medical emergencies, home repairs |
| Funding Strategy | Targeted monthly deposits | Build to 3-6 months of expenses |
| Account Type | Dedicated savings per goal | Liquid, high-yield savings |
This table highlights how sinking funds shift predictable costs from reactive spending to deliberate planning, preserving the emergency fund for true unpredictability.
Why Prioritize an Emergency Fund First
Financial advisors universally recommend establishing an emergency fund before diving into sinking funds. The rationale is straightforward: true emergencies can strike without warning, potentially derailing other savings efforts. A robust emergency fund—ideally 3 to 6 months’ worth of living expenses—provides peace of mind and prevents reliance on high-interest debt.
For instance, if unemployment hits, this fund covers rent, groceries, and utilities until stability returns. Without it, individuals might raid goal-specific savings or accumulate credit card debt, compounding financial strain.
Unlocking the Power of Sinking Funds
Once your emergency fund is solid, sinking funds become a game-changer for managing lumpy expenses. These irregular bills—think property taxes, car maintenance, or back-to-school supplies—often catch people off guard, leading to overspending or borrowing.
- Quarterly or Annual Bills: Divide the total by the number of months leading up. For a $1,200 insurance premium due yearly, save $100 monthly.
- Major Purchases: Planning a family vacation? Estimate costs and contribute consistently to avoid last-minute credit use.
- Homeownership Costs: Roofs, appliances, or HVAC servicing benefit from dedicated pots, turning potential shocks into smooth transactions.
The beauty lies in psychological ease: knowing funds are earmarked reduces impulse buys and fosters disciplined budgeting.
Step-by-Step Guide to Creating Sinking Funds
Building effective sinking funds requires intention. Follow these steps:
- Inventory Expenses: List all foreseeable costs within the next 12-24 months, including amounts and due dates.
- Calculate Contributions: Total cost divided by months until due equals your monthly set-aside. Adjust for interest if in a high-yield account.
- Choose Accounts: Use separate high-yield savings accounts or buckets within apps for each goal to track progress visually.
- Automate Transfers: Set up recurring deposits post-paycheck to build habitually.
- Review Quarterly: Reassess goals and adjust as life evolves.
For example, a $3,000 roof repair in 12 months means $250 monthly savings. Digital tools like banking apps make this seamless, often with goal-tracking features.
Integrating Both Funds into Your Budget
A balanced budget treats these funds as non-negotiable line items. Allocate 10-20% of income to savings overall: first to emergencies, then sinking goals. Use the 50/30/20 rule as a base—50% needs, 30% wants, 20% savings/debt—ensuring funds fit without strain.
Pro tip: Label accounts descriptively (e.g., “Car Fund”) to maintain mental separation. If an emergency overlaps a sinking goal—like a sudden roof leak—replenish the emergency fund promptly from future sinking contributions.
Real-Life Applications and Benefits
Consider a homeowner facing $2,400 annual property taxes. Without a sinking fund, December brings panic; with one, $200 monthly deposits cover it effortlessly. Similarly, holiday shopping becomes joy, not dread, when $50 weekly adds up.
Benefits extend beyond avoidance:
- Debt Reduction: Pre-funding eliminates credit needs.
- Stress Relief: Predictability enhances mental health.
- Goal Acceleration: Compound interest in savings accounts amplifies growth.
- Family Security: Models smart habits for children.
Overcoming Common Challenges
Starting feels daunting, but begin small. If cash flow is tight, prioritize 1-2 sinking funds. Temptation to dip in? Enforce a “no-touch” rule except for the designated purpose. Life changes? Pivot funds flexibly—unused vacation money could seed a home fund.
For high earners, multiple sinking funds enable ambitious goals like down payments or education savings. Low earners benefit equally by micro-saving $10-20 monthly.
Tools and Technologies to Simplify Management
Modern fintech shines here:
- Apps like Qapital or Digit automate rounding-up savings.
- Bank-specific accounts (e.g., target savers) offer sub-accounts.
- Spreadsheets track progress with formulas for projections.
High-yield accounts (4-5% APY) maximize returns on idle funds without risk.
Frequently Asked Questions (FAQs)
What if I need my sinking fund money early?
Redirect it strategically, but rebuild quickly to stay on track.
Can sinking funds earn interest?
Yes, park them in high-yield savings for passive growth.
How much should my emergency fund be?
3-6 months of essentials; more if self-employed.
Are sinking funds only for big expenses?
No—gifts, subscriptions, or dues qualify too.
What if emergencies deplete my fund?
Pause sinking contributions to rebuild first.
Long-Term Financial Harmony
Mastering sinking and emergency funds transforms reactive spending into empowered planning. This duo not only safeguards against shocks but propels progress toward dreams. Start today: assess your needs, open accounts, and automate. Financial freedom awaits those who prepare deliberately.
References
- What’s a Sinking Fund? Why Do I Need One? — Whitaker Wealth. 2023. https://www.whitakerwealth.com/posts/what-s-a-sinking-fund-why-do-i-need-one
- Sinking Fund vs. Emergency Fund: What’s the Difference and Where… — Jago. 2023. https://www.jago.com/en/blog/sinking-fund-emergency-fund-difference-how-to-save
- Emergency funds vs Sinking fund — ABC Bank. 2024. https://abcthebank.com/blog/emergency-funds-vs-sinking-fund/
- What Is a Sinking Fund and Why Do You Need One? — Central Bank. 2024. https://www.centralbank.net/learning-center/why-you-need-a-sinking-fund/
- What is the difference between an emergency fund and a sinking fund — Bayview Financial. 2023. https://www.bayviewfinancial.ca/blog/what-is-the-difference-between-an-emergency-fund-and-a-sinking-fund
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


