

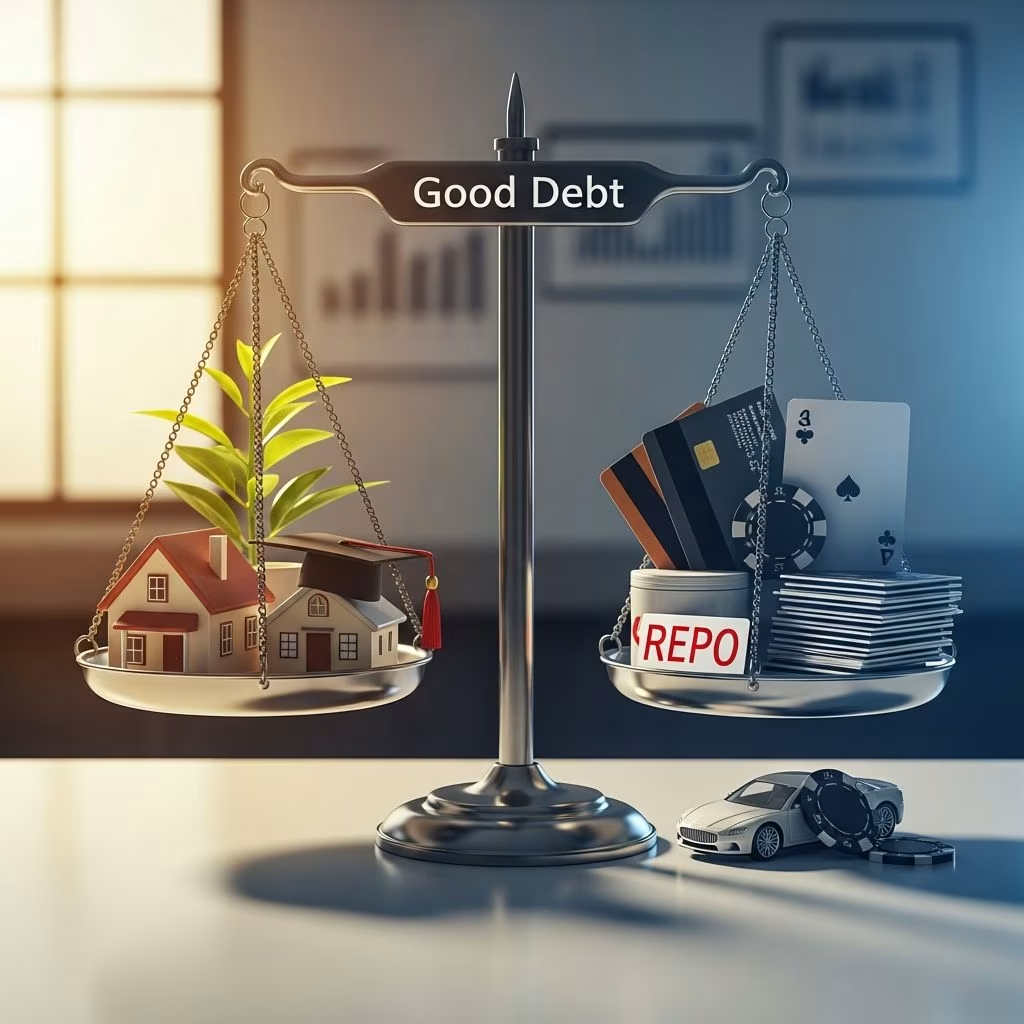
Debt often carries a negative stigma, but not all borrowing is detrimental. In fact, strategic use of credit can propel personal wealth and opportunities, while reckless debt accumulation leads to financial strain. This article explores the fundamental differences between good debt and bad debt, providing actionable insights to help you leverage credit effectively.
Defining the Core Concepts of Debt Types
At its essence, good debt involves borrowing to acquire assets or skills that appreciate in value or generate income over time. These loans typically feature lower interest rates and contribute positively to long-term financial health. Conversely, bad debt funds purchases that depreciate quickly or fail to yield returns, often burdened by high interest rates that amplify costs.
Understanding these categories requires evaluating factors like interest rates, repayment terms, and the purpose of the loan. Good debt acts as a tool for growth, while bad debt functions as a consumer trap, eroding wealth through interest payments on fleeting purchases.
Characteristics That Separate Good from Bad Debt
Several key traits distinguish these debt types:
- Asset Appreciation: Good debt targets investments like real estate, where property values may rise, offsetting borrowing costs.
- Income Potential: Loans for education enhance earning capacity, with college graduates often earning significantly more than high school graduates.
- Interest Rates: Beneficial debt usually has rates below 6%, making repayment manageable.
- Depreciation Risk: Bad debt finances items like vehicles or luxury goods that lose value immediately.
- Credit Impact: Responsible good debt can improve credit scores through on-time payments, whereas excessive bad debt raises utilization ratios, harming scores.
| Factor | Good Debt | Bad Debt |
|---|---|---|
| Purpose | Builds assets/income | Funds consumption |
| Interest Rate | Low (e.g., <6%) | High (e.g., >20%) |
| Asset Behavior | Appreciates | Depreciates |
| Credit Effect | Positive with management | Negative if mismanaged |
Prime Examples of Good Debt
Mortgages top the list of good debt. Homeownership allows equity buildup as properties often increase in value, and mortgage interest may be tax-deductible when used for home improvements. Home equity lines of credit (HELOCs) extend this benefit, funding renovations that boost property worth.
Student loans qualify as good debt when they lead to higher-paying careers. Federal options often carry lower rates and tax-deductible interest, with data showing graduates earn about $32,000 more annually than non-grads. Business loans also fit, enabling ventures that generate revenue and jobs.
Securities-based lines of credit offer another avenue, using investment portfolios as collateral for low-rate borrowing without selling assets, preserving growth potential. These examples illustrate how good debt serves as financial leverage.
Common Pitfalls of Bad Debt
Credit card debt exemplifies bad debt due to sky-high APRs, often exceeding 20%. The average U.S. balance hovers around $6,000-$6,730, turning everyday purchases into long-term burdens. Items bought—like clothing or electronics—depreciate rapidly, leaving borrowers with interest payments on vanishing value.
Car loans fund depreciating assets; vehicles lose 20-30% of value upon driving off the lot. Payday and title loans are predatory, with exorbitant rates trapping users in cycles of debt. Borrowing for luxuries like boats or jewelry amplifies this issue, as high-interest financing outpaces any utility.
The Dual Impact on Credit Scores and Wealth
Good debt, managed well, diversifies credit mix and builds payment history—key score factors. However, overborrowing turns it sour; excessive student loans can overwhelm budgets. Bad debt spikes utilization ratios above 30%, dinging scores and limiting future options.
Wealth-wise, good debt compounds net worth through appreciating assets. A mortgage might yield home equity gains surpassing interest costs. Bad debt erodes savings via interest, with no residual value. Balance is crucial: even good debt becomes problematic if it exceeds repayment capacity.
Strategies for Using Debt to Your Advantage
To maximize good debt:
- Compare rates and terms rigorously.
- Ensure the investment’s return exceeds borrowing costs.
- Maintain payments to preserve credit health.
Avoid bad debt by:
- Paying credit cards in full monthly.
- Saving for big purchases instead of financing.
- Building emergency funds to sidestep payday loans.
Financial leverage thrives with discipline. Assess your debt-to-income ratio, aiming below 36%, and prioritize high-interest payoffs first.
When Good Debt Turns Bad: Warning Signs
Too much debt flips the script. Overleveraging on a mortgage risks foreclosure if values drop. Student loans balloon if degrees don’t yield jobs. Monitor total obligations; if they strain cash flow, refinance or consolidate.
Personal tolerance matters—some thrive with leverage, others prefer minimal debt. Regularly review statements and scores to stay ahead.
Building a Debt-Savvy Financial Plan
Incorporate debt into broader planning:
- Set clear goals: homeownership, education, business startup.
- Calculate affordability using online tools.
- Diversify: mix good debt types without overload.
- Track progress quarterly.
Educate yourself on tax perks, like deductible mortgage or student interest, to optimize. Consult advisors for personalized leverage strategies.
FAQs
Is a car loan always bad debt?
Not inherently, but most are due to rapid depreciation. Opt for cash purchases or large down payments to mitigate.
Can student loans be bad?
Yes, if amounts exceed future earnings potential or payments become unmanageable.
How does debt affect my credit score?
Positive payment history boosts it; high utilization harms it. Keep ratios low.
What’s a healthy debt level?
Debt-to-income under 36%; focus on quality over quantity.
Should I avoid all debt?
No—strategic good debt accelerates goals, but minimize bad types.
References
- Good Debt vs. Bad Debt: How to Use Credit Wisely — Charles Schwab. 2023. https://www.schwab.com/learn/story/good-debt-vs-bad-debt-wellness-screening
- Good Debt/Bad Debt — Western Sun Federal Credit Union. 2024. https://www.wsfcu.com/good-debt-bad-debt/
- Understanding Credit: Good Debt vs. Bad Debt — Equifax. 2024. https://www.equifax.com/personal/education/credit/report/articles/-/learn/understanding-credit-good-debt-vs-bad-debt/
- What’s the difference between good and bad debt? — Investec. 2023. https://www.investec.com/en_za/focus/financial-wellness/good-debt-vs-bad-debt.html
- Good debt vs bad debt — Fidelity Investments. 2024. https://www.fidelity.com/learning-center/smart-money/good-debt-vs-bad-debt
- Financial Leverage: What Is Good Debt vs Bad Debt? — U.S. Bank. 2024. https://www.usbank.com/wealth-management/financial-perspectives/financial-planning/financial-leverage-what-is-good-debt-vs-bad-debt.html
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


