

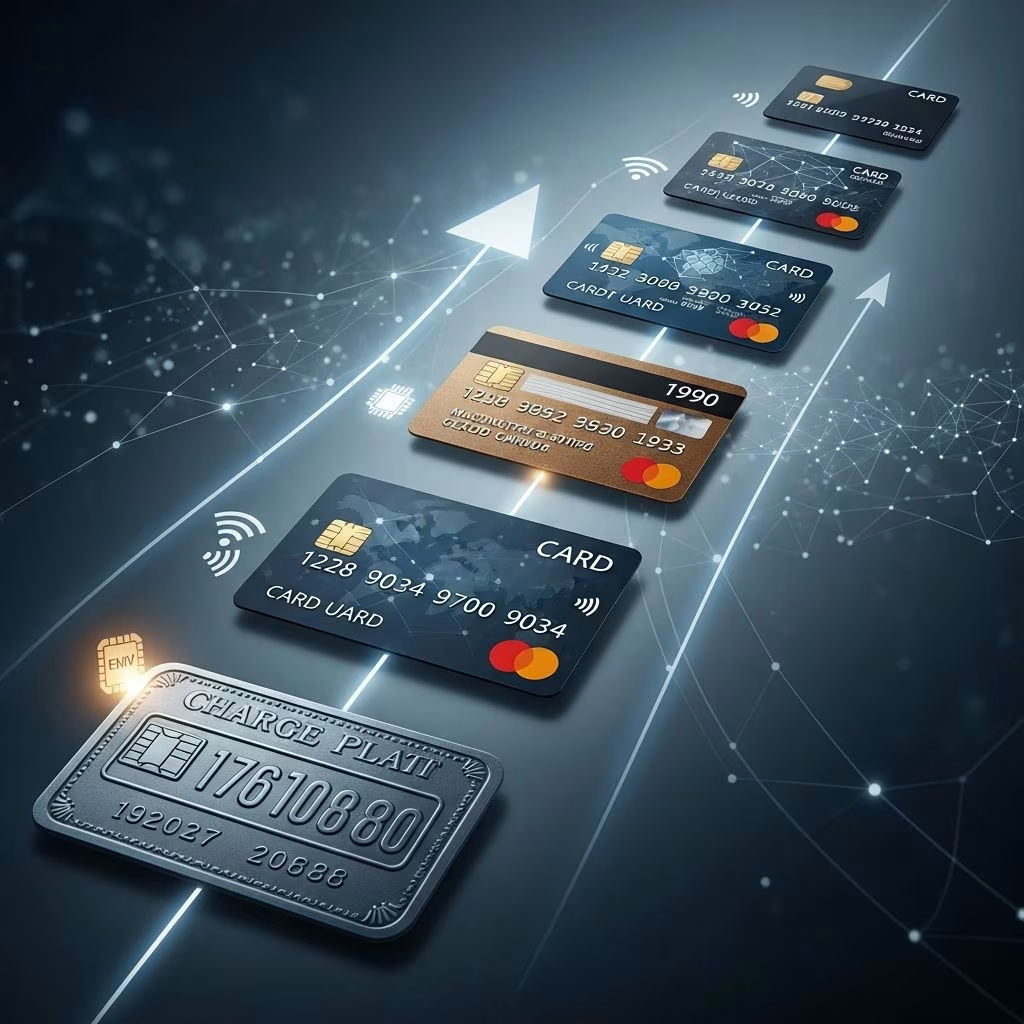
Credit cards have reshaped global commerce, evolving from rudimentary metal tokens to sophisticated digital tools. This journey spans over 150 years, driven by technological breakthroughs, regulatory reforms, and shifting consumer needs.
Ancient Roots and Early Experiments
While modern credit cards emerged in the 20th century, the concept of deferred payments dates back millennia. In ancient Mesopotamia around 2000 BCE, clay tablets recorded loans of grain and livestock, functioning as primitive credit records. By the 18th century, European merchants extended informal credit to trusted customers, often tracked via handwritten ledgers.
The late 19th century marked the shift toward physical credit identifiers. In 1865, some U.S. retailers issued charge coins—small metal or celluloid discs embossed with account numbers and store details. Customers presented these for purchases, with bills settled monthly. These coins were store-specific, limiting their utility but building familiarity with credit-based buying.
By 1914, Western Union pioneered metal charge plates, rectangular tags storing customer data for quick imprinting on receipts. The 1920s and 1930s saw widespread adoption of similar Charga-Plates by department stores like Macy’s and Gimbels. Over 1,400 U.S. stores offered such systems by 1941, per Federal Reserve data, embedding credit into retail culture despite fragmentation.
Birth of Travel and Bank-Issued Cards
Aviation’s rise spurred specialized cards. In 1934, American Airlines and the Air Transport Association launched the Air Travel Card, allowing passengers to book flights on credit. Within a decade, 17 airlines accepted it, proving demand for multi-merchant cards.
Post-World War II innovation accelerated. In 1946, Brooklyn banker John Biggins introduced the Charg-It card, usable at local merchants with the bank handling billing. This was among the earliest bank-backed programs, fostering customer loyalty.
The pivotal moment arrived in 1950 with Diners Club. Founder Frank McNamara, after forgetting cash at a NYC restaurant, created a 2,000-card network for 27 eateries. By 1953, it expanded internationally and to hotels, becoming the first general-purpose charge card—requiring full monthly payment.
Revolving Credit and Network Expansion
1958 brought revolving credit via Bank of America’s BankAmericard. In a bold “Fresno Drop,” the bank mailed 60,000 unsolicited cards to Fresno residents, allowing balance carryover with interest. Despite initial fraud, it grew rapidly; by 1960, nearly a million cards circulated, accepted at 61,000 merchants across 42 states by 1966.
To scale nationally, Bank of America licensed the program, birthing the BankAmericard network (later Visa in 1976). Meanwhile, in 1966, 23 banks formed the Interbank Card Association (ICA). Rebranded Master Charge in 1969 and Mastercard in 1979, it mirrored Visa’s shared-network model, standardizing issuance and acceptance.
American Express entered with its 1959 PVC plastic card, boosting portability over metal predecessors. Diners Club followed suit, ditching celluloid for durable plastic.
Security Upgrades: From Stripes to Chips
Manual imprinting dominated early use, prone to errors and fraud. IBM engineer Forrest Parry invented the magnetic stripe in 1969, embedding data for electronic readers. By the 1970s, it enabled real-time authorization via first POS terminals from Visa, slashing settlement times.
| Era | Technology | Impact |
|---|---|---|
| 1969-1970s | Magnetic Stripe | Automated verification, reduced fraud |
| 1990s | EMV Chips | Dynamic encryption, counterfeit resistance |
| 2000s | Contactless NFC | Tap-and-go speed, post-COVID surge |
EMV (Europay, Mastercard, Visa) chips debuted in 1994 Europe, generating unique codes per transaction. U.S. adoption lagged until the 2015 liability shift, forcing merchants to upgrade POS systems or bear chip-fraud costs.
Contactless payments emerged in 1995 Korea, with U.S. pilots mid-2000s via Visa PayWave and Mastercard PayPass. COVID-19 accelerated adoption; by 2025, tap-to-pay dominates for hygiene and speed.
Regulatory Milestones Protecting Consumers
Unsolicited mass-mailing in the 1960s-1970s—over 100 million cards—sparked crime waves and backlash. Congress responded with landmark laws:
- 1968: Truth in Lending Act (TILA)/Consumer Credit Protection Act (CCPA) Mandated clear APR disclosures and billing transparency.
- 1974: Fair Credit Billing Act (FCBA) Allowed billing error disputes within 60 days.
- 1974/1976: Equal Credit Opportunity Act (ECOA) Banned discrimination by sex, race, or marital status.
- 2009: CARD Act Curbed unfair practices like retroactive rate hikes and inadequate notices.
December 2004’s PCI DSS 1.0 standardized data security, enforced by networks.
Rewards, Personalization, and Digital Shift
1984 saw Diners Club launch ClubRewards, the first program offering points for travel. Today, rewards drive loyalty, with cashback, miles, and perks.
2007 innovations included Capital One’s customizable designs and LED-display cards from Mastercard/Visa. Apple Pay’s 2014 debut introduced tokenization—replacing card numbers with secure tokens—via NFC wallets.
Global Impact and Future Horizons
By 2025, billions use cards worldwide, fueling e-commerce and buy-now-pay-later hybrids. Blockchain and biometrics promise further security; central bank digital currencies may integrate.
Credit cards democratized access but raised debt concerns—U.S. household averages exceed $6,000. Education and tools like scores mitigate risks.
Key Milestones Table
| Year | Milestone |
|---|---|
| 1865 | Charge coins introduced |
| 1914 | Western Union metal plates |
| 1934 | Air Travel Card |
| 1946 | Charg-It bank card |
| 1950 | Diners Club launches |
| 1958 | BankAmericard (Visa precursor) |
| 1966 | Interbank Card Association (Mastercard) |
| 1969 | Magnetic stripe |
| 1974 | Key consumer protection laws |
| 1994 | EMV chips |
| 2014 | Apple Pay |
| 2015 | U.S. EMV liability shift |
Frequently Asked Questions
What was the first true credit card?
Diners Club in 1950, usable at multiple merchants unlike store-specific plates.
When did revolving credit begin?
1958 with BankAmericard’s Fresno launch, allowing interest-bearing balances.
How did magnetic stripes change payments?
Enabled electronic reads, replacing manual imprints for faster, secure processing.
What laws protect card users today?
TILA, FCBA, ECOA, and CARD Act ensure transparency and fairness.
Are contactless cards safe?
Yes, with tokenization and encryption; limits on low-value taps add protection.
References
- Credit Card History: A Complete Timeline to 2025 — PayCompass. 2025. https://paycompass.com/blog/credit-card-history/
- A Look at the History of Credit Cards & the Evolution of Payments — Paragon Edge. N/A. https://www.paragonedge.com/blog/a-look-at-the-history-of-credit-cards-and-the-evolution-of-payments
- The History of the Credit Card — SwipeSum. N/A. https://www.swipesum.com/insights/history-of-the-credit-card
- When Did Credit Cards Become Popular: History and Evolution — Juztcard. N/A. https://juztcard.com/resources/when-did-credit-cards-become-popular-history-and-evolution
- The Complete History of Credit Cards, from Antiquity to Today — The Points Guy. N/A. https://thepointsguy.com/credit-cards/history-of-credit-cards/
- The History of Credit Cards — Experian. N/A. https://www.experian.com/blogs/ask-experian/the-history-of-credit-cards/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


