

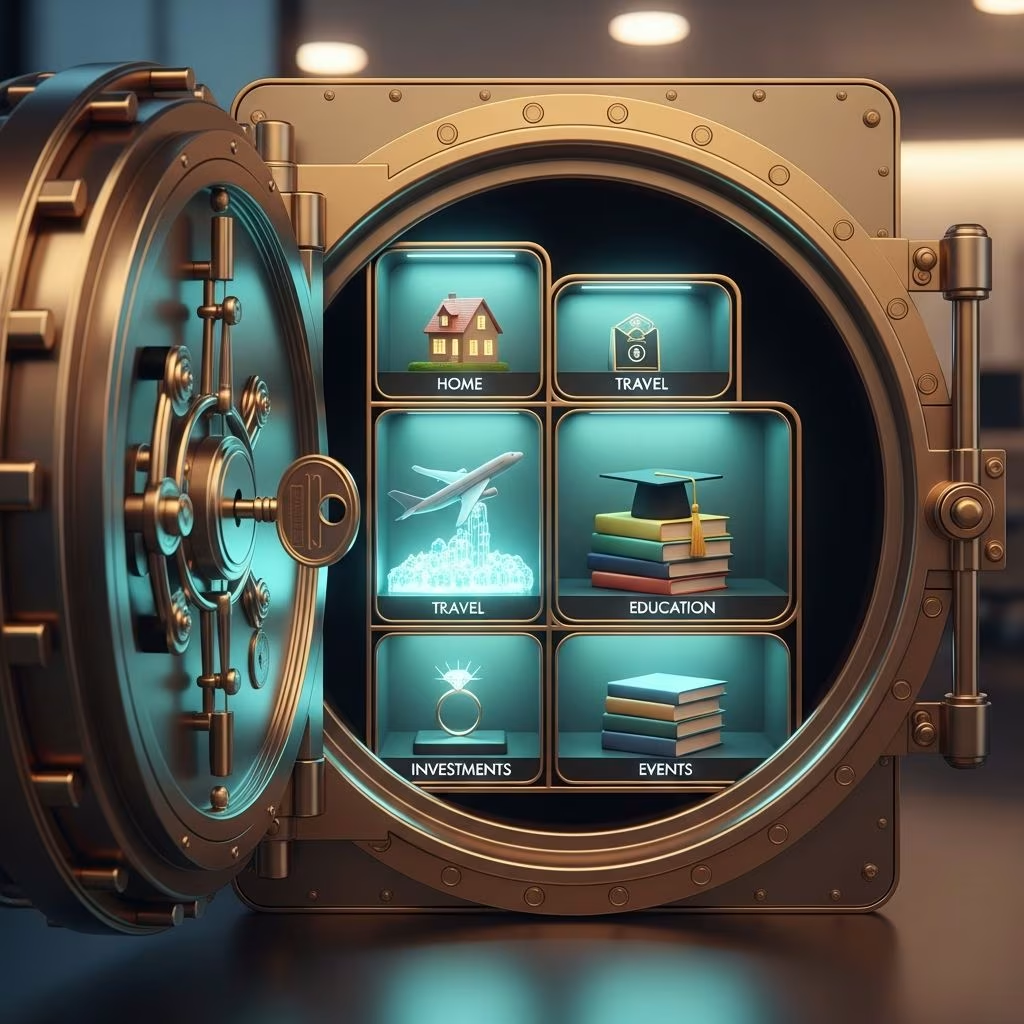
Savings vaults represent a modern evolution in personal banking, allowing individuals to compartmentalize their savings into dedicated digital sub-accounts for distinct financial objectives. This feature empowers users to pursue several goals simultaneously without the confusion of mingling funds, fostering disciplined saving habits through automation and clear visibility.
The Rise of Goal-Oriented Digital Savings Tools
In an era where financial pressures mount from unexpected expenses to long-term aspirations, traditional savings accounts often fall short. Savings vaults address this by mimicking physical envelopes or jars digitally, but with enhanced capabilities like interest accrual and seamless transfers. Banks and fintechs have popularized these tools to help consumers build wealth methodically.
Originating from the concept of ‘sinking funds’—where money is set aside incrementally for foreseeable costs—these vaults have gained traction amid rising interest rates and economic uncertainty. As of 2026, with national average APYs climbing, vaults in high-yield accounts amplify returns on segmented savings.
Core Mechanics: How Savings Vaults Function
At their essence, savings vaults operate as nested compartments within a primary savings or checking account. Users designate ‘vaults’ for specific purposes, such as vacations, home repairs, or holiday gifts. Key functionalities include:
- Sub-Account Creation: Instantly set up multiple vaults, often up to five or more, without extra fees.
- Automated Funding: Schedule recurring transfers from checking or direct deposits to populate vaults effortlessly.
- Progress Tracking: Visual dashboards display balances, goal percentages, and projected completion dates.
- Flexible Access: Move funds back to main balances fee-free, with security limits to prevent impulsive spending.
- Interest Earnings: Many vaults earn competitive APYs, sometimes exceeding 4% on balances up to $5,000.
Unlike separate physical accounts, vaults consolidate everything under one login, simplifying oversight while psychologically separating ‘locked’ goal money from spendable cash.
Advantages That Set Savings Vaults Apart
The primary appeal lies in their ability to streamline multifaceted saving. Here’s a breakdown of benefits:
| Feature | Benefit | Example Impact |
|---|---|---|
| Multiple Goals | Track 3-10 objectives concurrently | Save for car ($5K), wedding ($10K), emergency ($3K) separately |
| No Fees | Free setup/maintenance with direct deposit | Save $5-15/month vs. traditional methods |
| High APY | Earn 4-5% on vaulted funds | $1K at 4.5% yields $45/year |
| Mobile Integration | Real-time alerts and adjustments | Adjust contributions on-the-go |
| Psychological Boost | Reduces ‘money blindness’ | 33% more likely to meet goals per studies |
These perks make vaults ideal for visual learners and busy professionals, turning abstract saving into tangible milestones.
Popular Providers and Their Unique Offerings
Several institutions lead in vault innovation:
- GO2bank: Offers up to 5 vaults at 4.50% APY (up to $5K combined), quarterly payouts, and unlimited free transfers with direct deposit.
- Green Dot: Free Money Vault for emergencies or goals; no interest but unlimited in/out moves subject to limits.
- SoFi: Vaults nested under high-yield savings; goal-setting tools and progress trackers enhance motivation.
- U.S. Bank & Others: Bucket-style features for lifestyle goals, often paired with robust checking integration.
Choosing depends on APY needs, fee waivers (e.g., via direct deposit), and vault limits.
Step-by-Step Guide to Setting Up Your First Vault
- Select a Provider: Compare APYs and features via bank apps or sites.
- Open/Link Account: Ensure direct deposit for fee waivers; vaults typically activate instantly.
- Create Vaults: Name them (e.g., ‘Car Downpayment’), set targets, and deadlines.
- Automate Deposits: Link payroll or schedule weekly pulls (e.g., $50/vault).
- Monitor & Tweak: Use app notifications to stay on track; transfer out upon goal hit.
Pro Tip: Start small—allocate 10-20% of income across 3 vaults for balanced progress.
Real-World Applications: Goals That Thrive with Vaults
Vaults excel for both short- and long-term aims:
- Emergency Fund: 3-6 months’ expenses; untouchable until needed.
- Travel: Break down flights, lodging, fun money.
- Homeownership: Down payment, closing costs, furnishings.
- Debt Payoff: Extra payments beyond minimums.
- Seasonal: Holidays, taxes, back-to-school.
A family saving for a $20K home reno might split into ‘Materials’ ($10K), ‘Labor’ ($8K), ‘Contingency’ ($2K), hitting targets 20% faster via automation.
Potential Drawbacks and Mitigation Strategies
No tool is perfect:
- APY Caps: E.g., GO2bank limits rewards at $5K; diversify if balances grow.
- No FDIC Confusion: Funds remain fully insured under main account.
- Over-Segmentation: Too many vaults dilute focus; cap at 5-7.
- Interest Variability: Rates fluctuate; lock high APYs promptly.
Mitigate by reviewing quarterly and consolidating completed vaults.
Maximizing Returns: Pairing Vaults with High-Yield Accounts
For optimal growth, embed vaults in HYSA (national avg. ~0.45%, top tiers 4-5%). Example: $200/month into a 4.5% vault yields ~$120 interest/year per goal. Use FDIC.gov to verify insurance up to $250K/account.
Comparing Vaults to Traditional Methods
| Method | Pros | Cons |
|---|---|---|
| Savings Vaults | Automation, tracking, interest | Bank-specific availability |
| Multiple Accounts | Full separation | Fees, login overload |
| Spreadsheets | Free, customizable | No automation, error-prone |
| Cash Envelopes | Tactile | No interest, theft risk |
Vaults win for tech-savvy users seeking efficiency.
Frequently Asked Questions (FAQs)
Are savings vaults FDIC-insured?
Yes, as extensions of insured accounts, up to $250K per depositor per bank.
Do all banks offer vaults?
No, primarily fintechs like GO2bank, SoFi; check your app.
Can I earn interest in every vault?
Most do, but confirm (e.g., Green Dot does not).
What’s the max number of vaults?
Varies: 5 (GO2bank), unlimited in some.
Are there fees for transfers?
Typically none, especially with direct deposit.
Future Trends: Vaults in 2026 and Beyond
Expect AI-driven goal predictions, gamified rewards, and crypto integration. With rates potentially peaking, now’s prime time to vault up.
References
- What Are Savings Vaults? — Experian. 2023. https://www.experian.com/blogs/ask-experian/what-are-savings-vaults/
- 5 Key Factors of a GO2bank Savings Vault — GO2bank. 2024. https://www.go2bank.com/blog/money-moves/5-factors-of-savings-vault
- What is the Money Vault? — Green Dot. 2024. https://www.greendot.com/helpcenter/use-your-card/money-vault/what-is-the-money-vault
- What is the difference between Savings and Vaults? — SoFi. 2024. https://support.sofi.com/hc/en-us/articles/34726683548173-What-is-the-difference-between-Savings-and-Vaults
- Savings Accounts with Buckets — NerdWallet. 2025. https://www.nerdwallet.com/banking/learn/savings-accounts-with-buckets
- How to use savings buckets — U.S. Bank. 2024. https://www.usbank.com/financialiq/manage-your-household/personal-finance/savings-buckets.html
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


