

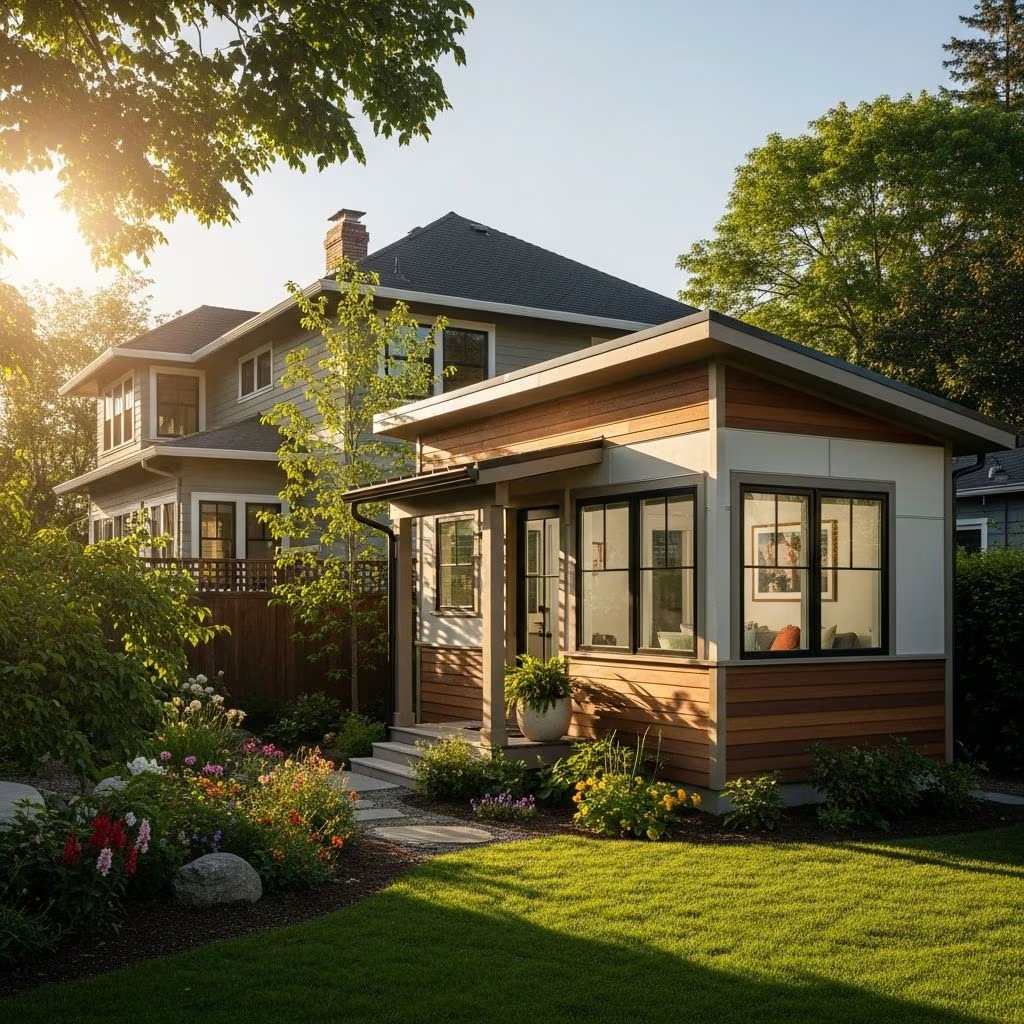
Accessory dwelling units (ADUs) offer homeowners versatile solutions for multigenerational living, rental income, or extra space. Properly insuring these structures is crucial to protect against financial losses from damage, liability claims, or income disruption. This guide explores coverage options, influencing factors, and practical steps to secure your ADU.
Understanding Accessory Dwelling Units and Insurance Needs
ADUs, also known as granny flats or in-law suites, are secondary residential units on the same property as a primary home. They can be attached, like basement conversions, or detached, such as backyard cottages. Insurance requirements hinge on location, attachment type, occupancy, and usage.
Standard homeowners policies may extend to certain ADUs, but modifications are often necessary. Failing to notify your insurer about an ADU can void coverage during claims, leaving you exposed to high rebuilding costs that average $150,000 or more for detached units.
Types of ADUs and Their Insurance Implications
ADU configurations directly impact insurance approaches. Here’s a breakdown:
- Attached ADUs: These include garage conversions or additions sharing walls with the main house. They typically integrate into the primary dwelling coverage, requiring only a policy limit increase.
- Detached ADUs: Freestanding structures fall under ‘other structures’ coverage, capped at 10% of dwelling limits—often insufficient for full rebuilds.
- Interior Conversions: Basement or attic apartments usually qualify as part of the main home, simplifying coverage adjustments.
| ADU Type | Typical Coverage | Key Considerations |
|---|---|---|
| Attached | Homeowners policy endorsement | Increase dwelling limits for added value |
| Detached | Other structures or separate policy | Check 10% cap; may need landlord if rented |
| Interior | Existing dwelling coverage | Notify insurer of square footage change |
Coverage Under Homeowners Insurance for ADUs
Homeowners policies can adapt to ADUs via endorsements, covering core perils like fire, wind, hail, and vandalism. Essential protections include:
- Dwelling Coverage: Repairs or rebuilds the ADU structure after covered losses.
- Personal Property: Replaces homeowner-furnished items like appliances inside the unit.
- Liability: Defends against injury lawsuits on the property, covering legal and medical costs.
- Other Structures: Applies to detached units, but limits apply.
For family-occupied ADUs, even with nominal rent, many carriers extend homeowners coverage. However, long-term rentals to unrelated tenants shift needs toward specialized policies.
Landlord Insurance: Essential for Rental ADUs
Renting an ADU introduces tenant-related risks, necessitating landlord or dwelling fire insurance. This policy safeguards:
- Structural damage from covered events.
- Landlord-owned appliances and furnishings.
- Liability for tenant injuries or third-party claims.
- Lost rental income during uninhabitability.
Landlord policies cost about 25% more than standard homeowners equivalents, influenced by unit size, location risks, and construction quality. In high-demand rental markets, this investment protects steady income streams.
Factors Influencing ADU Insurance Costs
Premiums vary based on multiple elements:
- Construction and Size: Larger, premium-material units raise rebuilding costs.
- Location Risks: Crime rates, weather hazards like floods or earthquakes demand add-ons.
- Usage: Rental status increases rates due to higher liability.
- Attachment: Detached units often incur higher or separate premiums.
Expect a 15-30% overall policy hike post-ADU addition. Shop multiple quotes to optimize rates.
Optional Coverages to Strengthen ADU Protection
Base policies may fall short amid rising construction costs. Enhance with:
- Extended Replacement Cost: Boosts dwelling coverage by 20-50% for inflation.
- Inflation Guard: Automatically adjusts limits yearly.
- Guaranteed Replacement: Covers full rebuilds exceeding policy limits.
Separate flood and earthquake policies are vital, as standard policies exclude them—critical in prone areas.
Legal and Financing Requirements for ADU Insurance
No universal mandate exists for ADU insurance, but lenders financing construction via HELOCs or refinances require it to protect collateral. Non-compliance risks foreclosure if damage prevents loan repayment.
Local zoning laws may impose habitability standards, indirectly mandating coverage. Always verify state-specific rules, as they dictate permissible ADU features like independent utilities.
Steps to Insure Your ADU Effectively
- Notify Your Insurer Early: Before or during construction, discuss ADU plans to adjust coverage proactively.
- Assess Coverage Gaps: Review limits against rebuild estimates from contractors.
- Compare Policies: Consult agents for endorsements vs. standalone options.
- Document Everything: Photos, blueprints, and upgrades aid claims.
- Review Annually: Update for changes in usage or local risks.
Common Pitfalls and How to Avoid Them
Homeowners often overlook ADU disclosures, leading to denied claims. Business use, like home offices in ADUs, voids standard coverage—secure commercial add-ons. Detached rentals without landlord policies expose owners to uncovered tenant disputes.
Mitigate by consulting independent agents familiar with ADUs, ensuring policies match your scenario.
State-Specific Considerations for ADU Insurance
Regulations vary: California promotes ADUs with streamlined permitting, often allowing homeowners coverage for attached units. Massachusetts emphasizes landlord add-ons for rentals. Check municipal codes for address, utility, and rental restrictions impacting insurability.
FAQs
Can I add an ADU to my existing homeowners policy?
Yes, for attached or family-occupied units via endorsement, but confirm with your carrier.
What’s the difference between homeowners and landlord insurance for ADUs?
Homeowners suits personal use; landlord covers rentals with income loss protection.
Does insurance cover ADU rebuilding costs fully?
Not always—other structures limits may cap detached units; opt for extended coverage.
Are floods covered for ADUs?
No, require separate NFIP flood insurance.
How much does ADU insurance cost?
Expect 15-25% policy increase, higher for rentals; varies by factors like location.
References
- How Do You Insure an Accessory Dwelling Unit? — Experian. 2023. https://www.experian.com/blogs/ask-experian/how-do-you-insure-accessory-dwelling-unit/
- Dwelling on Details: Answering the Essential Questions About Insurance-Protected Use Accessory Dwelling Units — Mass.gov. 2023-10-01. https://www.mass.gov/news/dwelling-on-details-answering-the-essential-questions-about-insurance-protected-use-accessory-dwelling-units
- Accessory Dwelling Units (ADUs) and Home Insurance — Mercury Insurance. 2024. https://www.mercuryinsurance.com/resources/home/accessory-dwelling-units-adus-and-home-insurance.html
- Insurance Guide for ADUs: How to Protect Your Investment — Maxable Space. 2023. https://maxablespace.com/insurance-guide-for-adus-how-to-protect-your-investment/
- What Is an Accessory Dwelling Unit (ADU)? — Travelers Insurance. 2024. https://www.travelers.com/resources/home/insuring/what-is-adu
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


