

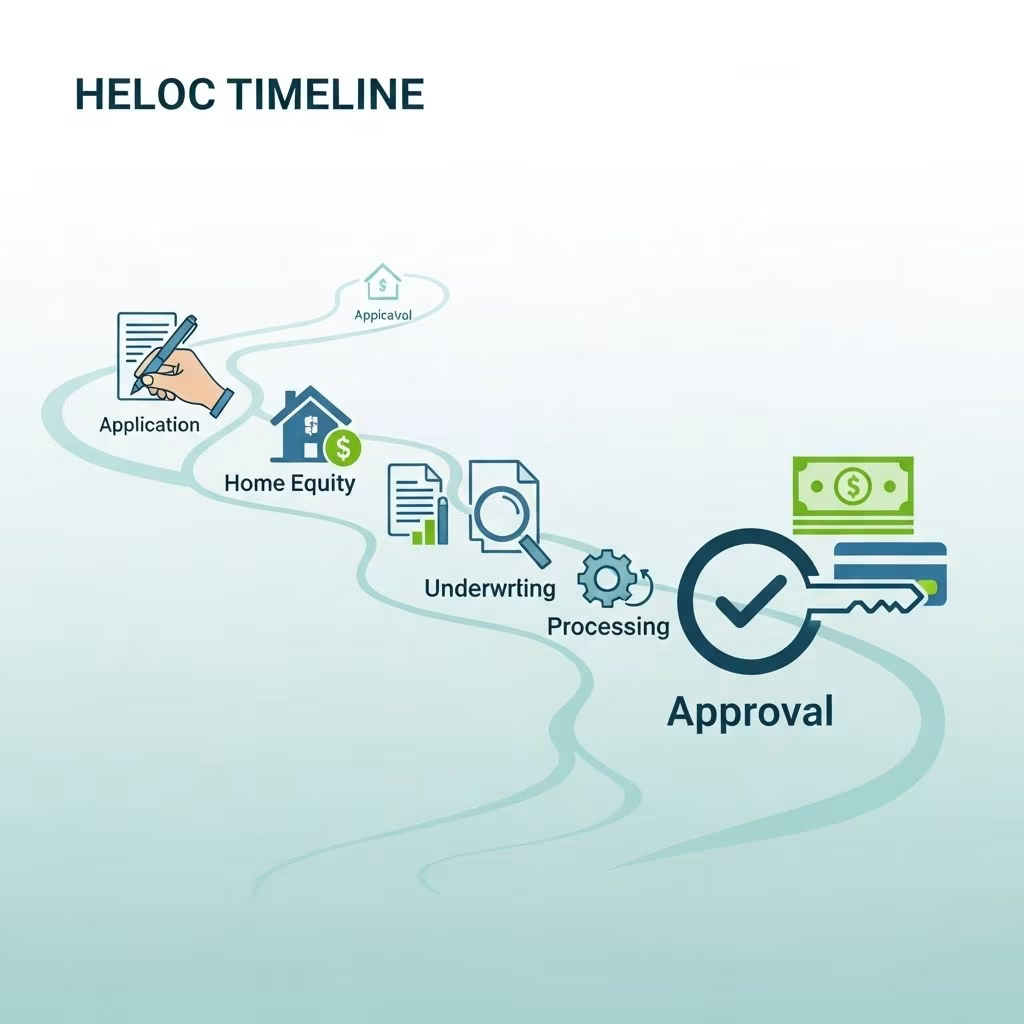
A Home Equity Line of Credit (HELOC) provides homeowners with flexible access to funds based on their property’s equity. Unlike a traditional loan, it functions like a credit card secured by your home, allowing draws during a specific period. Understanding the timeline for obtaining one is crucial for planning renovations, debt consolidation, or major expenses. The entire process typically spans 30 to 45 days, though it can vary based on lender efficiency, your preparedness, and external factors like appraisals.
Understanding What a HELOC Entails
Before diving into timelines, grasp the basics. A HELOC lets you borrow against the equity in your home—the difference between its market value and your outstanding mortgage balance. Lenders usually allow borrowing up to 85% of your home’s value minus what you owe, provided you meet other criteria. For instance, if your home is worth $400,000 and you owe $240,000, you have $160,000 in equity. Lenders might extend a line up to $136,000 (85% of value minus mortgage).
HELOCs feature two phases: a draw period (often 10 years) where you can borrow and pay interest only, followed by a repayment period (10-20 years) for principal and interest. Interest rates are variable, tied to the prime rate, making them sensitive to market changes.
Core Eligibility Criteria for HELOC Approval
Securing a HELOC demands meeting stringent financial benchmarks. Lenders prioritize these factors to mitigate risk since your home serves as collateral.
- Minimum Credit Score: Most require a FICO score of 660-720; higher scores yield better terms. Scores below 680 may still qualify with strong equity or income.
- Home Equity Threshold: At least 15-20% equity is standard, equating to a loan-to-value (LTV) ratio of 80-85% or less.
- Debt-to-Income (DTI) Ratio: Below 43% preferred, calculated as monthly debts divided by gross income.
- Stable Income: Proof via pay stubs, W-2s, tax returns, or bank statements confirms repayment ability.
- Payment History: Clean record without recent late payments or bankruptcies.
- Homeowners Insurance: Active policy required to protect the collateral.
Review your finances beforehand. Tools like free credit reports from AnnualCreditReport.com can reveal issues early.
Step-by-Step HELOC Application Journey
The process unfolds in sequential phases, each contributing to the overall timeline. Preparation accelerates progress.
Phase 1: Research and Prequalification (1-3 Days)
Shop lenders—banks, credit unions, online platforms—comparing rates, fees, and draw periods. Many offer prequalification online, providing instant estimates without a hard credit inquiry. Gather basics: home value estimate, mortgage balance, income, and debts.
Phase 2: Formal Application Submission (1-2 Days)
Submit a full application with documents: ID, income proofs (pay stubs for 30 days, two years’ tax returns), property deed, recent mortgage statements, and bank records. Digital applications speed this up; expect conditional approval within hours to days.
Phase 3: Underwriting and Credit Review (5-10 Days)
Underwriters verify details, pulling your credit report and assessing DTI. This is where discrepancies can delay things—respond promptly to requests for more info. Initial credit approval often occurs here.
Phase 4: Property Appraisal (7-14 Days)
A professional appraiser evaluates your home’s current value, crucial for equity calculation. Costs $300-$500, often lender-ordered. Delays arise in high-demand areas or complex properties. Some lenders use automated valuations for faster turnaround.
Phase 5: Final Underwriting and Approval (3-7 Days)
Post-appraisal, underwriters finalize terms: credit limit, rate, fees. You’ll receive a commitment letter outlining details.
Phase 6: Closing and Funding (3-5 Days)
Sign documents (online or in-person), pay closing costs (1-5% of line, including appraisal, title fees—sometimes rolled in). Funds become available days after recording. Total from application to draw: 30-40 days typically.
Timeline Comparison Table:
| Phase | Average Duration | Potential Delays |
|---|---|---|
| Research/Prequalify | 1-3 days | Lender shopping |
| Application | 1-2 days | Document issues |
| Underwriting/Credit | 5-10 days | Verification needs |
| Appraisal | 7-14 days | Scheduling/appraiser backlog |
| Final Approval | 3-7 days | Title issues |
| Closing/Funding | 3-5 days | Signing delays |
| Total | 30-45 days | Market conditions |
Factors Influencing Your HELOC Timeline
Several variables can shorten or extend the process.
- Market Conditions: High demand for appraisals lengthens waits; digital lenders are quicker.
- Your Readiness: Pre-collected documents cut days off.
- Property Type: Unique homes take longer to appraise.
- Credit Complexity: Multiple debts or disputes slow underwriting.
- Lender Type: Credit unions may be faster for members; big banks have more bureaucracy.
In peak seasons (spring/summer), add 1-2 weeks.
Costs Associated with Obtaining a HELOC
Beyond time, budget for fees averaging 2-5% of the line:
- Appraisal: $300-500
- Application/Origination: $0-1,000 (waived by some)
- Title Search/Insurance: $200-400
- Attorney/Closing: $300-1,500
- Annual Fees: $50-75 (optional)
Shop for no-closing-cost options, though they may have higher rates.
Strategies to Accelerate Your HELOC Process
Proactive steps can shave weeks:
- Boost Credit Early: Pay down debts; dispute errors.
- Prepare Documents: Organize in digital folders.
- Choose Efficient Lenders: Opt for online platforms with e-closing.
- Get a Head-Start Appraisal: Some allow private ones.
- Apply Mid-Week: Avoid weekend slowdowns.
Monitor rates; lock if favorable, as HELOCs are variable.
Common Pitfalls and How to Avoid Them
Avoid delays by sidestepping errors:
- Incomplete apps lead to back-and-forth.
- Ignoring DTI—calculate yours first: (Debts/Income) x 100.
- Overlooking equity—use Zillow for estimates, but appraisals rule.
- Not shopping—rates vary 1-2%.
Alternatives if HELOC Timeline is Too Long
If urgency strikes:
- Home Equity Loan: Fixed-rate lump sum, similar process.
- Cash-Out Refinance: Replaces mortgage, potentially slower.
- Personal Loan: Unsecured, faster but higher rates.
- 0% Balance Transfer Cards: Short-term for smaller needs.
Frequently Asked Questions (FAQs)
What is the fastest way to get a HELOC?
Choose digital lenders, prepare all docs upfront, and apply during low-volume periods for 2-3 week approvals.
Can I get a HELOC with bad credit?
Possible below 680 with high equity/income, but expect higher rates or denials.
How much can I borrow with a HELOC?
Up to 85% of home value minus mortgage, capped by DTI and lender policy.
Are HELOC closing costs tax-deductible?
Potentially if used for home improvements; consult a tax advisor.
What if my home appraises low?
Negotiate with lender or build more equity before reapplying.
References
- Home Equity Line of Credit (HELOC) | Home Loans – U.S. Bank — U.S. Bank. 2025. https://www.usbank.com/home-loans/home-equity/home-equity-line-of-credit.html
- How to apply for a home equity line of credit (HELOC) — Rocket Mortgage. 2025. https://www.rocketmortgage.com/learn/how-to-apply-for-a-heloc
- HELOC Application Process — Heritage Family Credit Union. 2025. https://www.hfcuvt.com/post/heloc_application_process.html
- Requirements for a Home Equity Loan or HELOC — Experian. 2025. https://www.experian.com/blogs/ask-experian/requirements-for-home-equity-loans-and-helocs/
- How To Get A Home Equity Line Of Credit (HELOC) — CU SoCal. 2025. https://www.cusocal.org/resources/blog/getting-a-home-equity-line-of-credit-heloc/
- Applying for a Home Equity Loan — Navy Federal Credit Union. 2025. https://www.navyfederal.org/loans-cards/equity/resources/how-to-apply.html
- Understanding the HELOC process — First Financial Bank. 2025. https://www.bankatfirst.com/personal/discover/flourish/understanding-the-heloc-process.html
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


