

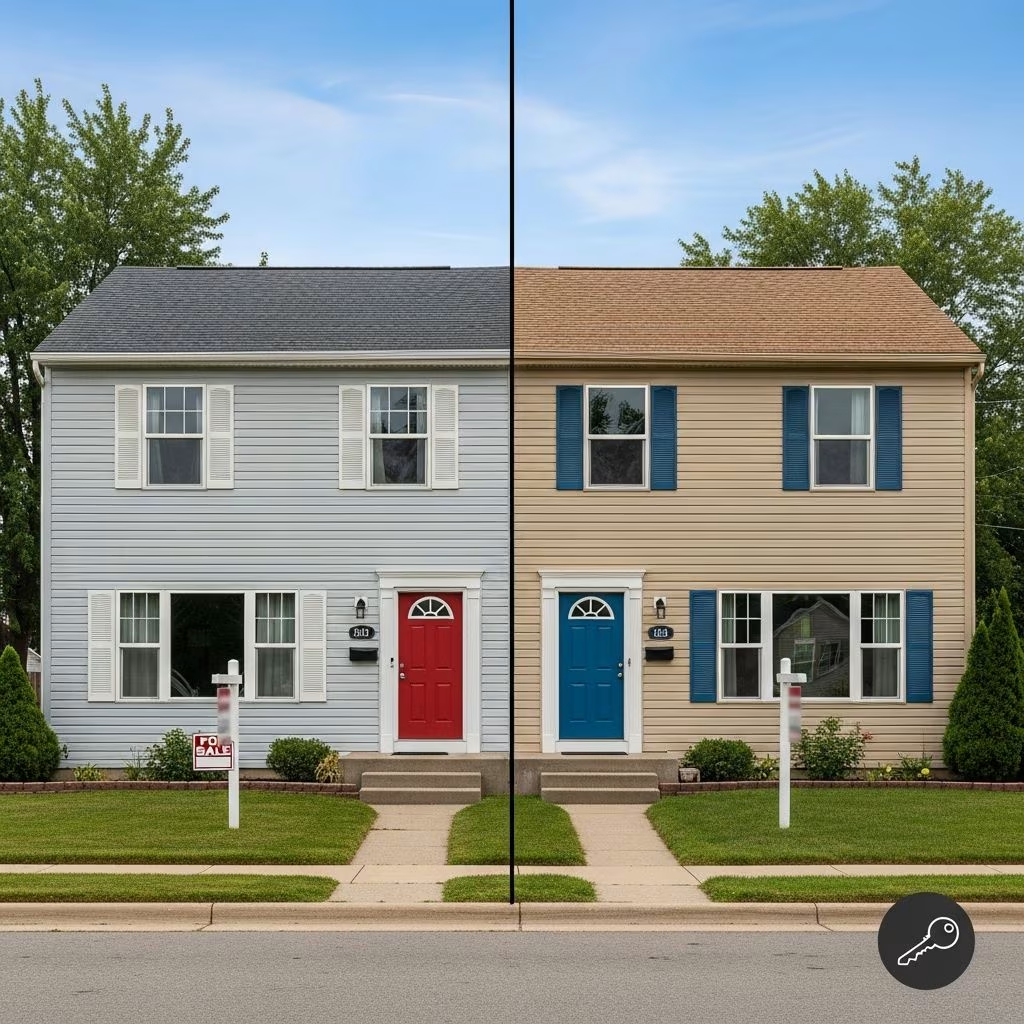
Duplexes represent a strategic entry into real estate ownership, combining residential living with income generation. These properties feature two separate living units under one roof, allowing owners to reside in one while renting the other—or leasing both for pure investment returns. With favorable financing options and rising demand for multifamily homes, buying a duplex can accelerate wealth building compared to single-family houses.
Why Consider a Duplex Investment?
Duplex ownership appeals to diverse buyers, from first-timers seeking affordability to seasoned investors eyeing passive income. According to industry data, over 17 million renters occupy two- to four-unit dwellings, underscoring strong market demand. Key advantages include:
- Income Stream: Rent from one unit can cover up to 50-100% of your mortgage, reducing personal housing costs.
- Affordability Edge: Duplexes often cost less per unit than comparable single-family homes, especially in emerging neighborhoods.
- Equity Growth: Dual units appreciate together, doubling potential gains while rental income supports maintenance.
- Tax Benefits: Deduct mortgage interest, property taxes, and depreciation on rented portions.
- Flexibility: House family in one unit or scale to triplexes later.
However, challenges exist: higher upfront costs, landlord duties, and vacancy risks demand careful planning. Investors must weigh these against single-family alternatives, where duplexes shine in cash flow potential.
Financial Readiness: Budgeting for Success
Before searching listings, solidify your financial foundation. Calculate affordability using the 28/36 rule: housing costs should not exceed 28% of gross income, with total debt under 36%.
| Expense Category | Estimated Cost (% of Purchase Price) | Example ($500K Duplex) |
|---|---|---|
| Down Payment (Owner-Occupied) | 3-5% (FHA) | $15K-$25K |
| Down Payment (Investment) | 15-25% | $75K-$125K |
| Closing Costs | 2-5% | $10K-$25K |
| Monthly PITI (Principal, Interest, Taxes, Insurance) | N/A | $3K-$4K |
| Reserves (6 Months) | N/A | $18K-$24K |
Factor in ongoing expenses: maintenance (1% of value annually), insurance (25% higher for multifamily), and potential vacancies. Use the 1% rule: aim for combined rents at 1% of purchase price monthly (e.g., $5K rent on $500K property).
Navigating Financing Pathways
Financing hinges on occupancy: living in one unit unlocks better terms. Compare options below:
| Loan Type | Min Down Payment | Min Credit Score | Occupancy | 2026 Limits (Most Areas) |
|---|---|---|---|---|
| FHA | 3.5% | 580 | Primary Residence | $693K (Duplex) |
| VA | 0% | None | Primary Residence | Conforming Limits |
| Conventional (Owner-Occupied) | 5% | 620-700 | Primary | $1.06M (Duplex) |
| Conventional (Investment) | 15-25% | 660-680 | None | $1.06M (Duplex) |
FHA and VA loans suit owner-occupants, requiring residence for 1 year minimum. Investment loans demand larger down payments and reserves (6 months PITI). Prequalify early to strengthen offers. For fixer-uppers, FHA 203(k) covers repairs up to total project cost with 3.5% down.
Finding the Ideal Duplex
Target neighborhoods with low vacancy (under 5%), strong schools, and job growth. Use platforms like Zillow or agents specializing in multifamily. Evaluate via:
- Rental Comps: Verify rents via listings or appraisers; ensure 1% rule viability.
- Cap Rate: (Net Income / Price) x 100; aim for 8-12%.
- Condition: Prioritize updates to minimize capex.
- Zoning: Confirm multifamily allowance; check HOA rules.
Partner with a buyer’s agent experienced in duplexes to access off-market deals and negotiate.
Due Diligence: Inspections and Appraisals
Professional inspections are non-negotiable, costing $400-800 but revealing issues like roof leaks or plumbing failures. Request sewer scopes and radon tests. Lenders appraise for loan-to-value; if value lags, renegotiate price.
Review leases if occupied: verify rents, tenant history, and eviction records. Calculate net operating income (NOI): Gross Rents – Expenses.
Closing the Deal
Secure insurance (landlord policy), title search, and finalize underwriting. Expect 30-45 days from offer to close. Post-purchase, screen tenants rigorously: credit checks, income verification (3x rent), and references.
Maximizing Returns Long-Term
Optimize with professional management if hands-off (8-10% of rents). Raise rents annually per market (3-5%). Refinance after seasoning to pull equity for more properties. Duplexes scale: use income to fund triplexes.
Track metrics quarterly: occupancy, cash flow, ROI. In strong markets, force appreciation via renovations (e.g., $20K kitchen yields $40K value).
Frequently Asked Questions
Can first-time buyers afford a duplex?
Yes, FHA loans require just 3.5% down if owner-occupied, making entry accessible.
Is duplex insurance more expensive?
Typically 25% higher due to rental coverage; shop multiple quotes.
Can I rent both units immediately?
Owner-occupants must live in one unit for 1 year on FHA/VA; investors face stricter financing.
What if the duplex needs repairs?
FHA 203(k) loans bundle purchase and rehab costs.
How much rental income should I expect?
Target 1% of price monthly combined; varies by location.
References
- Guide to Buying a Duplex — SoFi. 2023. https://www.sofi.com/learn/content/buying-a-duplex/
- Buy & Live In a Duplex, Triplex or Fourplex to Earn Rental Income — My Mortgage Insider. 2024. https://mymortgageinsider.com/multi-unit-properties/
- How to Buy a Duplex as a Rental Property — Amplify Credit Union. 2024. https://www.goamplify.com/blog/business/how-to-buy-a-duplex/
- Buying a Duplex: What You Should Know — LendingTree. 2024. https://www.lendingtree.com/home/mortgage/how-to-finance-a-duplex/
- Is Investing in Duplexes Right for You? Learn the Pros & Cons — Real Wealth. 2023. https://realwealth.com/learn/investing-in-duplexes/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


