

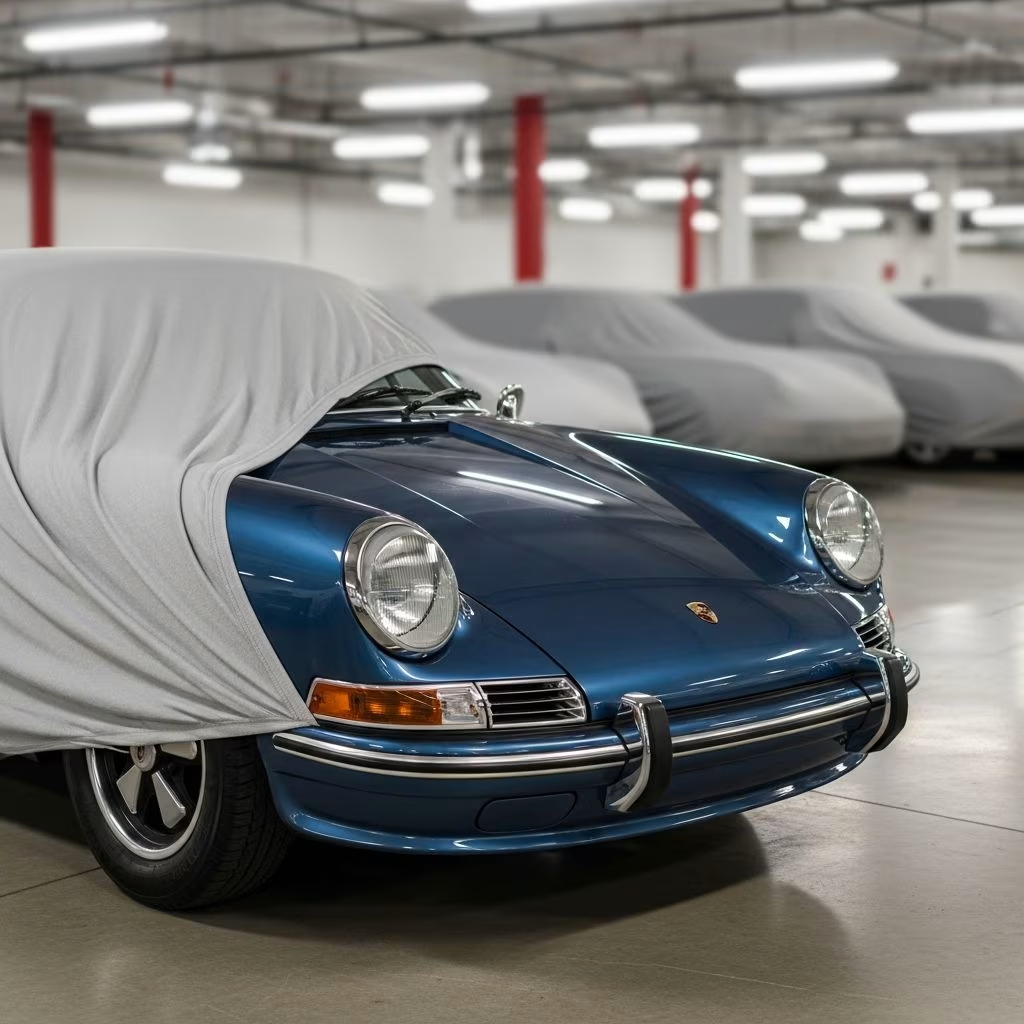
Vehicle owners often wonder about maintaining insurance when placing a car in long-term storage, such as during winter months or extended trips. While full coverage might not always be necessary, dropping all protection can expose you to significant risks and potential legal issues. This article examines key considerations, including legal mandates, recommended coverage levels, and practical steps for managing policies effectively.
Legal Requirements Across States
Insurance obligations for stored vehicles vary by location. In many states, if the car remains registered, minimum liability coverage must stay active regardless of usage. This ensures public safety standards are met even for non-driven vehicles. Deregistering the vehicle through your local Department of Motor Vehicles (DMV) or Bureau of Motor Vehicles (BMV) can sometimes allow full policy cancellation, but this process involves paperwork and may delay reactivation.
For instance, states like California and New York require proof of insurance for registered cars, stored or not. Owners should verify with their DMV: submit forms indicating non-operation status to avoid fines or registration suspension. Failure to comply could result in penalties, including license suspension or increased future premiums.
Risks of Canceling Insurance Completely
Eliminating all coverage might seem cost-effective short-term, but it leaves vehicles vulnerable. Common threats include theft, vandalism, fire, hail, or structural damage from falling objects like trees. Without protection, repair costs fall entirely on the owner—potentially thousands for high-value cars.
- Theft: Stored cars in garages or facilities remain targets for opportunistic criminals.
- Weather events: Hail storms or floods can cause extensive damage indoors or out.
- Vandalism: Accessible locations heighten risks from graffiti or broken windows.
- Fire hazards: Electrical issues or nearby blazes pose dangers even in storage.
Additionally, policy lapses create gaps in driving history, flagging you as high-risk upon reinstatement. This often leads to 20-50% premium hikes, depending on the insurer.
Optimal Coverage: Comprehensive-Only Policies
The most practical solution for stored cars is switching to comprehensive-only coverage, suspending liability and collision components. This targets non-driving perils while slashing premiums by up to 70%.
Comprehensive insurance covers:
- Non-collision theft or attempted theft.
- Weather-induced damage (hail, wind, floods).
- Vandalism and malicious mischief.
- Fire, explosion, or animal collisions.
- Falling or flying objects.
Insurers like Allstate and Progressive typically require 30+ days of storage before approval. The vehicle must remain stationary—no test drives allowed, as this violates terms and leaves you uninsured for liability.
| Coverage Type | Protects Against | Typical Premium Savings | Best For |
|---|---|---|---|
| Full Policy | Driving accidents, theft, weather | Baseline cost | Active daily drivers |
| Comprehensive-Only | Theft, weather, vandalism | 50-70% lower | Long-term storage (30+ days) |
| No Coverage | Nothing | 100% savings (risky) | Not recommended |
Lender and Lease Considerations
Financed or leased vehicles often mandate continuous full coverage per loan agreements. Lenders protect their investment, requiring proof of insurance via electronic monitoring. Suspending coverage without permission risks loan default, repossession, or forced-place insurance at exorbitant rates (2-3x standard premiums).
Contact your lender early: some allow comprehensive-only with documentation of storage status. Always obtain written approval to avoid disputes.
Storage Location Impacts
Where you store the vehicle influences both risks and insurance needs. Home garages offer basic shelter but expose cars to family-related incidents or neighborhood hazards. Professional facilities vary:
- Secure indoor units: Lowest risk, potentially qualifying for premium discounts.
- Outdoor lots: Higher exposure to elements, may require enhanced comprehensive limits.
- Climate-controlled: Ideal for classics, protecting against humidity or temperature swings.
Some facilities, like Extra Space Storage, demand active auto insurance or their customer protection plan (covering contents or vehicle value inside units). Review facility contracts carefully.
Steps to Adjust Your Policy for Storage
Proactive communication with your insurer ensures smooth transitions. Follow these steps:
- Notify your agent: Provide storage duration, location, and deregistration proof if applicable.
- Request suspension: Ask for comprehensive-only; confirm minimum storage period (often 30 days).
- Document everything: Get confirmation in writing, including reactivation process.
- Prepare the vehicle: Disconnect battery, inflate tires, use fuel stabilizer to prevent issues during storage.
- Monitor policy: Set calendar reminders for seasonal changes.
Reactivating Coverage Safely
Before driving, reinstate full coverage—liability and collision—at least 24-48 hours prior. Insurers may require vehicle inspection or proof of roadworthiness. Re-register if deregistered, paying any fees.
Transporting from storage? Standard policies often exclude towing or transit; consider temporary add-ons or commercial haulers with their own insurance. Test drive only after full reinstatement to avoid illegal operation.
Cost-Saving Strategies
Beyond coverage reduction:
- Bundle policies: Combine with home/renters for multi-policy discounts.
- Shop around: Compare quotes from Progressive, State Farm, Allstate for storage options.
- Seasonal adjustments: For snowbirds or seasonal vehicles, time suspensions precisely.
- Usage-based programs: Low-mileage trackers may further reduce rates.
Average savings: $800-1,500 annually for a $2,000 full policy, per insurer estimates.
Frequently Asked Questions
Can I drive my stored car occasionally?
No. Suspended liability means no legal driving; even short trips risk fines or uncovered accidents. Reinstate full coverage first.
What’s the minimum storage time for reduced coverage?
Typically 30 days, varying by insurer. Some allow immediate suspension.
Does storing off-site change requirements?
Facilities may mandate insurance; indoor units often lower premiums due to reduced risk.
How do I deregister for storage?
Contact your DMV for non-operation affidavits; requirements differ by state.
Will a lapse affect my rates long-term?
Yes, gaps signal high risk, increasing future premiums significantly.
Protecting Classic and Specialty Vehicles
Collector cars demand specialized policies. Standard comprehensive may suffice, but classic car insurers offer agreed-value coverage (pays full appraised worth, not depreciated market value). Storage in heated garages qualifies for lower rates. Annual mileage limits (e.g., 2,500 miles) align well with seasonal use.
For RVs or boats in off-season storage, similar rules apply: suspend driving coverages, retain comprehensive against weather or theft.
Conclusion
Maintaining appropriate insurance during storage safeguards your asset without unnecessary expense. Comprehensive-only coverage strikes the ideal balance for most scenarios, but always align with state laws, lender terms, and storage conditions. Consult your agent and DMV promptly to customize a plan. This approach prevents costly surprises and preserves your insurance record.
References
- Do I Need Insurance For A Car In Storage? — Allstate. 2023. https://www.allstate.com/resources/car-insurance/insuring-a-car-in-storage
- Does a Car in Storage Need Insurance? — Rec Nation Storage. 2024. https://www.recnationstorage.com/blog/does-a-car-in-storage-need-insurance/
- Do I Need Insurance for a Car in Storage? — Progressive. 2024. https://www.progressive.com/answers/insurance-car-in-storage/
- Car Storage Insurance: Everything You Need to Know — Car and Driver. 2023. https://www.caranddriver.com/car-insurance/a36190680/car-storage-insurance/
- Preparing for Long Term Car Storage — State Farm. 2024. https://www.statefarm.com/simple-insights/auto-and-vehicles/preparing-for-longterm-car-storage
- Does a car in storage need insurance? — Extra Space Storage. 2024. https://www.extraspace.com/self-storage/faq/does-a-car-in-storage-need-insurance/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


