

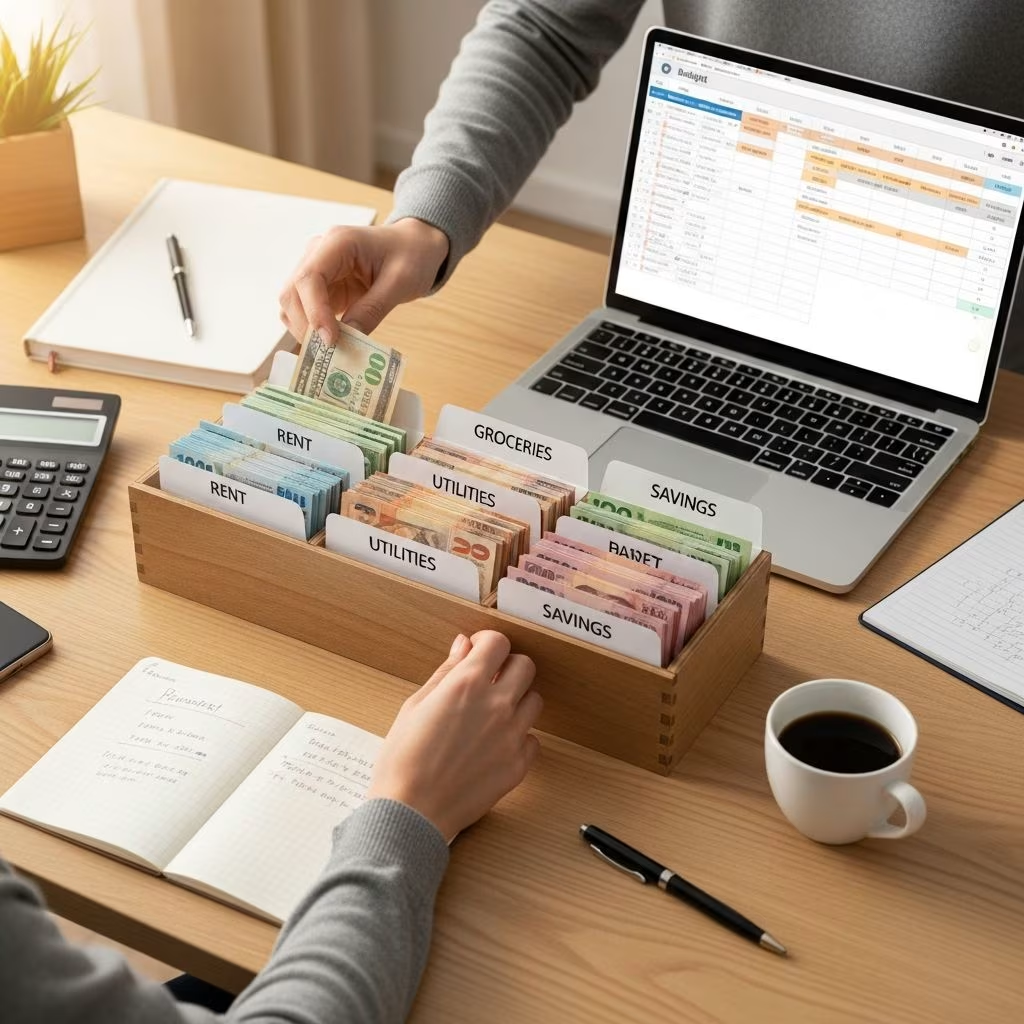
The cash envelope budgeting system offers a straightforward way to manage money by dividing cash into designated categories, ensuring you spend only what you’ve allocated for each purpose. This tactile approach fosters mindfulness and discipline in daily finances.
Understanding the Fundamentals of Envelope Budgeting
At its core, envelope budgeting involves separating your income into physical or virtual envelopes, each labeled for specific spending areas like food, transportation, or entertainment. Once the cash in an envelope is depleted, spending in that category halts until the next funding cycle, typically monthly or per paycheck.
This method traces back to traditional cash-based economies but has evolved with digital tools. It emphasizes assigning every dollar a job, aligning with zero-sum budgeting principles where income minus expenses equals zero. By handling physical money, users experience a stronger sense of loss when spending, reducing impulsive purchases.
Why Envelope Budgeting Stands Out in Modern Finance
In an era dominated by digital payments, envelope budgeting counters the disconnection from spending that cards create. Studies and user reports indicate cash users spend less overall due to the psychological weight of handing over tangible bills.
It particularly excels for variable expenses—those fluctuating costs like groceries or dining out—while fixed bills like rent can be tracked separately or auto-paid from a primary account. This hybrid approach accommodates real-life needs without rigid constraints.
Step-by-Step Guide to Implementing Your Envelope System
Setting up requires minimal tools: envelopes, a pen, and cash. Here’s a structured process to launch effectively.
- Assess Your Income: Calculate total monthly take-home pay from all sources, including salary, gigs, or investments.
- Track Past Spending: Review 2-3 months of bank statements to identify patterns in variable expenses.
- Define Categories: Group expenses logically—broad (e.g., ‘Food’) or detailed (e.g., ‘Groceries’ and ‘Dining Out’).
- Allocate Funds: Divide income proportionally, prioritizing needs (50%), wants (30%), and savings/debt (20%) as a starting framework.
- Stuff the Envelopes: Withdraw cash post-payday and fill each envelope with its assigned amount.
- Spend Mindfully: Use only envelope cash for category purchases; track remaining balances on the envelope.
- Review and Adjust: At cycle end, roll over leftovers to savings or tweak allocations based on reality.
Example Monthly Allocation Table
| Category | Allocated Amount | % of $3,500 Income |
|---|---|---|
| Essentials (Rent, Utilities) | $1,400 | 40% |
| Groceries | $500 | 14% |
| Transportation | $300 | 9% |
| Entertainment | $350 | 10% |
| Savings/Debt | $950 | 27% |
This table illustrates a balanced split for a $3,500 monthly income, adaptable to individual circumstances.
Customizing Categories for Your Lifestyle
Tailor envelopes to your unique needs. Families might include ‘Kids’ Activities’ or ‘School Supplies,’ while singles could prioritize ‘Fitness’ or ‘Hobbies’. For irregular costs like car repairs, calculate annual totals and divide monthly into a dedicated envelope.
- Needs: Housing, food staples, bills—non-negotiable basics.
- Wants: Leisure, subscriptions, gifts—flexible fun.
- Future-Focused: Emergency fund, vacations, retirement—build wealth proactively.
Start with 8-12 categories to avoid overwhelm, consolidating as habits form.
Digital Adaptations for the Tech-Savvy
Not keen on carrying cash? Digital envelopes replicate the system via apps like YNAB (You Need A Budget) or Monarch Money, using virtual categories and bank syncs. Software like Actual Budget incorporates fixed expenses seamlessly, ensuring a holistic view.
Multiple bank accounts can mimic envelopes: one for groceries, another for gas. Track via spreadsheets for free customization. These tools provide reports, alerts, and automation while preserving the discipline of limits.
Key Advantages That Drive Financial Success
Users report transformative results:
- Overspending Prevention: Empty envelopes enforce hard stops, dodging fees and debt.
- Heightened Awareness: Visual, touchable cash builds emotional ties to money.
- Surplus Generation: Unused funds fuel savings or debt payoff.
- Budget Refinement: Real data reveals true costs, refining future plans.
It’s especially empowering for beginners or those rebuilding after financial setbacks.
Navigating Common Hurdles
Challenges exist, but solutions abound.
| Challenge | Solution |
|---|---|
| Security risks with cash | Use a secure wallet or home safe; opt for digital for high amounts |
| Forgetting envelopes | Track digitally alongside; build routine reminders |
| Unexpected expenses | Maintain a flexible ‘Miscellaneous’ envelope; adjust promptly |
| Fixed bill integration | Auto-pay from checking, envelope only variables |
Discipline wanes initially, but consistency yields habits within weeks.
Real-World Success Stories and Tips
Many regain control: one user slashed dining out by 60% after visualizing coffee costs. Another cleared $10,000 debt by prioritizing envelopes. Pro tips include weekly check-ins, family involvement for shared budgets, and celebrating milestones with non-cash rewards.
For older adults, it simplifies fixed incomes, preventing shortfalls. Couples benefit from transparent allocation, reducing disputes.
Integrating with Broader Financial Strategies
Pair envelopes with zero-based budgeting: assign 100% of income. Combine with emergency funds (3-6 months expenses) in a separate ‘untouchable’ envelope. Track progress toward goals like homeownership via dedicated long-term envelopes.
Frequently Asked Questions
What if an envelope empties early?
Hold off spending or borrow from another, then rebalance next cycle to reflect true needs.
Is it safe to carry cash?
Minimize amounts; use digital for safety while keeping the mindset.
How often to refill?
Align with paychecks—biweekly for steadiness.
Does it work for high earners?
Yes, scale allocations; focus envelopes on discretionary spend.
Can businesses use it?
Adapted versions aid small ops for expense control.
Long-Term Impact on Wealth Building
Consistent use cultivates habits leading to wealth. Users often double savings rates within a year by curbing leaks. It instills intentionality, turning reactive spenders into proactive planners. As finances stabilize, expand to investments or philanthropy envelopes.
Envelope budgeting isn’t flawless but shines for tangibility. Evolve it as life changes—key is persistence.
References
- What Is the Cash Stuffing Envelope Budget System? — NerdWallet. 2023-10-15. https://www.nerdwallet.com/finance/learn/envelope-system
- Envelope system — Wikipedia. 2024-01-20. https://en.wikipedia.org/wiki/Envelope_system
- How to Use the Envelope Budget System — Capital One. 2024-05-12. https://www.capitalone.com/learn-grow/money-management/envelope-budget-system/
- Envelope budgeting — Actual Budget. 2023-11-08. https://actualbudget.org/docs/getting-started/envelope-budgeting/
- How to Use the Envelope Budget System: A Guide for Older Adults — National Council on Aging. 2024-02-14. https://www.ncoa.org/article/how-to-use-the-envelope-budget-system-a-guide-for-older-adults/
- Dave Ramsey’s Envelope System Explained — Debt.org. 2023-09-22. https://www.debt.org/advice/dave-ramseys-envelope-system-explained/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


