

What Is a Collateralized Debt Obligation (CDO)?
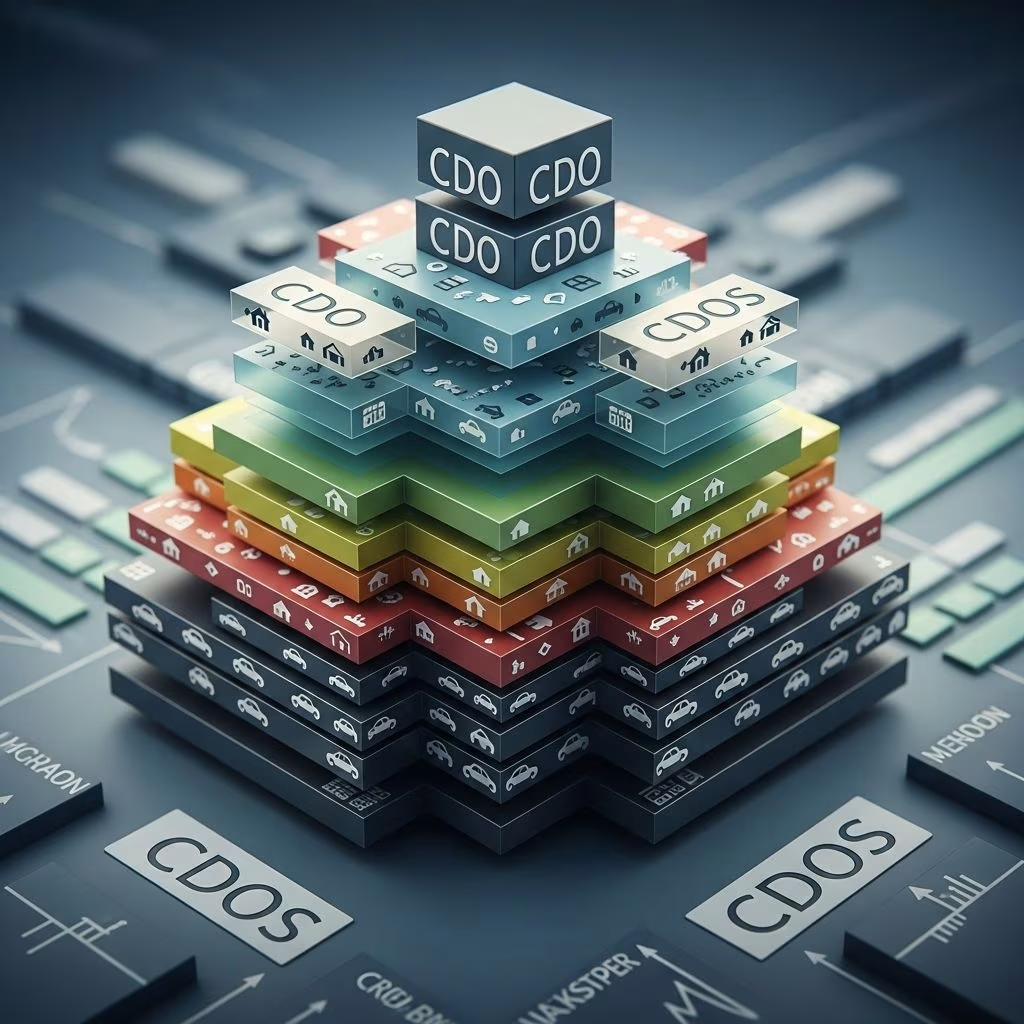
A Collateralized Debt Obligation (CDO) is a type of structured financial product that pools together cash-generating assets such as mortgages, bonds, and loans, and then repackages them into tranches that can be sold to investors. CDOs are created by financial institutions that acquire debt obligations from various sources, bundle them together, and sell shares of the resulting cash flows to investors. The underlying assets are collateral for the security, which is why these instruments are called collateralized debt obligations.
The primary purpose of CDOs is to transfer the credit risk associated with debt instruments from the original lender to investors who purchase the CDO securities. This process, known as securitization, allows financial institutions to free up capital and reduce their exposure to credit risk while generating fees from the structuring and sale of these complex instruments.
How CDOs Work: The Mechanics
Understanding how CDOs function requires examining the process from inception to distribution:
The Securitization Process
CDOs are created through a multi-step securitization process. First, a financial institution originates or acquires various debt obligations. These debt instruments are then transferred to a special purpose vehicle (SPV), which is a legal entity created specifically to hold these assets. The SPV then issues securities backed by the cash flows generated from the underlying debt obligations.
The cash flows from the underlying assets are distributed to investors in a hierarchical structure. Senior tranches receive priority in payment, followed by mezzanine tranches, and finally equity tranches. This waterfall structure means that senior investors are paid first, reducing their risk exposure compared to junior investors.
Tranche Structure
CDOs are divided into multiple tiers or tranches, each representing a different level of risk and return:
- Senior Tranches: These receive the highest priority for payment and typically carry the lowest risk and lowest yields. They are often rated AAA or equivalent by credit rating agencies.
- Mezzanine Tranches: These occupy the middle tier, receiving payments after senior tranches are satisfied. They carry moderate risk and moderate yields, typically rated between A and BBB.
- Equity Tranches: These are the first to absorb losses and the last to receive payments. They carry the highest risk but offer the highest potential returns. These tranches are often unrated or rated below investment grade.
Types of Collateralized Debt Obligations
CDOs come in several varieties, each structured around different types of underlying assets:
Mortgage-Backed CDOs
Mortgage-backed CDOs are constructed from pools of residential or commercial mortgages. These were extremely popular in the years leading up to the 2008 financial crisis. The underlying mortgages generate cash flows through monthly payments from borrowers, which are then distributed to CDO investors according to the tranche structure.
Bond-Backed CDOs
Bond-backed CDOs pool together corporate bonds, government bonds, or other fixed-income securities. These CDOs generate returns through coupon payments from the underlying bonds.
Loan-Based CDOs
Loan-based CDOs, also known as CLOs (Collateralized Loan Obligations), are backed by pools of commercial loans or bank loans. These are often used to bundle syndicated bank loans into tradeable securities.
CDOs Squared
CDOs squared are securities created from pools of other CDOs rather than original debt obligations. They represent a further layer of complexity and were particularly prevalent during the pre-crisis mortgage boom.
Advantages of CDOs
Despite their association with the financial crisis, CDOs offered several theoretical and practical advantages:
- Risk Distribution: CDOs distribute credit risk across multiple investors, reducing the concentration of risk in any single institution.
- Capital Efficiency: Banks and other financial institutions can originate loans and immediately sell them, freeing up capital to originate additional loans.
- Investment Opportunities: CDOs create investment opportunities for investors seeking specific risk-return profiles that might not be available through direct debt ownership.
- Liquidity Enhancement: By converting illiquid debt obligations into tradeable securities, CDOs enhance the liquidity of the underlying assets.
- Access to Markets: CDOs allow smaller financial institutions to access capital markets and diversify their funding sources.
Disadvantages and Risks Associated with CDOs
CDOs carry significant risks that contributed substantially to the 2008 financial crisis:
Complexity and Opacity
CDOs are extremely complex financial instruments that many investors and even financial professionals fail to fully understand. The layered structure, especially in CDOs squared, makes it difficult to assess the true risks inherent in these securities.
Credit Risk Concentration
While CDOs are designed to distribute risk, they often concentrate credit risk in specific geographic regions or asset classes. For example, mortgage-backed CDOs created significant exposure to residential real estate markets.
Rating Agency Failures
Credit rating agencies assigned AAA ratings to many CDOs that subsequently defaulted. These ratings failures were attributed to conflicts of interest, inadequate models, and insufficient due diligence.
Information Asymmetry
Investors often lacked complete information about the underlying assets in CDOs. The originators of the underlying debt had superior information but were incentivized to minimize standards and maximize origination volume through the moral hazard created by the ability to immediately sell the loans.
Systemic Risk
The interconnectedness of financial institutions through CDO holdings created systemic risk. When housing prices declined and mortgage defaults increased, the entire financial system faced potential collapse.
Leverage and Interconnectedness
Many financial institutions used leverage to amplify their returns on CDO investments, increasing their exposure to losses when values declined. Additionally, the interconnected nature of financial institutions meant that losses at one institution threatened the stability of the entire system.
CDOs and the 2008 Financial Crisis
CDOs played a central role in the 2008 financial crisis. The combination of lax lending standards, inadequate credit underwriting, rising housing prices, and the complexity of CDO structures created a perfect storm:
- Mortgage lenders, knowing they could immediately sell loans into the secondary market through CDO securitization, reduced lending standards dramatically.
- Subprime mortgages were bundled into CDOs and tranched in ways that obscured the underlying credit quality.
- Rating agencies assigned investment-grade ratings to securities backed by subprime mortgages.
- Banks and other financial institutions became deeply exposed to housing market declines through their CDO holdings.
- When housing prices declined and mortgage defaults increased, the values of CDOs collapsed, threatening the solvency of many financial institutions.
- The interconnectedness of financial institutions meant that the decline of one institution threatened to cause a cascade of failures throughout the financial system.
CDOs Since the Financial Crisis
Following the 2008 financial crisis, regulatory reforms and market skepticism significantly reduced the issuance of CDOs. However, the market for structured finance products has gradually recovered. Modern CDOs are subject to stricter regulatory oversight, including:
- The Dodd-Frank Act’s requirement that originators retain a minimum of 5% of the credit risk in securitized assets
- Enhanced disclosure requirements for structured finance products
- Higher capital requirements for banks holding significant amounts of structured finance securities
- Improved due diligence standards and risk management practices
Despite these reforms, CDOs remain controversial and are viewed with suspicion by many market participants and regulators. The market for new CDO issuance remains considerably smaller than it was before the financial crisis.
Key Differences Between CDOs and Other Securities
| Feature | CDO | Mortgage-Backed Security (MBS) | Bond |
|---|---|---|---|
| Underlying Assets | Multiple types of debt obligations | Residential mortgages | Issuer’s creditworthiness |
| Complexity | Highly complex with multiple tranches | Moderately complex | Simple and straightforward |
| Risk Profile | Varies by tranche; can include significant credit risk | Prepayment and credit risk | Primarily issuer default risk |
| Transparency | Limited transparency into underlying assets | Better transparency | High transparency |
| Liquidity | Often illiquid, especially lower tranches | Generally more liquid than CDOs | Highly liquid for major issuers |
Frequently Asked Questions
Q: What does a CDO stand for?
A: CDO stands for Collateralized Debt Obligation. It is a type of structured financial product that pools together cash-generating assets and repackages them into tradeable securities.
Q: Why were CDOs so important in causing the 2008 financial crisis?
A: CDOs played a critical role because they allowed banks to originate subprime mortgages and immediately sell them, removing the incentive to ensure borrower creditworthiness. The complexity of CDOs obscured underlying credit quality, and rating agencies failed to properly assess risks.
Q: What is the difference between a CDO and a mortgage-backed security?
A: While mortgage-backed securities (MBS) are specifically backed by pools of mortgages, CDOs can be backed by various types of debt obligations including mortgages, bonds, and loans. CDOs are also typically more complex with multiple layers of securitization.
Q: Are CDOs still used today?
A: Yes, CDOs are still used today, but in significantly smaller volumes than before the 2008 financial crisis. Modern CDOs are subject to stricter regulatory requirements and more rigorous risk management practices.
Q: How do CDO tranches differ in terms of risk and return?
A: Senior tranches have priority in receiving payments and carry lower risk but lower returns. Equity tranches are paid last and absorb losses first, carrying the highest risk but offering the highest potential returns. Mezzanine tranches occupy the middle ground.
Q: What is a CDO squared?
A: A CDO squared is a CDO that is backed by a pool of other CDOs rather than original debt obligations. This represents an additional layer of complexity and increased risk.
Q: How did rating agency failures contribute to the CDO crisis?
A: Rating agencies assigned AAA ratings to many CDOs backed by subprime mortgages. These failures resulted from conflicts of interest, inadequate risk assessment models, and insufficient due diligence in evaluating the quality of underlying assets.
References
- Dodd-Frank Wall Street Reform and Consumer Protection Act — U.S. Congress. 2010. https://www.congress.gov/111/plaws/publ203/PLAW-111publ203.pdf
- The Role of Credit Rating Agencies in the Structured Finance Market — U.S. Securities and Exchange Commission. 2008. https://www.sec.gov/cgi-bin/viewer?action=view&coll_id=1001&doc_id=5627&sort_type=DATE_A&count=40&search_text=credit%20rating%20agencies
- Financial Crisis Inquiry Commission Report — U.S. Government Printing Office. 2011. https://www.govinfo.gov/content/pkg/GPO-FCIC/pdf/GPO-FCIC.pdf
- Securitization and Structured Finance — Federal Reserve Board. 2014. https://www.federalreserve.gov/econresdata/feds/2014/files/201428pap.pdf
- The Evolution of the Structured Finance Market Since the Financial Crisis — Bank for International Settlements. 2016. https://www.bis.org/publ/qtrpdf/r_qt1606g.pdf
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


