

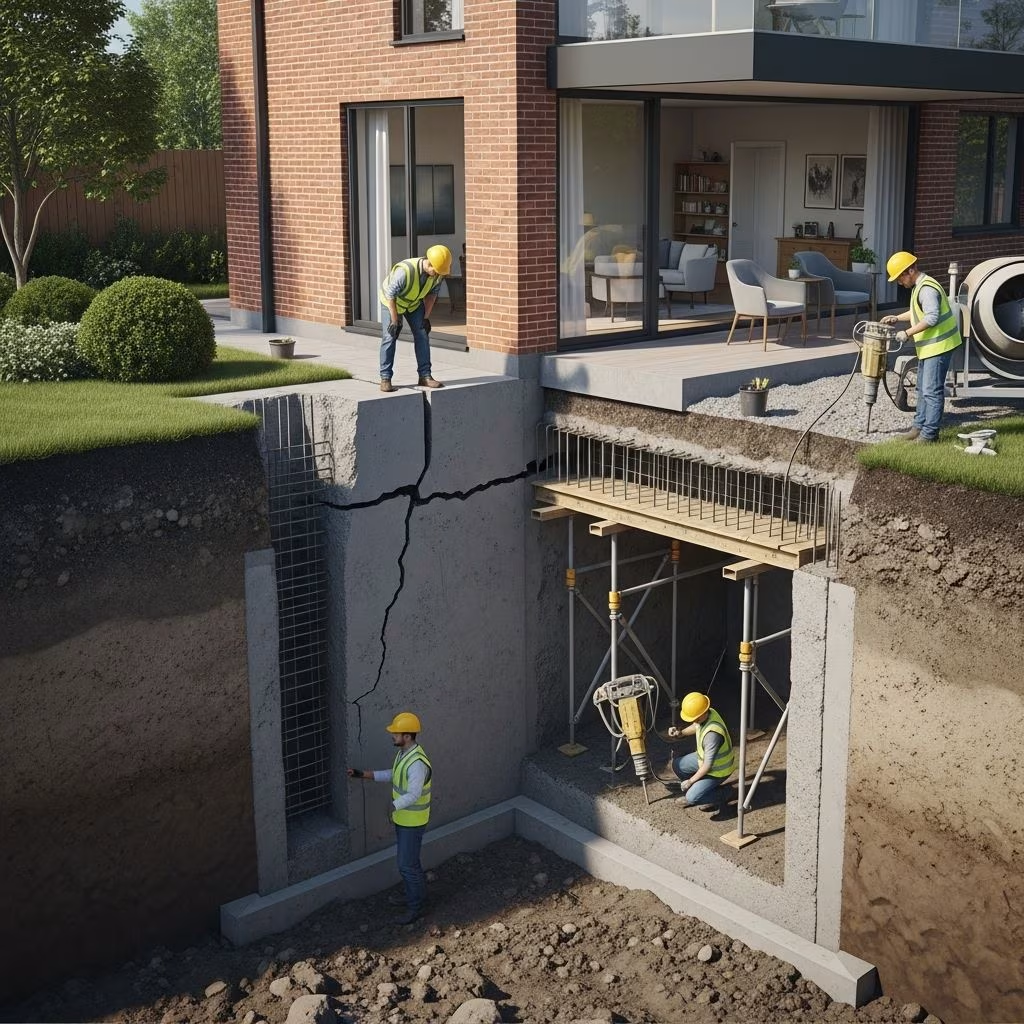
Your home’s foundation is its backbone, bearing the weight of the entire structure. When cracks appear or shifts occur, the question arises: does homeowners insurance step in to cover the hefty repair bills? Standard policies often provide protection against sudden, unexpected events but leave out gradual deterioration or specific disasters.
Understanding Coverage Basics for Structural Damage
Dwelling coverage in most homeowners policies protects the home’s physical structure, including the foundation, from listed perils. These typically encompass fire, lightning, explosions, windstorms, hail, and damage from falling objects or vehicles. For instance, if a tree topples during a storm and cracks the foundation, your insurer may reimburse repair costs up to policy limits, minus your deductible.
However, coverage hinges on the cause being a named peril and the event being sudden. Policies exclude maintenance issues, as homeowners must upkeep their property. Review your declarations page to confirm specifics, as variations exist between insurers like Progressive or Nationwide.
Common Perils That Trigger Foundation Coverage
- Fire and Smoke: Intense heat can warp or crack concrete foundations.
- Wind and Hail: Severe storms may hurl debris, impacting slabs or basements.
- Vandalism or Impact: A car crashing into your garage could damage supporting walls.
- Weight of Ice or Snow: Heavy accumulations might stress and fracture foundations in cold climates.
- Sudden Plumbing Leaks: Burst pipes causing soil erosion under the foundation may qualify.
These events align with “all-risk” or open-peril policies, where anything not explicitly excluded is covered. Always document damage immediately with photos to support claims.
Exclusions: When Insurance Won’t Pay
Most foundation problems stem from non-covered causes, leading to out-of-pocket expenses. Standard policies omit:
| Exclusion | Description | Typical Cost Impact |
|---|---|---|
| Wear and Tear | Cracks from aging concrete or normal settling | $2,000–$10,000 |
| Soil Movement | Shifting earth, expansion/contraction due to moisture | $5,000–$30,000 |
| Flooding | Water inundation from rivers or heavy rain | Up to $100,000 |
| Earthquakes | Seismic shifts cracking slabs | $10,000–$50,000 |
| Faulty Workmanship | Poor initial construction or renovations | $3,000–$20,000 |
| Neglect | Ignored maintenance like poor drainage | Variable, escalates quickly |
Flood and earthquake damages require separate policies; for example, FEMA’s National Flood Insurance Program covers certain foundation issues but not soil shifts. Water backups from sewers often need an endorsement.
Average Costs and Financial Implications
Foundation repairs average $2,188 to $7,884, but severe cases like full slab replacement can exceed $100,000. Costs vary by type:
- Crack injection: $500–$4,000
- Piering/underpinning: $10,000–$30,000
- Wall bowing fixes: $4,000–$15,000
Without insurance, options include home equity loans, personal loans, or contractor financing. Delaying repairs risks further damage, potentially halving home value and complicating sales.
Spotting Early Warning Signs
Proactive detection prevents escalation. Look for:
- Horizontal or wide vertical cracks in walls
- Doors/windows sticking or uneven floors
- Bulging walls or separation from framing
- Water pooling near the base or damp basement
- Sagging rooflines or chimney cracks
Schedule annual inspections, especially after heavy rains or droughts, which exacerbate soil issues. Proper grading—sloping soil 6 inches over 10 feet away from the house—diverts water effectively.
Step-by-Step Guide to Filing a Claim
- Assess Safely: Inspect without entering unstable areas; call professionals if severe.
- Notify Insurer: Report within 24–48 hours via app, phone, or agent.
- Document Everything: Photos, videos, timestamps; note weather conditions.
- Mitigate Damage: Tarp leaks or brace temporarily; save receipts.
- Get Quotes: From 2–3 licensed contractors for adjuster review.
- Adjuster Visit: Cooperate fully; they determine coverage.
- Receive Payout: Minus deductible; may go to lender if mortgaged.
Claims can raise premiums 7–20%, so weigh necessity.
Enhancing Protection with Add-Ons
Bridge gaps in standard coverage:
- Flood Insurance: Via NFIP or private carriers for water-related foundation harm.
- Earthquake Endorsement: Covers seismic retrofits to code.
- Water Backup: Protects against sewer overflows eroding soil.
- Service Line Coverage: For underground pipe breaks shifting foundations.
Bundle policies for discounts; compare quotes annually. Pre-purchase inspections reveal issues before closing.
Prevention Strategies for Long-Term Stability
Minimize risks through maintenance:
- Install French drains or gutters to manage runoff.
- Trim trees to prevent root intrusion.
- Ensure stable soil moisture with soaker hoses in dry areas.
- Re-level soil annually and seal cracks promptly.
- Monitor sump pumps and clean gutters seasonally.
These steps preserve warranty eligibility and avoid neglect claims.
FAQs
Will insurance cover small foundation cracks?
Usually no, if from settling; yes, if from a covered peril like hail.
Does renters insurance cover foundations?
No, it protects personal property; landlords handle structural issues.
How long does a foundation claim take?
30–60 days, depending on adjuster scheduling and contractor work.
Can I repair first and claim later?
Check policy; immediate fixes to prevent worsening are often allowed with receipts.
What if damage is partial?
Coverage prorates based on extent; partial repairs may still apply.
Foundation integrity affects safety and equity. Consult your agent for personalized advice, and act swiftly on issues to protect your investment.
References
- Does Homeowners Insurance Cover Foundation Repair? — Airlift Concrete Experts. 2023. https://airliftconcreteexperts.com/does-homeowners-insurance-cover-foundation-repair/
- Does Homeowners Insurance Cover Foundation Repair? — Experian. 2024-01-15. https://www.experian.com/blogs/ask-experian/does-homeowners-insurnace-cover-foundation-repair/
- Does Homeowners Insurance Cover Foundation Repair? — Bankrate. 2025-02-10. https://www.bankrate.com/insurance/homeowners-insurance/does-homeowners-insurance-cover-foundation-repair/
- Does Home Insurance Cover Foundation Repairs? — Progressive. 2024-11-05. https://www.progressive.com/answers/does-home-insurance-cover-foundation/
- Does Homeowners Insurance Cover Foundation Repair? — Nationwide. 2024. https://www.nationwide.com/lc/resources/home/articles/does-homeowners-insurance-cover-foundation-repair
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


