

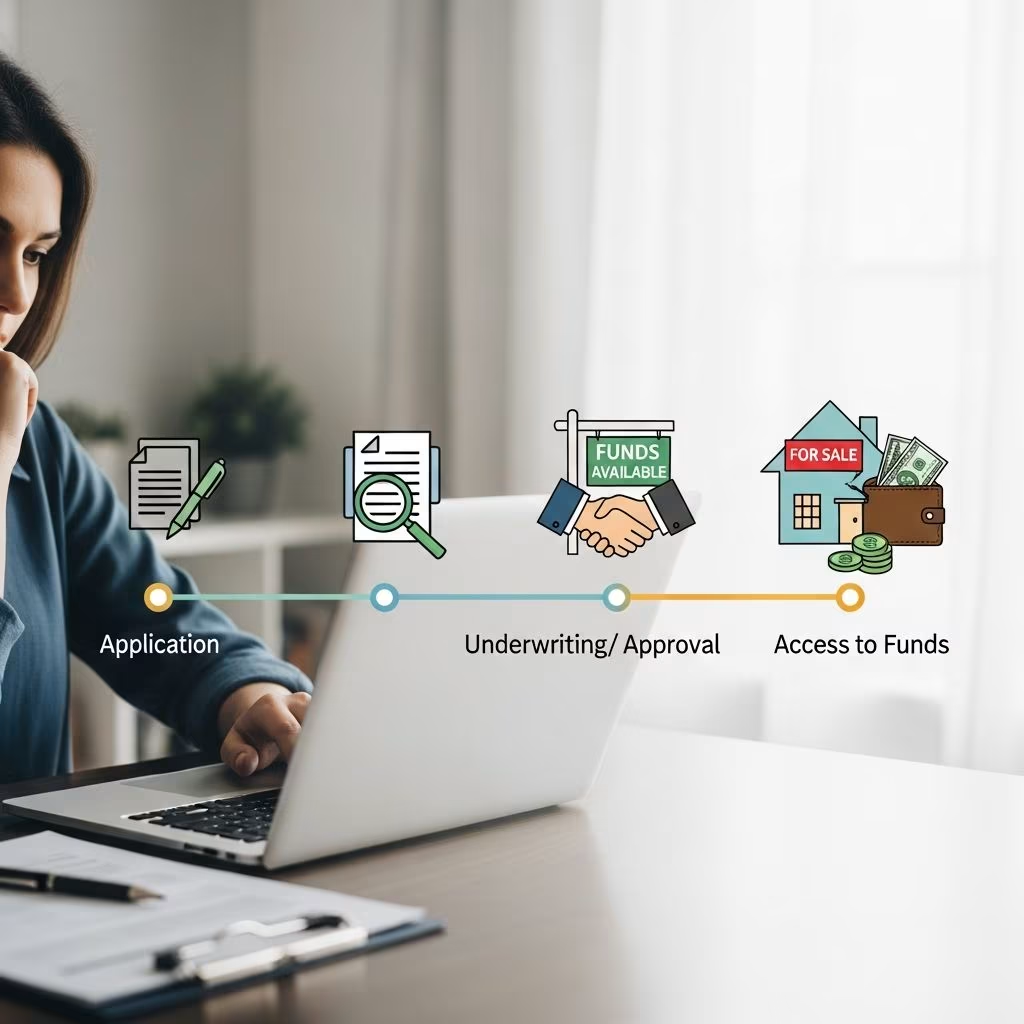
A Home Equity Line of Credit (HELOC) provides homeowners with flexible access to funds by leveraging the equity built in their property. Unlike traditional loans, a HELOC functions as a revolving credit line, secured by the home, allowing borrowers to draw funds as needed during a specific period. Understanding the timeline from application to first withdrawal is crucial for planning renovations, debt consolidation, or other major expenses. This guide breaks down each phase, average durations, and influences on processing speed.
Building Your Home Equity Foundation
Equity represents the portion of your home’s value that you own outright, calculated as current market value minus outstanding mortgage balance. For instance, a $400,000 home with a $200,000 mortgage yields $200,000 in equity. Lenders typically allow borrowing up to 80-95% of this equity, depending on creditworthiness and property type.
To qualify, homeowners need sufficient equity—often at least 15-20% after accounting for the new credit line. Rising property values and mortgage principal payments naturally increase equity over time, making HELOCs viable after several years of homeownership. Recent market trends show average HELOC limits ranging from $10,000 to $500,000, influenced by home appraisal and debt-to-income ratios.
Phase 1: Preparing and Submitting Your Application
The journey begins with gathering documents and choosing a lender. Preparation typically takes 1-3 days for organized applicants.
- Financial Documents: Recent pay stubs, tax returns (two years), W-2s or 1099s, and bank statements.
- Property Details: Deed, current mortgage statement, and homeowners insurance proof.
- Credit Profile: Lenders pull credit reports; aim for scores above 680 for best rates.
Online applications streamline this, often pre-qualifying in minutes via soft credit checks. Full submissions trigger hard inquiries, potentially dipping scores by 5-10 points temporarily. Expect initial lender response within 24-48 hours, with pre-approval offers outlining estimated limits and rates.
Phase 2: Underwriting and Property Evaluation
Post-submission, underwriting assesses risk, lasting 2-6 weeks. Key steps include:
| Step | Duration | Description |
|---|---|---|
| Credit Review | 1-3 days | Deep dive into debt-to-income (DTI below 43% ideal), payment history, and credit utilization. |
| Income Verification | 3-7 days | Confirmation of stable employment and income sources. |
| Home Appraisal | 7-14 days | Professional valuation to confirm equity; costs $300-$500, often lender-paid. |
| Title Search | 3-5 days | Ensures clear property ownership without liens. |
Variable rates, tied to the prime rate, make HELOCs sensitive to economic shifts, but fixed-rate options may extend this phase slightly.
Phase 3: Conditional Approval and Closing
Conditional approval arrives 10-30 days post-application, outlining terms like draw period (5-10 years) and repayment (10-20 years). Review and sign documents digitally or in-person within 3-5 days. Closing mirrors mortgage processes: notary, final disclosures, and funding instructions. This stage spans 3-7 days, with funds wired 1-3 days later.
Total timeline: 2-6 weeks for most, accelerating to 10-14 days with digital lenders or strong profiles. Delays arise from incomplete docs (20% of cases) or appraisal issues in volatile markets.
Activating Your HELOC: Draw and Repayment Mechanics
Once funded, enter the draw period: borrow via checks, cards, or transfers up to your limit, paying interest only on drawn amounts. Repayment follows, with principal plus interest. Navy Federal offers interest-only options, minimizing early payments.
- Draw Period: Flexible access, variable rates (currently lower than credit cards).
- Repayment Period: Fixed payments; balloon risks if not planned.
Factors Accelerating or Delaying Your HELOC
Several elements impact speed:
- Credit Strength: Scores 740+ yield faster approvals.
- Equity Levels: Higher cushions reduce scrutiny.
- Lender Type: Credit unions like Navy Federal skip closing costs, shaving days.
- Market Conditions: High demand lengthens queues.
- Documentation: Digital uploads cut weeks.
Pro tip: Shop multiple lenders; pre-approvals don’t hard-pull credit.
Strategic Uses and Financial Benefits
HELOCs shine for ongoing needs: education ($35k over years pays interest progressively), renovations, or debt consolidation at lower rates than cards. Tax-deductible interest (consult advisor) adds appeal for qualified improvements.
Risks and Mitigation Strategies
Your home secures the line; default risks foreclosure. Variable rates fluctuate, eroding equity if values dip. Counter with:
- Fixed-rate locks during draw periods.
- Budgeting for repayment hikes.
- Building emergency reserves.
Disciplined users avoid balance creep, preserving credit mix benefits.
Comparing HELOCs to Alternatives
| Option | Rate Type | Access Style | Best For |
|---|---|---|---|
| HELOC | Variable (fixed options) | Revolving | Ongoing needs |
| Home Equity Loan | Fixed | Lump sum | One-time expenses |
| Personal Loan | Fixed | Lump sum | Smaller amounts, unsecured |
HELOCs offer flexibility absent in lump-sum products.
Frequently Asked Questions
How long does it take to get a HELOC?
Typically 2-6 weeks, varying by lender and applicant readiness.
Can I get a HELOC with bad credit?
Possible but rates higher; minimum scores around 620.
Are there closing costs?
Often yes (1-5% of limit), but some waive like Navy Federal.
What if home values drop?
Equity shrinks; lenders may freeze lines.
Is HELOC interest tax-deductible?
Potentially for home improvements; verify with tax pro.
Steps to Expedite Your HELOC Process
- Check equity via online tools.
- Boost credit 3+ months prior.
- Compare 3-5 lenders.
- Prepare docs digitally.
- Opt for e-closing.
By anticipating phases, homeowners access equity efficiently, turning home value into actionable capital.
References
- Pros And Cons Of Home Equity Line Of Credit (HELOC) — Bankrate. 2024. https://www.bankrate.com/home-equity/pros-cons-of-home-equity-lines/
- What is a Home Equity Line of Credit and How Does it Work? — Bank of America. 2025. https://www.bankofamerica.com/mortgage/learn/what-is-a-home-equity-line-of-credit/
- What is a Home Equity Line of Credit? (HELOC) — Citizens Bank. 2025. https://www.citizensbank.com/learning/what-is-a-home-equity-line-of-credit.aspx
- Home Equity Loans and Home Equity Lines of Credit — Federal Trade Commission (FTC.gov). 2023-10-01. https://consumer.ftc.gov/node/78380
- Home Equity Line of Credit — LA County Department of Consumer and Business Affairs (dcba.lacounty.gov). 2024. https://dcba.lacounty.gov/portfolio/home-equity-line-of-credit/
- Home Equity Loan vs. Home Equity Line of Credit (HELOC) — Equifax. 2025. https://www.equifax.com/personal/education/loans/articles/-/learn/home-equity-loans-vs-home-equity-lines-of-credit/
- Home Equity Line of Credit (HELOC) & Today’s Rates — Navy Federal Credit Union. 2026-02-01. https://www.navyfederal.org/loans-cards/equity/heloc.html
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


