

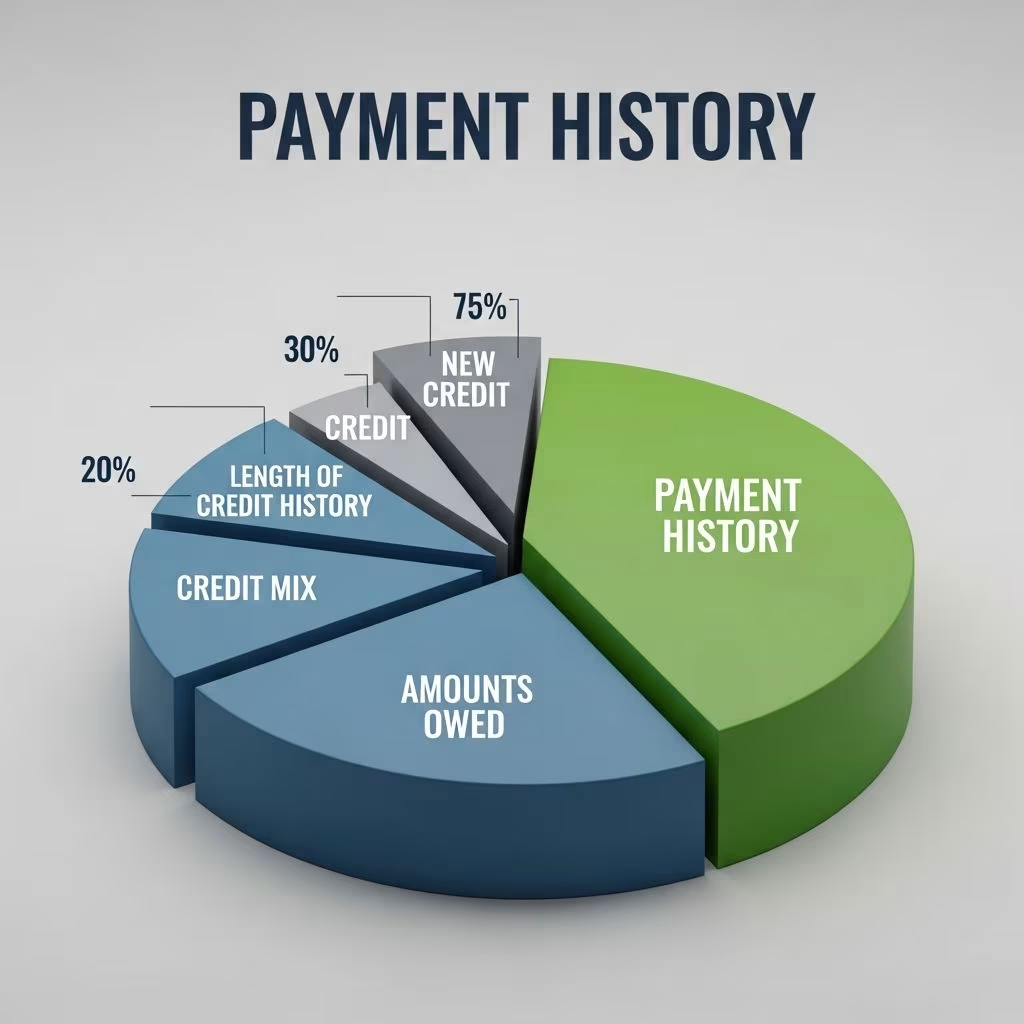
Your payment history is the cornerstone of your credit score, comprising 35% of your FICO score and serving as the strongest predictor of future repayment behavior. Lenders prioritize it because it reveals your reliability in meeting financial obligations over time. Even isolated late payments can harm your score, but consistent on-time payments build a robust profile that opens doors to better loans, lower rates, and financial flexibility.
What Is Payment History and Why Does It Matter So Much?
Payment history tracks how you’ve handled payments on credit accounts, including credit cards, retail accounts, installment loans, mortgages, and more. It includes details like payment timeliness, delinquency severity (e.g., 30, 60, or 90 days late), amounts owed on delinquent accounts, past-due items, bankruptcies, and collections. This data remains on your credit report, influencing scores from FICO and VantageScore models.
Accounting for 35% of FICO scores and up to 40% in some VantageScore versions, payment history outweighs other factors like amounts owed (30%) or credit age. Research confirms it’s the top predictor of default risk, making it lenders’ first review point. A strong history signals trustworthiness, while negatives like late payments—reported after 30 days—can drop scores significantly, with severity increasing over time (e.g., 90+ days late hurts more).
Positive aspects include the number of on-time accounts and time elapsed since issues. Bankruptcies linger 7-10 years, collections 7 years from delinquency, but their impact fades with age and positive behavior.
Common Payment History Red Flags That Hurt Your Score
- Late Payments: One 30-day late payment can slash scores by 60-110 points; multiple or severe delinquencies compound damage.
- Collections: Third-party collections stay 7 years from original delinquency; both original and collection accounts may appear.
- Bankruptcies: Chapter 7 lasts 10 years, Chapter 13 for 7 years from filing.
- Foreclosures and Repossessions: Treated as severe delinquencies, lingering 7 years.
- Public Records: Judgments, liens, and wage garnishments also factor in.
Even closed accounts contribute, and non-debt payments like rent/utilities rarely appear unless reported via services. However, autopay exclusions apply only to select accounts.
How Long Do Negative Marks Stay on Your Credit Report?
Negative information persists but loses punch over time:
| Item | Duration on Report |
|---|---|
| Late Payments/Delinqencies | 7 years from original delinquency date |
| Collections | 7 years from first delinquency |
| Chapter 7 Bankruptcy | 10 years from filing |
| Chapter 13 Bankruptcy | 7 years from filing |
| Foreclosure | 7 years |
Older negatives impact less; consistent on-time payments dilute them. Check reports weekly for free via AnnualCreditReport.com.
Proven Strategies to Build a Strong Payment History
Improving payment history starts with prevention and proactive habits. Here’s how:
1. Set Up Autopay and Payment Alerts
Enroll in autopay for at least minimum payments on all accounts—many issuers offer it fee-free. Combine with email/SMS alerts 3-5 days before due dates to catch issues early. This eliminates forgetfulness, the top late-payment cause.
2. Organize Bills with a Payment Calendar
Use apps like Mint or a spreadsheet to track due dates, prioritizing by severity (e.g., mortgages first). Pay high-interest debts early to free cash flow.
3. Make More Than Minimum Payments When Possible
Minimums keep accounts current but accrue interest. Extra payments reduce balances, improving utilization (30% of score) alongside history.
4. Contact Creditors for Hardship Help
If struggling, call issuers immediately—before 30 days late. Options include forbearance, reduced rates, or modified plans. Nonprofits like NFCC provide free counseling.
Steps to Repair Existing Payment History Damage
You can’t erase accurate late payments, but mitigation works:
1. Get Current on Delinquent Accounts
Pay past-due balances fully; this stops further reporting and begins recovery. Scores rebound faster post-correction.
2. Dispute Errors on Your Credit Reports
Review Equifax, Experian, TransUnion reports for inaccuracies (e.g., wrong late dates). File disputes online—60% of reports have errors. Removals boost scores proportional to history strength.
3. Request Goodwill Adjustments
Politely write creditors explaining one-off lates (e.g., medical emergency), requesting removal. Success varies but works for good-standing customers.
4. Add Positive Accounts Strategically
Secured cards or credit-builder loans report payments, diluting negatives. Keep utilization under 30%.
Advanced Tactics for Long-Term Credit Recovery
Beyond basics:
- Become an Authorized User: On a family member’s perfect-history card (notify issuer for reporting).
- Use Experian Boost: Adds utility/rent payments for instant score lift (opt-in service).
- Monitor Progress: Free tools like CreditWise track changes without hard inquiries.
Average score recovery: 3-6 months of perfect payments yields 20-50 point gains; full rebound takes 1-2 years.
Which Bills Actually Count Toward Payment History?
- Credit cards (revolving)
- Retail/store cards
- Auto, student, personal loans (installment)
- Mortgages
- Consumer finance loans
- Closed accounts (positive/negative)
Exclusions: Rent, utilities, telecom (unless reported); payday loans rarely qualify. Focus on reportable debts.
Frequently Asked Questions (FAQs)
Q: Can one late payment ruin my credit?
A: No—a single 30-day late drops scores 60-100 points initially, but good history mitigates it. Impact fades over time with on-time payments.
Q: How soon after a late payment does it affect my score?
A: Reported after 30 days; appears on reports ~1 month later. Prevent by paying before day 21.
Q: Do paid collections hurt my score?
A: Yes, they stay 7 years, but paying reduces severity; focus on current payments.
Q: Can autopay fix past late payments?
A: No, but prevents future ones, accelerating recovery.
Q: How often should I check my credit reports?
A: Weekly for free; monthly for disputes. Monitor scores via free apps.
Final Thoughts on Mastering Payment History
Consistent on-time payments transform payment history from liability to asset, unlocking prime rates and opportunities. Start today: Autopay everything, dispute errors, and track progress. Your future self—and wallet—will thank you. (Word count: 1678)
References
- How Payment History Impacts Your Credit Score — myFICO. Accessed 2026. https://www.myfico.com/credit-education/credit-scores/payment-history
- What Affects Your Credit Scores? — Experian. Accessed 2026. https://www.experian.com/blogs/ask-experian/credit-education/score-basics/what-affects-your-credit-scores/
- How to Improve Your Payment History — Experian. 2025-07-18. https://www.experian.com/blogs/ask-experian/how-to-improve-payment-history/
- Payment History and How It Impacts Credit — Capital One. 2023-11-30. https://www.capitalone.com/learn-grow/money-management/payment-history/
- How long does information stay on my credit report? — Consumer Financial Protection Bureau. Accessed 2026. https://www.consumerfinance.gov/ask-cfpb/how-long-does-information-stay-on-my-credit-report-en-323/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


