

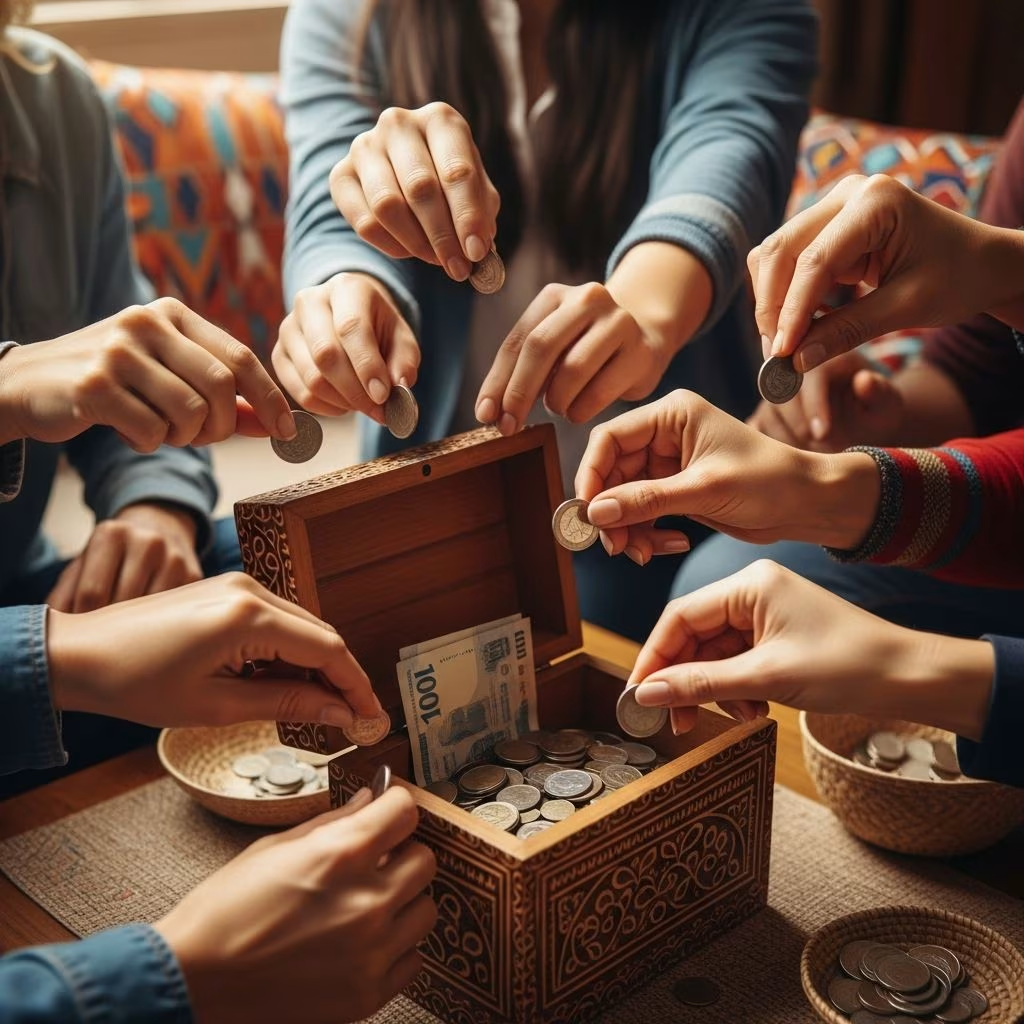
Saving money can feel lonely when you are doing it by yourself. If you struggle to stay consistent or motivated, a Susu (also called Sou-Sou, Esusu, Tontine, Ajo, or partner hand) offers a community-based way to build savings and access lump sums of cash.
This guide explains what a Susu is, how it works, its history and purpose, the pros and cons, and practical steps to decide if this savings method fits your life and goals.
What Is A Susu or Sou-Sou?
A Susu is a type of rotating savings and credit association (often shortened to ROSCA) where a group of people agree to contribute a fixed amount of money at regular intervals and take turns receiving the entire pooled amount.
Common features of a traditional Susu include:
- Group-based: Typically family members, friends, coworkers, or trusted members of a community.
- Fixed contribution: Everyone contributes the same agreed amount each cycle (weekly, bi-weekly, or monthly).
- Rotating payout: At each cycle, one member receives the full pot until everyone has had a turn.
- Informal agreement: Often built on trust and social ties rather than formal contracts.
In many African, Caribbean, Latin American, and Asian communities, Susu-style systems are used to fund:
- Weddings and major celebrations
- Funerals and related family obligations
- School fees and professional training
- Small business start-up or expansion costs
- Home repairs, large purchases, or emergency expenses
Economists classify Susu and similar systems as informal financial arrangements that help people save and borrow when access to banks or credit is limited.
The History and Origins of Susu
The concept of Susu is deeply rooted in West African culture. The word is often traced to the Yoruba term “Esusu”, which refers to collective savings schemes used by community members to pool resources and provide mutual financial support.
Similar systems exist across the world under different names, for example:
- Sou-Sou or Box hand in the Caribbean
- Tontine in parts of Francophone Africa and elsewhere
- Ajo or Esusu in Nigeria
- Partner in some Caribbean communities in the UK and North America
- ROSCA or Rotating Savings and Credit Association in academic literature
Historically, Susu systems allowed people to:
- Save without needing a formal bank account
- Access lump sums without applying for bank loans
- Rely on community relationships and reputation instead of credit scores
Research by the World Bank and other institutions notes that ROSCAs like Susu have been especially important for women, low-income workers, and migrants who face barriers in formal financial systems.
How Does A Susu Savings Work?
A Susu is a simple but structured system. Understanding the mechanics helps you decide if it is right for you.
Basic Structure
At its core, a Susu works as follows:
- The group decides how many people will participate.
- Members agree on a fixed contribution amount and frequency (e.g., $100 weekly).
- Each period, everyone contributes their share into a common pot.
- One member receives the entire pot for that period.
- The payout rotates every period until all members have received their lump sum once.
Example of a Susu Cycle
| Member | Contribution per week | Number of members | Total lump sum received | Week of payout |
|---|---|---|---|---|
| A | $100 | 5 | $500 | Week 1 |
| B | $100 | 5 | $500 | Week 2 |
| C | $100 | 5 | $500 | Week 3 |
| D | $100 | 5 | $500 | Week 4 |
| E | $100 | 5 | $500 | Week 5 |
Everyone contributes a total of $500 over five weeks, and everyone receives a $500 lump sum once. The main benefit is getting that money all at once when it is your turn, instead of gradually over time.
Key Decisions Every Susu Group Must Make
Before starting, group members should clearly agree on:
- Contribution amount – How much can everyone realistically afford each period?
- Frequency – Weekly, bi-weekly, or monthly contributions.
- Number of participants – This determines how long the cycle lasts.
- Order of payouts – Who gets the pot first, second, and so on.
- Start and end dates – When contributions begin and when the cycle is complete.
- Rules and consequences – What happens if someone pays late or stops paying.
Many groups also appoint a coordinator (sometimes called a banker or treasurer) to track contributions, manage payments, and communicate with participants.
Pros and Cons of Susu Savings
Susu systems can be powerful, but they also come with important risks. It is crucial to understand both sides.
Benefits of Joining a Susu
- Built-in accountability: Knowing others rely on your contribution can motivate you to save consistently.
- Access to lump sums: You can receive a large sum at once, which may be easier than saving the same amount on your own.
- Community support: Susu often strengthens relationships and mutual support within families and communities.
- No credit checks: Your access to the pot is based on membership, not on credit scores or collateral.
- Simple structure: No complex financial products, interest calculations, or paperwork.
- Culturally familiar: For many, Susu is a trusted, long-standing tradition passed down through generations.
Risks and Drawbacks of Susu
- No legal protection: In most countries, traditional Susu arrangements are informal. If someone stops paying or disappears with the money, you may have limited legal recourse.
- Risk of non-payment: If a member receives their payout early in the cycle and then stops contributing, others lose out.
- No interest earnings: Unlike savings accounts, you generally do not earn interest on your contributions.
- Liquidity risk: Your ability to access funds depends on when your turn comes up; this may not match emergencies or sudden needs.
- Potential for scams: Some people misuse the Susu label to run pyramid or gifting schemes that promise unrealistic returns; these are not traditional Susu systems and may be illegal in many jurisdictions.
How To Make A Susu Savings Approach Work For You
To use a Susu effectively and safely, approach it with the same care you would apply to any financial commitment.
1. Clarify Your Financial Goals
Start by deciding why you want to participate. Common goals include:
- Paying off a high-interest debt with a lump sum
- Funding a major purchase (appliances, furniture, a car down payment)
- Covering tuition, certification fees, or other education costs
- Building a small business inventory or equipment fund
- Creating a dedicated fund for annual expenses or family events
Knowing your goal helps you choose the right contribution amount and when during the cycle you want to receive the pot.
2. Pick the Right Contribution Amount
Your Susu contribution should fit comfortably within your budget. Before you join, carefully review:
- Your monthly income and essential expenses
- Existing debt payments
- Emergency savings (if any)
Only commit to an amount you can pay on time every single period, even if your schedule or income changes. Many central banks and financial education programs recommend ensuring that saving commitments do not crowd out essential needs like housing, food, and basic utilities.
3. Agree on Clear Rules and Documentation
Even if you are participating with close friends or relatives, it is wise to put the Susu terms in writing. Include:
- Names and contact details of all members
- Contribution amount and frequency
- Full payout schedule (who gets paid when)
- How contributions will be collected (cash, transfer, mobile payment)
- What happens if someone pays late or misses a payment
- What happens if a member needs to exit early
A simple written agreement or even a shared digital document can prevent misunderstandings later.
4. Stay Committed to the Process
The success of a Susu depends entirely on everyone staying committed. To stay on track:
- Set reminders for contribution dates.
- Automate transfers where possible.
- Adjust your budget to treat Susu contributions like a non-negotiable bill.
- Communicate early if you anticipate a delay and work with the group on a solution.
Consistency, honesty, and reliability help sustain the trust that Susu systems depend on.
Expert Tip: Be Mindful Of Who You Do A Susu With
Because Susu systems rely on trust, choosing the right group is crucial. To reduce risk, consider the following:
- Join people you know well – Long-term friends, close family, or coworkers you trust.
- Assess reliability – Have the members shown responsible behavior with money or other shared commitments?
- Beware of pressure – Avoid joining a group solely because of pressure from acquaintances or social media.
- Watch for red flags – Promises of high or “guaranteed” returns, complex rules you do not understand, or organizers who refuse transparency may signal a scam.
If you are new to Susu, you might prefer to start with a smaller group or a smaller contribution until you gain experience and confidence.
Frequently Asked Questions About Susu Savings
Who should participate in a Susu?
A Susu can be suitable for people who:
- Value community and shared responsibility
- Need access to a lump sum for a specific purpose
- Can reliably contribute the agreed amount each period
- Already have or are building a basic emergency fund through other means
It may not be a good fit if your income is highly unpredictable, you have difficulty meeting existing commitments, or you feel pressured to join.
Is Susu a good way to save money?
A Susu can be an effective savings tool for people who are motivated by social accountability and need structure to save regularly. However, it should not replace more secure financial tools such as insured savings accounts for long-term or emergency savings.
If you choose to use a Susu, consider balancing it with:
- A separate emergency fund in a bank or credit union
- Retirement savings in tax-advantaged accounts where available
- Debt repayment strategies for high-interest loans or credit cards
Is a Susu the same as a pyramid scheme?
No. A traditional Susu is a closed group of people contributing a fixed amount and taking turns receiving the pot. There is no profit promised, no recruitment-based rewards, and everyone gets back exactly what they put in, just at different times.
By contrast, pyramid and gifting schemes often:
- Require ongoing recruitment of new members
- Promise high or guaranteed returns
- Collapse when new participants stop joining
Regulators such as the U.S. Federal Trade Commission warn that such schemes are illegal and can cause serious losses for most participants.
What happens if someone in the Susu stops paying?
This is one of the biggest risks. If someone who has already received their lump sum stops contributing, later participants may not get the full amount they expect. That is why:
- Group selection and trust are vital.
- Written rules and expectations should be agreed before starting.
- Some groups require members who want an early payout to provide additional guarantees or collateral.
Is money in a Susu insured like a bank account?
No. Traditional Susu contributions are usually not protected by deposit insurance or government guarantees. In contrast, in countries like the United States, eligible deposits in banks and credit unions are insured by agencies such as the FDIC and NCUA up to specified limits.
Because of this, you should only commit money you can afford to risk and avoid very large Susu contributions unless the group is extremely reliable and transparent.
Can I participate in more than one Susu at a time?
Some people do, but this increases the strain on your budget and the risk of missing payments. If you join more than one Susu:
- Ensure your total contribution fits comfortably in your monthly cash flow.
- Stagger the payout dates so you are not overextended.
- Keep detailed records of each group’s rules and schedules.
Related Topics to Help You Save More
If you are exploring Susu because you want to strengthen your finances, you may also want to learn about:
- Creating and following a realistic budget
- Automating transfers to savings accounts
- Building an emergency fund in a safe, insured account
- Paying down high-interest debt systematically
- Setting clear money goals and timelines
Combining community-based tools like Susu with modern financial products can create a balanced approach that honors tradition while protecting your long-term security.
Give A Susu Savings A Try—Carefully
Now that you understand what a Susu is, how it works, and the potential benefits and risks, you can decide whether this saving method fits your goals, values, and financial situation.
A well-run Susu can:
- Provide structure and accountability
- Help you access a meaningful lump sum at the right moment
- Strengthen community ties and mutual support
At the same time, it is essential to:
- Choose trustworthy participants
- Put clear agreements in writing
- Understand that your contributions are not insured
- Use Susu as one part of a broader, diversified financial strategy
If traditional saving on your own has not worked well, and you have a reliable circle of people who share your commitment, a Susu could be a meaningful way to work together toward your financial goals.
References
- “Rotating Savings and Credit Associations (ROSCAs): The Origins of Financial Cooperation” — World Bank (Global Financial Development Report background, referencing informal finance and ROSCAs). 2014. https://openknowledge.worldbank.org/entities/publication/0a5b6390-f23c-5a2e-9f4f-7db15bf95df2
- “Esusu: The History of an African Financial Institution” — O. Y. Ogundiran (academic discussion of Yoruba esusu systems). 2007. https://doi.org/10.1353/jaf.2007.0004
- “Informal Finance in African Countries” — International Monetary Fund (occasional papers discussing informal savings groups, including ROSCAs). 1992. https://www.elibrary.imf.org/view/book/9781557751997/9781557751997.xml
- “Consumer Information: Pyramid Schemes” — U.S. Federal Trade Commission. 2019-10-01. https://www.ftc.gov/business-guidance/resources/pyramid-schemes
- “Deposit Insurance at a Glance” — Federal Deposit Insurance Corporation (FDIC). 2023-06-30. https://www.fdic.gov/resources/deposit-insurance
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


