

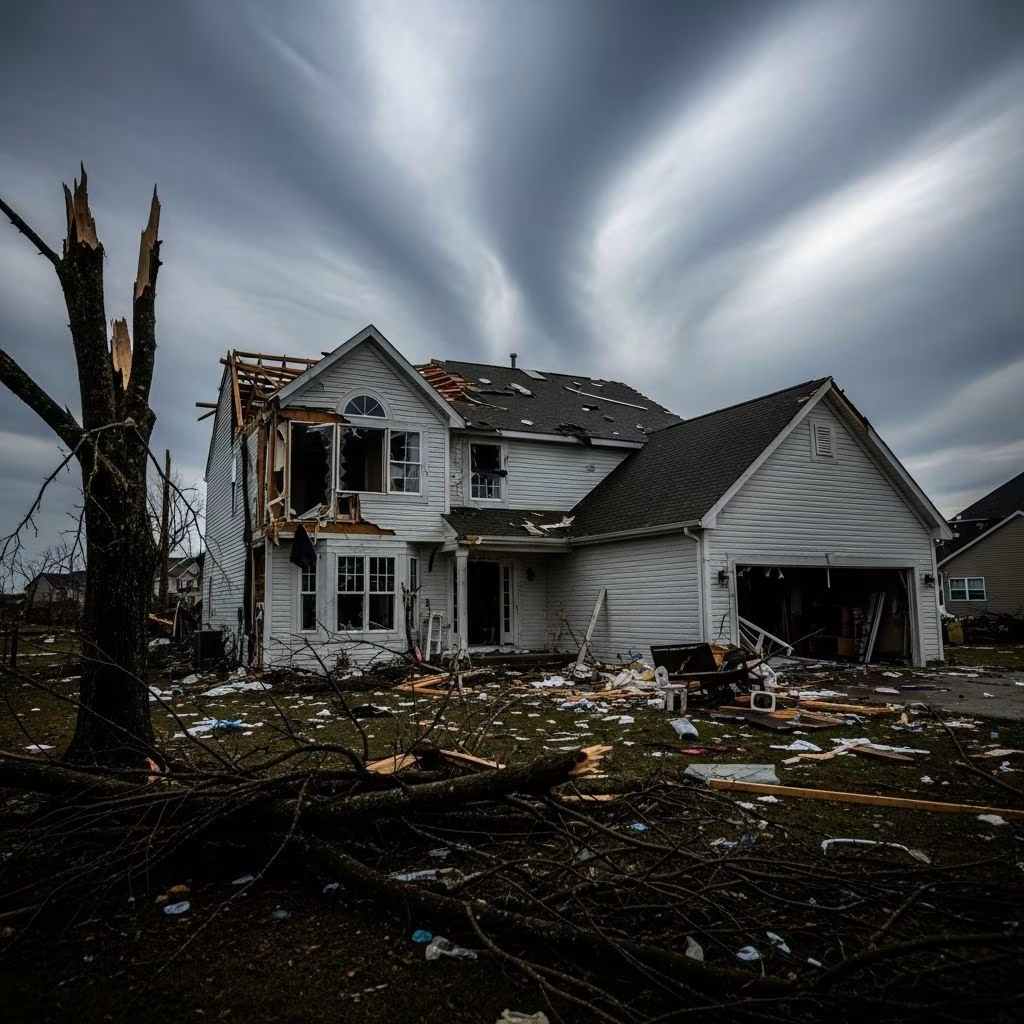
Standard homeowners insurance policies generally protect against tornado-related destruction caused by high winds, hail, and flying debris, covering repairs to your home, belongings, and temporary living costs if you’re displaced. However, coverage varies by location, policy terms, and specific exclusions like flooding or neglected maintenance.
Core Components of Tornado Coverage in Home Policies
Most policies treat tornadoes as a covered peril under windstorm protection, but high-risk areas often impose unique rules. Understanding the breakdown helps homeowners assess their protection levels accurately.
- Dwelling Protection: This pays for repairing or rebuilding the main house structure, including walls, roof, and foundations damaged by tornado forces, up to the policy limit.
- Detached Buildings: Coverage extends to garages, sheds, fences, and gazebos not connected to the home, ensuring outlying property isn’t overlooked.
- Belongings Inside: Furniture, appliances, clothing, and electronics qualify for replacement or repair if ruined by storm entry or direct impact.
- Temporary Relocation Aid: Funds hotel stays, meals, and laundry if your home becomes uninhabitable during recovery.
In practice, a tornado lifting your roof could trigger dwelling coverage for full replacement, while scattered personal items might fall under contents protection on either actual cash value or replacement cost basis, depending on your endorsement.
Common Exclusions and Limitations to Watch For
Not every tornado effect receives automatic payout. Insurers draw clear lines to manage risks, particularly in vulnerable regions.
| Potential Damage Type | Typically Covered? | Notes |
|---|---|---|
| Wind-driven structural harm | Yes | Subject to wind deductibles in prone areas. |
| Hail impacts | Yes | Often paired with wind deductibles. |
| Water intrusion from breached roof | Yes, if sudden | Not if from poor upkeep. |
| Ground flooding | No | Requires separate flood policy. |
| Fallen tree on home | Usually yes | No if tree was diseased/neglected. |
Wind exclusions appear in coastal or tornado alley policies, slashing standard coverage. Flooding from heavy rains accompanying twisters demands National Flood Insurance Program add-ons, as standard policies ignore ground-up water rise.
Navigating Deductibles in Tornado Claims
Storm-specific deductibles amplify costs in disaster zones, often 1-5% of dwelling value versus flat $1,000 all-peril types. A $300,000 home with 2% wind deductible means $6,000 out-of-pocket before benefits flow.
- Opting for lower percentages hikes premiums but eases claim burdens.
- Multiple deductibles may stack if hail and wind combine.
- Review annually, especially post-rate changes in high-risk states.
Claims process deducts this from repair estimates; for $20,000 damage, you’d cover the threshold, insurer the balance up to limits.
Handling Debris, Trees, and Secondary Impacts
Tornadoes scatter limbs, uproot trees, and hurl objects, complicating recovery. Policies often fund debris removal tied to covered structures, plus tree trimming if blocking access.
Tree falls qualify if storm-forced, not decay-related. Evidence like pre-storm photos proves neglect wasn’t yours. Car damage from debris might invoke comprehensive auto coverage separately.
Steps to File a Tornado Damage Claim Successfully
Act swiftly post-storm to maximize recovery odds. Delays risk further deterioration, weakening claims.
- Ensure Safety: Evacuate if unstable; document from afar initially.
- Photograph Everything: Capture exterior, interior, and item-specific harm before cleanup.
- Contact Insurer Promptly: Report within 24-48 hours; get claim number.
- Tarp and Secure: Mitigate extra damage like rain entry without full repairs.
- Gather Proof: Receipts, videos, neighbor statements bolster validity.
- Adjuster Visit: Cooperate fully; question estimates if low.
- Appeal if Needed: Hire public adjuster for disputes.
Average payouts cover 70-80% of verified costs after deductibles, per industry data.
Enhancing Protection in Tornado-Prone Regions
Baseline policies suffice for mild threats, but upgrades fortify against severe outbreaks. Consider these options:
- Windstorm Riders: Override exclusions in vulnerable spots.
- Extended Replacement Cost: 20-50% over dwelling limit for surge pricing.
- Ordinance/Law Coverage: Funds code upgrades post-rebuild.
- Flood Endorsement: Pairs with NFIP for comprehensive water defense.
Annual reviews align limits with home value appreciation; underinsurance slashes payouts proportionally.
Prevention Strategies to Minimize Tornado Losses
Proactive measures cut damage scale and claim denials for maintenance issues.
- Trim overhanging branches near rooflines.
- Install storm shutters or impact glass.
- Anchor heavy furniture and secure appliances.
- Build safe room per FEMA specs (P-320 guide).
- Inventory belongings yearly via app or video.
FEMA reports fortified homes suffer 50% less wind damage; safe rooms boost survival rates dramatically.
Regional Variations Across the U.S.
Tornado frequency shapes policy terms: Midwest ‘Tornado Alley’ mandates higher deductibles; Southeast adds hurricane overlaps. States like Texas, Oklahoma mandate wind pools for excluded risks.
Use tools like NOAA’s storm tracker for personalized risk profiles when shopping carriers.
Frequently Asked Questions
Does basic home insurance cover roof damage from a tornado?
Yes, if wind/hail caused it and no exclusions apply; expect actual cash value unless upgraded to replacement cost.
What if my policy has a wind exclusion?
Seek state FAIR plans or private windstorm insurers; premiums rise but coverage activates.
Is debris cleanup included?
Limited to $1,000-$5,000 typically for covered structures; trees blocking driveways qualify separately.
Can I claim for spoiled food after power outage?
Usually $500 limit under food spoilage endorsement; verify policy.
How much does adding tornado coverage cost?
Varies 10-30% premium bump in risk zones; shop quotes annually.
Key Takeaways for Homeowners
Verify wind inclusion, grasp deductibles, document meticulously, and fortify preemptively. Consult agents for tailored advice matching your locale’s threats.
References
- Does Home Insurance Cover Tornado Damage? — Progressive. 2024. https://www.progressive.com/answers/does-home-insurance-cover-tornado-damage/
- Does Homeowners Insurance Cover Tornado Damage? — Openly. 2024. https://openly.com/the-open-door/articles/does-homeowners-insurance-cover-tornado-damage
- Does Homeowners Insurance Cover Tornado Damage? — Bankrate. 2024. https://www.bankrate.com/insurance/homeowners-insurance/tornado-insurance/
- Tornado Insurance 101 — Kin Insurance. 2024. https://www.kin.com/blog/tornado-insurance/
- Does Insurance Cover Tornado Damage? — American Family Insurance. 2024. https://www.amfam.com/resources/articles/understanding-insurance/is-my-insurance-tornado-ready
- Does Homeowners Insurance Cover Tornado Damage? — NerdWallet. 2024-05-02. https://www.nerdwallet.com/insurance/homeowners/learn/does-homeowners-insurance-cover-tornado-damage
- Tornado Damage Coverage — Allstate. 2024. https://www.allstate.com/resources/home-insurance/insurance-for-tornado-damage
- Safe Rooms for Tornadoes and Hurricanes (FEMA P-320) — FEMA.gov. 2022-04-01. https://www.fema.gov/emergency-managers/risk-management/building-science/safe-rooms
- Severe Weather Data — NOAA.gov. 2025. https://www.noaa.gov/storms
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


