

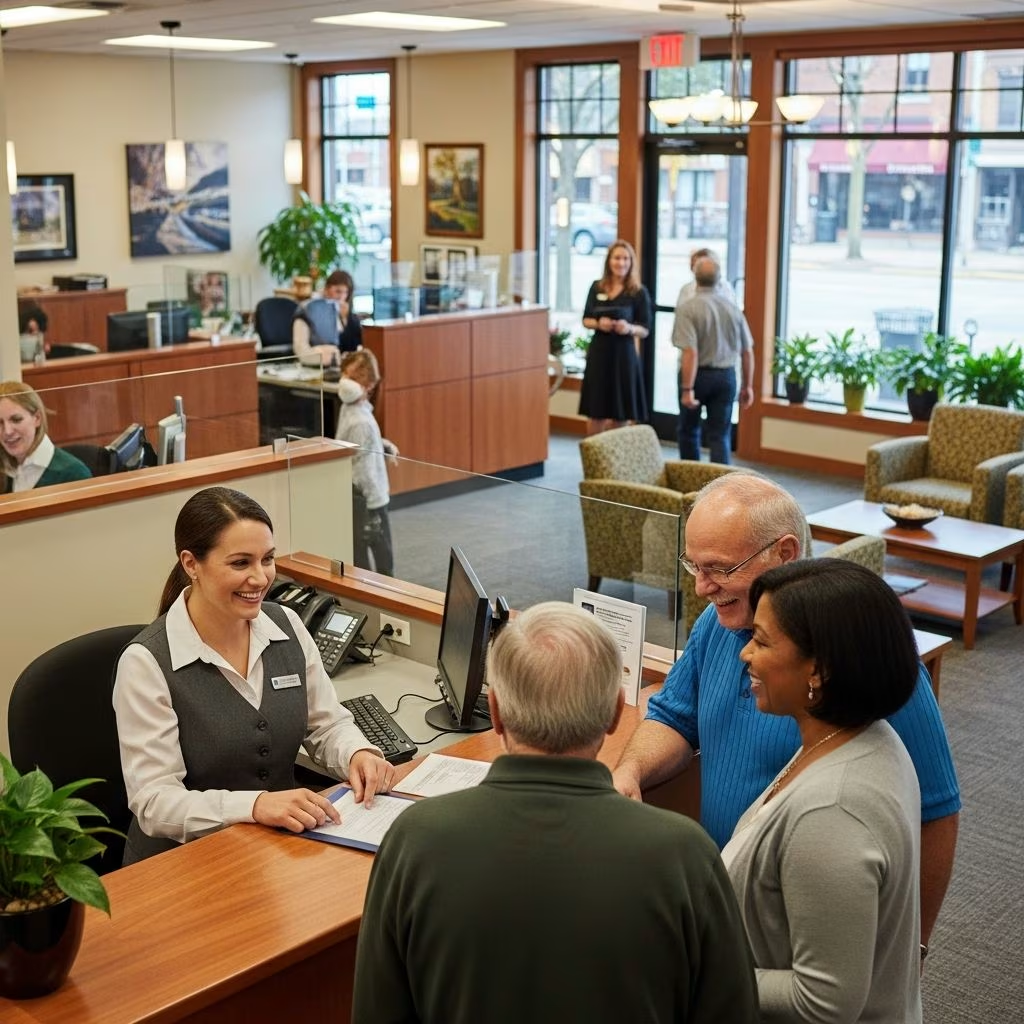
Community banks are locally focused financial institutions that prioritize serving individuals and businesses in specific regions, often with assets under $10 billion. They emphasize relationship-driven banking, local reinvestment, and customized services that larger banks may not provide as effectively.
Defining Community Banks: Core Characteristics
At their essence, community banks operate within defined geographic areas, gathering deposits from local residents and channeling a substantial portion back into the community through loans and investments. The Federal Deposit Insurance Corporation (FDIC) characterizes them as providers of traditional banking services in local settings, with many loans directed toward small businesses, commercial real estate, and agriculture. Unlike expansive national chains, these banks typically hold less than $10 billion in assets, enabling agile, community-centric operations.
This local orientation fosters deep knowledge of regional economic conditions, customer histories, and unique needs. For instance, the Federal Reserve defines community banking organizations similarly, highlighting their role in relationship lending where qualitative factors like long-term customer ties influence decisions alongside standard metrics.
How Community Banks Stand Apart from National Giants
Community banks differ markedly from large national or international banks in scale, ownership, and approach. While big banks boast vast branch networks and standardized products, community banks maintain a smaller footprint, often privately owned without shareholder pressures dictating short-term profits.
| Feature | Community Banks | Big Banks |
|---|---|---|
| Asset Size | Typically under $10B | Often trillions |
| Ownership | Mostly private/local | Publicly traded |
| Geographic Focus | Local/regional | National/global |
| Lending Style | Relationship-based | Transactional/algorithmic |
| Products | Customized for locals | Standardized offerings |
This table illustrates key contrasts, drawn from analyses by Experian and the FDIC, showing how community banks tailor services to everyday people, including low- to moderate-income borrowers, whereas larger institutions focus on corporate-scale lending.
The Power of Local Decision-Making
A hallmark of community banks is decentralized authority, where loan approvals and financial products are decided by staff familiar with the area. This contrasts with national banks, where distant corporate offices handle approvals using rigid criteria. Local decision-makers can consider community-specific factors, such as seasonal agricultural cycles or small business growth potential, leading to more flexible lending.
According to the FDIC’s community banking studies, this expertise enables higher credit access in rural and underserved areas. Customers benefit from quicker responses and approvals that account for personal histories rather than solely credit scores.
Personalized and Relationship-Driven Service
Community banks excel in “relationship banking,” treating customers as individuals rather than account numbers. Staff often live in the same communities, building trust over years. This model assesses creditworthiness holistically, blending quantitative data like debt ratios with qualitative insights from ongoing interactions.
- Direct Access to Leaders: Speak with loan officers or executives who hold decision-making power.
- Tailored Advice: Customized plans for mortgages, business expansion, or personal savings.
- Community Knowledge: Understanding of local job markets, real estate trends, and economic drivers.
Such personalization is rarer at big banks, where automated systems dominate.
Driving Local Economic Growth
By reinvesting deposits locally, community banks stimulate economies. They fund small businesses, farms, and home purchases, creating jobs and stability. The FDIC’s 2020 study noted their critical role in commercial real estate and agricultural lending. Banking locally means your money supports neighbors, not distant projects.
Edward Jones highlights that these banks derive most deposits from their operating areas, ensuring high recirculation rates. This impact extends to sponsoring events, charities, and development initiatives, enhancing community well-being.
Available Services: Matching Big Banks with a Local Touch
Don’t mistake smaller size for limited offerings. Community banks provide checking/savings accounts, loans, mortgages, credit cards, online banking, and investment advice—often with competitive rates due to lower overhead.
- Personal and business checking accounts with low fees.
- Home equity loans and first-time buyer programs.
- Small business lines of credit with flexible terms.
- Digital tools like mobile apps and secure online platforms.
Customization shines here; a local farmer might get seasonal loan adjustments unavailable elsewhere.
Advantages of Choosing a Community Bank
Opting for a community bank yields tangible benefits:
- Higher Approval Odds: Relationship knowledge aids non-traditional borrowers.
- Lower Costs: Fewer fees and personalized rate negotiations.
- Stronger Security: FDIC insurance up to $250,000 per depositor.
- Community Support: Your patronage bolsters local vitality.
- Personal Rapport: Friendly service from known faces.
Experian emphasizes local investment and personality as top pros.
Potential Drawbacks and Considerations
While advantageous, community banks have limitations. Fewer branches mean less convenience for travelers, and they may lack advanced tech like 24/7 chatbots. Product variety is narrower, and rates might not always beat online-only banks.
However, for those valuing personal service and local impact, these trade-offs are minimal. Always verify FDIC membership and compare rates.
Finding and Evaluating Your Community Bank
Locate options via FDIC’s BankFind tool or local directories. Assess by visiting branches, reviewing online reviews, checking fees, and inquiring about loan processes. Ask: Do they know local needs? What’s their community involvement?
Key questions for prospects:
- How local are lending decisions?
- What small business support do they offer?
- Can I meet decision-makers easily?
Real-World Impact: Success Stories
Community banks power stories like a rural entrepreneur securing startup funding based on local reputation, or families achieving homeownership through flexible mortgages. Their role in small business lending is outsized relative to size, per Federal Reserve data.
FAQs About Community Banks
What qualifies as a community bank?
Generally, banks with under $10 billion in assets, local focus, and relationship lending.
Are deposits safe?
Yes, insured by FDIC up to $250,000.
Do they offer online banking?
Most do, with robust mobile and digital services.
Can I get business loans easily?
Often yes, thanks to local expertise and flexible criteria.
How do fees compare?
Typically lower, with negotiable terms.
References
- What Is a Community Bank? — SouthEast Bank. 2023. https://www.southeastbank.com/knowledge-hub/money-management/banking/what-is-a-community-bank/
- What is a Real Community Bank? — Farmers National Bank. 2023. https://www.farmersnationalbank.bank/what-is-a-real-community-bank/
- What Is a Community Bank? — Experian. 2024-02-06. https://www.experian.com/blogs/ask-experian/what-is-community-bank/
- The Community Bank — First American State Bank / FDIC 2020 Community Banking Study. 2020. https://www.firstamericanstatebank.com/the-community-bank/
- Community Banking 101 — Edward Jones. 2020-09. https://www.edwardjones.com/sites/default/files/acquiadam/2020-09/community-banking-101.pdf
- FDIC Community Banking Study – Chapter 1 — FDIC. 2012. https://www.fdic.gov/resources/community-banking/report/2012/2012-cbi-study-1.pdf
- The Critical Role of Community Banks — Federal Reserve Bank of Kansas City. 2023. https://www.kansascityfed.org/banking/community-banking-bulletins/the-critical-role-of-community-banks/
This article is general information, not personal financial advice. Consider your own situation, or speak with a licensed adviser, before acting on it.


